The Question Behind the Question
When founders search for how to find investors for a startup, they are rarely asking a simple directory question. They are asking something harder: how do I get in front of the right people, earn their interest, and convert that interest into a check — without losing six months and torpedoing my company in the process?
The answer starts with a distinction that most guides skip entirely. “Finding investors” is not one problem. It is three separate problems stacked together: identifying who the right investors actually are for your specific company, creating the conditions for a real conversation with those people, and managing the full process well enough that momentum builds instead of stalls. Each problem requires different skills, different tools, and a different allocation of your most limited resource — time. This guide works through all three, with enough specificity to be genuinely useful and enough honesty to tell you what it actually costs.
Investor Type Determines Everything Before Outreach Begins
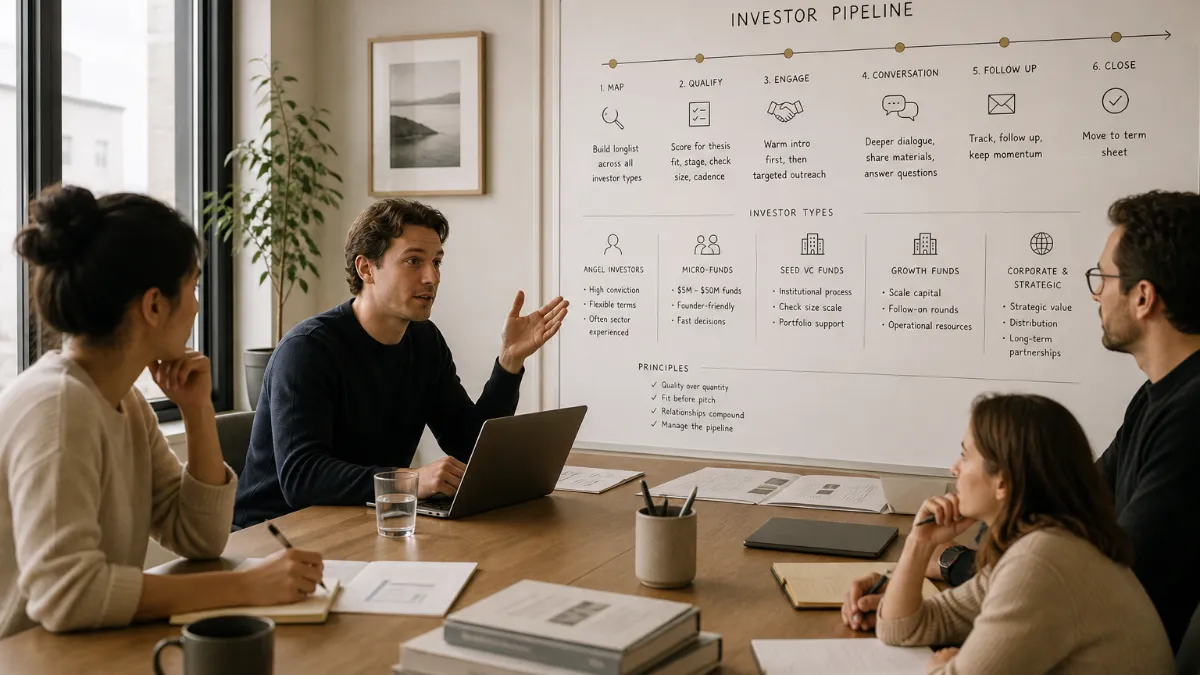
The single most common mistake early-stage founders make is treating “investors” as a monolithic category. Before you write a single email or build a single spreadsheet, you need to understand who you are actually targeting — because angel investors, micro-VCs, institutional VCs, and family offices operate on fundamentally different check sizes, stage mandates, thesis filters, and decision timelines.
Angel Investors
Angel investors typically invest $10,000–$250,000 at the earliest stages, often pre-seed or bridging into seed. They are usually individuals — former founders, operators, or executives — deploying their own capital, which means decision timelines can be short and terms are often simpler. Because they are investing personal money, they tend to be more thesis-driven by personal experience than by fund mandates. An angel who built a B2B SaaS company will lean toward B2B SaaS founders; an angel who scaled a marketplace will look for network-effects businesses. The practical implication: finding the right angel means identifying people who have lived your problem, not just people who write checks.
Micro-VCs and Seed Funds
Seed checks from institutional funds typically run $500K–$3M at $5M–$20M post-money valuations, and the bar has risen meaningfully since 2023: working product, $10K+ MRR, or named-founder credentials. Micro-VCs and seed-focused funds are often the first institutional check into a company. They have fund mandates, LP commitments, and portfolio construction targets that shape when and how they deploy. Unlike Series A and beyond — where funding cycles have grown significantly longer — seed funding has remained relatively active, and investors view this stage as an opportunity to enter high-potential companies at more reasonable valuations. Seed funds vary enormously in focus: some are sector-agnostic, others concentrate exclusively on climate tech or developer tools or fintech. Researching the fund structure and the specific partner’s domain matters as much as confirming the check size.
Institutional VCs
Series A and beyond involves institutional VCs managing hundreds of millions to billions of dollars. Their process is longer, their diligence is deeper, and their bar for pattern recognition is higher. They are looking for a repeatable revenue engine, a defensible market position, and a management team that can credibly scale. They will not lead a round on a promise — they need evidence. Approaching an institutional VC too early is not just a missed opportunity; it can permanently tag your company as “not ready” in a partner’s mental model, making a second approach awkward even when your metrics have moved significantly.
Family Offices
Family offices manage wealth for high-net-worth families, have flexible mandates, longer time horizons than traditional VCs, and occasionally deep domain interest in specific sectors. They are harder to find through standard databases and almost always require a warm introduction to reach productively. For founders in sectors where patient capital matters — deep tech, biotech, climate — family offices are worth mapping deliberately rather than leaving to chance.
The Startup vs. Small Business Distinction
One clarification that saves founders real pain: startup investors and small business investors are different populations with different expectations. Startup investors expect equity, exponential growth, and an exit — they are buying a small piece of a potentially enormous outcome. Small business investors may prefer debt instruments, revenue share agreements, or slower, more predictable return profiles. Conflating the two audiences in your outreach — or pitching a lifestyle-oriented business to a VC expecting a billion-dollar exit — wastes everyone’s time and signals that you do not understand the investment landscape you are operating in.
Building a Qualified Target List Before You Contact Anyone
Most founders build their investor list backwards: they find a database, export a few hundred names, and start emailing. The conversion rate on this approach is close to zero, for a simple reason — volume without qualification is noise.
The right approach is to build a short, tight, deeply researched list before any outreach begins. The target is 40–60 investors who have demonstrably funded companies like yours — in your sector, at your stage, at your check size, within the last 18–24 months. A list of this quality will dramatically outperform a spray-and-pray list of 500, because every conversation you start is with someone who has already proved, through their own portfolio decisions, that your type of company interests them.
Start With Databases — But Don’t Stop There
Platforms like OpenVC let founders search 20,000+ verified investors — including venture capitalists, angel investors, and family offices — build target lists, send pitch decks, and track their pipeline in one place. Crunchbase, PitchBook, and AngelList serve similar discovery functions. These databases are necessary starting points, but they are not sufficient. A name in a database tells you that an investor has invested somewhere, sometime. It does not tell you whether they are actively deploying capital right now, whether their fund is in its investment period, or whether their current thesis still maps to your category. The real research layer comes from stacking three additional signals on top of the database entry.
Thesis recency. Has the investor written, spoken, or posted publicly about your problem space in the last 12 months? An investor with an old thesis post about fintech and a portfolio full of fintech from 2018–2020 may have moved on entirely. Recency signals active interest far better than historical activity.
Portfolio composition. Look at the companies they have backed in the last 18–24 months. Are there clear analogues to your business — similar business models, adjacent markets, comparable team backgrounds? A single portfolio parallel is a signal; three portfolio parallels is a pattern worth acting on immediately.
Fund age and status. A fund that closed its flagship vehicle in 2019 and has not announced a new vehicle is likely in harvest mode, not investment mode. Founders who reach out to funds past their active deployment period waste weeks on conversations that will never convert to a term sheet.
Signals That an Investor Is Actively Deploying
Indicators of active deployment include: a recently announced new fund, investments made in the last six months visible in public databases, active social presence commenting on deals and market developments, and participation in recent demo days or pitch events. When you find an investor who checks all of these boxes and whose portfolio includes companies that look like yours, you have found a qualified target worth genuine research investment.
Warm Introductions: The Highest-Conversion Path
The data on this is consistent enough that it barely needs arguing: a warm introduction from a trusted source converts to a first meeting at multiples of the rate that cold outreach achieves. Investors receive hundreds of cold pitches per week and most go unread. A message that arrives with the implicit endorsement of someone they trust cuts through all of that friction immediately.
Portfolio Founder Introductions
The most powerful introduction you can get to an investor is from a founder in their current portfolio. These founders have a direct relationship with the partner, built through board meetings and operational check-ins, and their word carries genuine weight. Start by identifying which companies in your target investors’ portfolios are at a stage and scale where a peer founder conversation makes sense. Reach out honestly — not to ask for an intro immediately, but to compare notes, share something useful, and build a real relationship. When the time comes, an intro request that follows genuine mutual value is easy to make and easy to receive.
Advisors and Operators
Advisors who sit on multiple boards or who have long-standing relationships with investors in your target set are another high-conversion introduction path. The key is identifying advisors who have a real relationship with your target investors — not just a LinkedIn connection, but a history of co-investment, board overlap, or direct personal contact. A warm introduction from someone the investor respects but barely knows is warmer than cold outreach, but it is not as powerful as an intro from a true trusted source.
Your Own Network, Mapped Systematically
Before concluding that you do not have warm introduction paths, map what you actually have. Take your list of 40–60 target investors and, for each one, ask: who in my first or second degree network has a real relationship with this person? LinkedIn’s mutual connections feature is a starting point, but the better approach is to ask people in your network directly: “I am talking to [X fund] — do you have a genuine relationship with anyone there?” The answer will surprise you more often than you expect. Most founders significantly underestimate the introduction paths already available to them before they start.
Cold Outreach: When It Works and Why It Usually Doesn’t
Once you have exhausted genuine warm introduction paths, cold outreach is viable — and sometimes the only path to certain investors. The critical word is personalized. Cold outreach works when it demonstrates real research and genuine specificity. It fails when it is templated, generic, and clearly written to be sent to hundreds of people at once.
An investor who has published a thesis piece about B2B infrastructure, made three investments in vertical SaaS in the last 18 months, and publicly commented on your specific market at a recent conference is a strong cold target — but only if the email references those specific things. An email that opens with “I see you invest in B2B software” signals that the founder has done no real research, and the message is closed before the second sentence. The anatomy of effective cold outreach is simple, even if the execution is not:
- A specific reason why you are reaching out to them, not investors generally. Reference a portfolio company, a thesis statement, a public comment, a shared connection, or a publicly known investment thesis — something that could only have been written to this person.
- A one-sentence description of what you do. Not your vision, not your market size — what you do, for whom, and the sharpest proof point you have that it matters.
- The ask. A specific, low-friction request: a 20-minute call. Not a pitch meeting, not a commitment — a conversation.
- Nothing else. Attachments, pitch decks, and multiple paragraphs of company history do not increase reply rates. They decrease them.
Managing the Pipeline: Why Momentum Requires a System
One of the least-discussed dimensions of fundraising is the operational burden of running parallel processes. If you are managing 50 investor conversations simultaneously — across different stages of engagement, different response timelines, and different information requests — the cognitive load is substantial. Without a system, things fall through the cracks. Follow-ups that do not happen are deals that die in silence.
A disciplined pipeline tracks every investor through clear stages: researched → contacted → replied → meeting scheduled → meeting completed → diligence → decision. Each stage transition requires a defined action. When a conversation stalls in silence, the system tells you when to follow up and what to say, rather than leaving it to memory and instinct.
Tools like Foundersuite are designed specifically for managing investor pipelines — tracking contacts, conversations, and follow-ups in a CRM built for fundraising rather than sales. Whatever system you use, the discipline matters more than the tool: a spreadsheet that you actually update every day outperforms sophisticated software that you open once a week.
The Follow-Up Problem
Most investor conversations that die do not die because the investor said no. They die because no one followed up. Investors are managing dozens of active portfolio companies, LP relationships, and prospective deals simultaneously. A founder who sends one email and interprets silence as rejection is making a systematic error. The protocol that works is simple: one follow-up after seven days if there is no reply; one more after another ten days; then a graceful close that leaves the door open. Three touches, no more — persistence past that becomes friction.
The True Cost of DIY Fundraising
Everything described above — building a qualified list of 40–60 investors, layering thesis research and portfolio analysis on top of database discovery, mapping and activating warm introduction paths, writing genuinely personalized outreach for each target, following up systematically across weeks of silence, and tracking 50 parallel conversations at different stages — is a part-time job. For most Seed-to-Series A founders, it is closer to a full-time job compressed into the margins around building.
Seed-stage investment continues to show more resilience than late-stage venture capital despite a broader market reset, with U.S. seed-stage startups raising approximately $13.2 billion in 2024 — well above pre-2020 levels. The market is active, but expectations have changed, and startups that come prepared — with focus, traction, and financial discipline — will be in the strongest position to secure backing from top seed investors. Preparation includes not just product and metrics but process: founders who show up to investor conversations with a clear story, relevant proof points, and a demonstrated understanding of the investor’s thesis are perceived as more credible, not just more prepared.
The honest question for any founder is not “can I do this?” but “what does it cost me to do this, and what am I not building while I do it?” For founders who have genuine expertise in investor research, personalized outreach, and pipeline management and who can execute at the required quality level without pulling significant time from the product, self-managing is a legitimate path. For founders who cannot, the real risk is not just a slower fundraise — it is a lower-quality process that reaches the wrong investors, burns relationship capital, and fails to create the competitive dynamics that make investors move faster.
Expert-Managed Outreach: What It Should and Should Not Do
There is a growing category of services that execute fundraising outreach on behalf of founders. The quality varies enormously, and the distinction that matters most is ownership: who retains the investor relationships?
Any service model that positions itself as an intermediary — where the service owns the investor conversations, controls the communication, and extracts fees tied to introductions — creates a structural problem for the founder. Investor relationships compound over time. The investor who passes on your seed round and remembers you warmly because of a genuine conversation will take your Series A call without hesitation. That relationship, and the goodwill embedded in every touchpoint, belongs to the founder. Any model that inserts a middleman between the founder and the investor undermines the compounding value of the entire process.
What expert-managed outreach should look like is different: experienced operators doing the research, personalization, and execution work on the founder’s behalf, while every conversation and every relationship stays entirely with the founder. The founder reads every email before it goes out. The founder is on every reply thread. The investor knows they are speaking with the founder — not a service, not an intermediary, not a broker. This model treats outreach execution as a professional service, not as a relationship toll.
Rupert was built around exactly this principle. Founders raising Seed through Series A who want their outreach researched, personalized, and managed by experienced operators — without black-box processes, without hidden investor lists, and without surrendering any of the relationship capital they are building — work with Rupert knowing that every investor conversation belongs to them entirely. The work is done on the founder’s behalf; the relationships are the founder’s to keep and compound long after the round closes.
If the process of finding investors is the hardest part of your raise right now — not because you lack a compelling company, but because you lack the bandwidth to execute the research and outreach at the quality the process demands — expert-managed support is a legitimate professional choice. The question is only whether the service you choose respects the most important asset you are building alongside the product: your investor network.
Where Things Stand
The early-stage funding environment in mid-2026 is active but increasingly demanding of commercial proof over narrative promise. U.S. startups raised $19.44 billion across 492 companies in July 2026, though recent reporting notes extreme concentration — a large share of that capital flowing to a small number of late-stage deals rather than distributing evenly across early-stage companies. For seed founders specifically, most seed-stage VCs in 2026 expect a working product, $10K+ MRR or signed pilot agreements, a clear ICP wedge, and a credible 12–18-month plan to Series A milestones. Analysis of recent deal activity reinforces that investors want evidence, not broad claims: paid pilots, repeat usage, retention, pricing proof, and signs your product is hard to replace. The practical implication for founders building investor lists right now is that qualification and specificity have never mattered more — reaching the right 50 investors with a sharp, evidence-backed story will outperform reaching 500 investors with a generic deck by a wider margin than it would have in any prior vintage of early-stage funding.
See Related below for more on this topic.
See Sources below for the references behind this article.
Further reading: How to Get Investors for Your Business: A Founder’s Guide · angel investors for small business · angel investors for startups · angel investors vs venture capital · how to get investors for small business · how to get investors for your business idea · how to get private investors for your business · investors for small business · investors looking for projects to fund · types of investors for small business · investor database · pitch deck · series a · startup funding · venture capital.