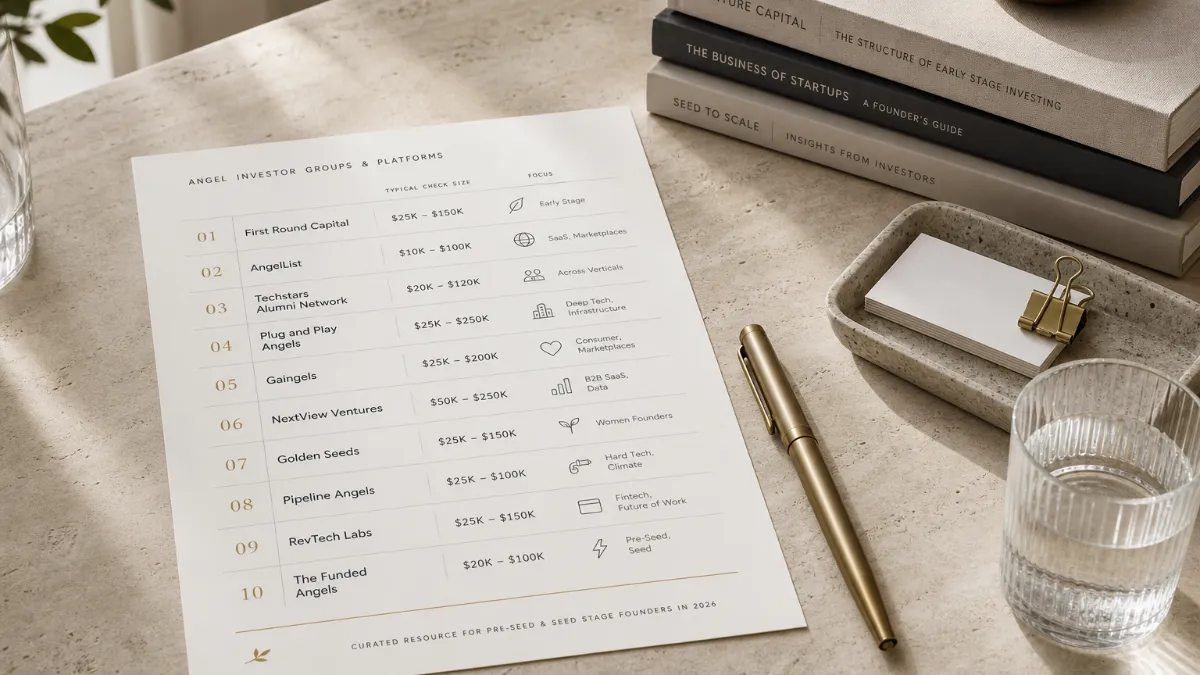
Why the Right List Matters More Than a Long One
Building a list of angel investors for your startup feels straightforward until you realize how much variety sits inside that category. Individual check sizes range from $5,000 to $500,000 depending on whether an angel is writing personal checks or pooling capital through a structured group. Application processes swing from open online forms anyone can submit to referral-only networks where a cold approach never reaches a decision-maker. The most active groups focus on technology, healthcare, and consumer sectors while deploying millions in quarterly investments , but that concentration also means there are highly active sector-specific groups covering fintech, climate, life sciences, and defense that rarely appear on generic “top angel investors” lists.
The best angel investor platforms in 2026 are not marketplaces — they’re relationship engines. The same logic applies to groups. A group that has backed three companies in your vertical over the past two years understands your customer acquisition economics, recognizes your competitive landscape, and can make introductions that move the needle. A group with no relevant portfolio history will spend your pitch session asking foundational questions about the market rather than evaluating you. Matching your outreach to groups and platforms that have genuinely funded businesses like yours is the first discipline worth building before you contact anyone.
The National Platforms: Structured Access at Scale
AngelList
AngelList launched in 2010 in San Francisco as a marketplace connecting early-stage founders with angel investors and emerging fund managers, and has since grown into a full-stack fundraising platform running syndicates, rolling funds, and institutional venture products. Today the platform spans pre-seed through Series A, covers any sector, and serves founders across the US, Europe, and Asia. For founders, its defining characteristic is distribution: AngelList is a distribution layer, not a single fund, putting your round in front of hundreds of vetted backers simultaneously — though that widening of the investor pool expands your cap table options but adds coordination work at close.
Syndicate rounds typically close in two to four weeks after a lead commits, and the fastest path to a meeting is a warm introduction from an existing AngelList-backed founder or active syndicate lead. Check sizes through syndicate structures run $25,000 to $500,000 as minority stakes, while rolling funds deploy quarterly across seven-to-ten-year hold periods.
AngelList Syndicates facilitated roughly 52% more deals in 2026, underscoring the rise of online platforms in angel investing. The platform is best suited to Delaware C-Corps raising from accredited investors; if you need a single lead writing a check above $10 million, AngelList’s distributed-syndicate model is not a fit.
Gust
Gust connects over 80 angel networks and 80,000-plus accredited investors globally, offering CRM tools, pitch deck templates, and investor relations management — making it best for founders who want to apply to multiple angel groups through a single profile. It functions less as a place where individual investors write checks and more as the administrative backbone for structured angel groups. Many formal groups — including regional networks affiliated with the Angel Capital Association — accept applications exclusively through Gust, which means creating a complete, polished profile there is a prerequisite before you approach those networks rather than an afterthought.
Republic and Wefunder
Republic and Wefunder dominate Regulation Crowdfunding (Reg CF), which allows retail investors to participate in raises up to $5 million. Republic is open to both accredited and non-accredited investors, with over 1.5 million investor accounts including those from the Seedrs acquisition, and offers equity and token-based investment options — making it best for consumer-facing startups with brand visibility.
Wefunder guides founders through the process, from a “Testing the Waters” phase to gauge interest to filing SEC paperwork and managing investor communications, making it an accessible option for founders who lack a pre-existing angel network but have a strong user base. The critical distinction: success on these platforms is tied to your ability to mobilize a community, not just appeal to a handful of professional angels. Founders with traction and a passionate user base can use early backers on these platforms as social proof to attract follow-on investment from more traditional angels.
Organized Angel Groups: Where Capital and Expertise Travel Together
The defining feature of organized angel groups is that they bring more than a check. These groups pool individual angels, share deal flow, and run a structured process that makes it easier for startups to pitch and for investors to write checks together. Members are often former operators, executives, or founders who offer introductions, due diligence support, and domain knowledge alongside capital. Beyond check size, evaluate what any group brings to the relationship — sector expertise, portfolio synergies, follow-on capacity, and willingness to make introductions are the signals that separate a high-value investor relationship from a passive one.
The Angel Capital Association Member Network
The Angel Capital Association (ACA) is the professional association of global angel investors that offers education, best practices, data, public policy advocacy, and significant benefits and resources to its membership of more than 14,000 accredited investors, who invest individually or through its 250-plus angel groups, accredited platforms, and family offices. The ACA’s member directory is the most comprehensive map of organized angel activity in the country. As the world’s largest community of angel investors, ACA represents and connects the most active seed-stage investors from around the world — and while not a direct funding source itself, ACA works with incubators, universities, economic development organizations, and others to support entrepreneurship and assist startups in their quest for knowledge about angel capital.
The practical value of the ACA directory is that it lets founders filter by geography and sector before reaching out to individual groups. The ACA member directory lists 300-plus groups across the US, filterable by state and investment focus — but presence in the directory doesn’t equal activity. Dead or dormant groups stay listed for years; active groups close 10-plus deals annually and hold monthly pitch meetings. Look for published portfolio pages with recent investment dates and check whether the group runs regular pitch forums — these are the clearest signals that a group is actually deploying capital.
Tech Coast Angels
Based in Southern California, Tech Coast Angels is one of the largest and most active angel groups in the United States, with a long track record of funding early-stage companies across many sectors and operating through regional networks — founders benefit from a structured screening and pitch process, plus access to a deep bench of experienced investors and mentors.
Through affiliation with over 50 angel groups nationwide, TCA has the ability to syndicate deals, further amplifying the opportunities it creates for startups. This syndication capability matters: a TCA investment can pull in co-investors from partner groups, which means a single pitch can generate interest well beyond Southern California.
Golden Seeds
Golden Seeds is a leading angel investment network funding women-led startups for over 20 years while building a nationwide community of experienced investors, and has surpassed $200 million invested in women-led companies since its founding — a milestone that represents one of the largest investment totals by any angel network this century and signals continued momentum around advancing gender parity in angel investing.
If your startup has women in leadership, Golden Seeds offers both capital and a community aligned with that mission, along with the rigor of an established investment process. The group operates nationally with chapters in major US cities, and its members are themselves largely operators and investors who can open meaningful doors in addition to writing checks.
New York Angels and 37 Angels
New York hosts some of the most active organized angel capital in the country, and two groups are particularly worth understanding. New York Angels runs dedicated working groups for fintech, blockchain, and life sciences , which means sector-specific screening by members who genuinely know those markets. The application process for groups in this ecosystem typically runs through an online submission, initial screening by the network’s team, a pitch forum invitation for a select few companies, a diligence process managed by a single lead investor, and a final investment decision following successful completion of diligence.
37 Angels, also based in New York, takes a founder-centric approach with structured feedback at every stage of the process. With its founder-centric approach and operational efficiency, 37 Angels provides a clear and valuable fundraising path within the New York tech scene. Both groups accept applications through Gust, and the fastest path to either group’s pitch forum is a referral from a portfolio founder or advisor already in their network.
Alliance of Angels
Alliance of Angels is an investment group based in Seattle, Washington, with over 140 angel investors, investing over $10 million in more than 20 startups annually while providing valuable mentorship services. For founders outside California and New York, the Alliance of Angels is an important proof point that highly active, well-capitalized groups operate in secondary markets. Seattle’s group has particular strength in cloud infrastructure, developer tools, and enterprise software — sectors that align with the region’s deep technical talent base.
VentureSouth
VentureSouth is one of the largest and most established angel networks in the Southeastern US, with 550-plus active investors and sidecar funds — and since 2008, it has invested over $85 million in 100-plus early-stage companies, typically writing first checks of $250K–$1M. For founders based in the Southeast, or founders with a regional presence there, VentureSouth represents the kind of well-resourced regional group that often gets overlooked by founders who default to California and New York. Its sidecar fund structure means it can participate at meaningful check sizes without requiring each individual member to independently commit capital.
The Overlooked Tier: Regional and University-Affiliated Groups
The data reveals a significant shift: traditional hub cities — San Francisco, New York, Boston — still lead in absolute numbers, but mid-market groups in Austin, Denver, Miami, and Nashville are moving faster and deploying capital more aggressively on a per-firm basis. For early-stage founders outside major hubs, regional groups — often affiliated with university ecosystems, economic development bodies, or SBDC networks — are among the most accessible entry points available.
Regional angel groups typically invest $100K–$250K per company in seed or early-stage rounds and will often co-invest with other local groups or venture firms for raises up to $2 million — and that core ticket size maps perfectly to companies raising Seed or pre-Series A rounds. Groups affiliated with research universities are particularly active in life sciences, hard tech, and enterprise software, reflecting the research and commercialization ecosystems around their campuses. Examples of university-affiliated programs active in the ACA ecosystem include the Catalyst Angel Program, TN Tri-Star Angel Program, and programs affiliated with institutions like the University of Texas at Rio Grande Valley — a reminder that this tier extends well beyond the coasts.
How to Approach Any Angel Group Effectively
Knowing the landscape is the prerequisite. Knowing how to enter it is the skill. In 2026, 68% of seed deals started with a warm introduction — founders should invest their time in building relationships with other founders who can introduce them, attending pitch events, and joining accelerator alumni networks.
The highest-leverage move before approaching any organized group is mapping your existing network against theirs. Seek warm intros from fellow founders, incubators, or business contacts, as angels favor trusted recommendations over cold outreach. Most angel group applications are technically open, but the ones that convert to term sheets almost always begin with a referral from a portfolio founder or a shared advisor. Before you submit through Gust or fill out an online form, spend a week researching who in your network has already received a check from that group.
Most angel group rounds now require 90 to 120 days from first meeting to wire transfer, compared to 30 to 45 days in 2021 — extended due diligence, tighter committee requirements, and higher revenue expectations all contribute to longer timelines, which means founders should begin fundraising with at least six months of runway remaining.
The evaluation criteria beyond check size also matter. Active groups want sector expertise they can apply to your company, portfolio synergies that create customer introduction opportunities, and follow-on capacity so they can protect their position in later rounds. Investors are looking for evidence early: clear customer demand, believable unit economics, a path to distribution, and founder judgment they can trust. A group with no relevant portfolio companies offers capital and little else. A group that has backed your three closest competitors understands your market deeply — and may be the most valuable partner you can find, or may have conflicts you need to surface early.
Running Outreach Across Multiple Groups Without Losing Momentum
Building a shortlist of the right angel groups — national platforms, organized networks, and overlooked regional groups — is the foundation. The operational layer that follows is where most founders stall. Running parallel conversations across 30 to 50 investor relationships simultaneously requires consistent follow-up cadences, personalized messaging for each group’s specific sector focus, and disciplined tracking of where each relationship sits in the pipeline. Most founders managing this process alone discover that the fundraise starts to consume the entire company: every meeting, follow-up, and data room request is time not spent building the product or serving customers.
This is the execution problem Rupert is designed to solve. Every outreach campaign is researched and personalized by experienced operators who understand what angel groups and syndicate leads respond to — and founders retain complete visibility into every conversation and every investor relationship. That combination of expert execution and full transparency means founders can engage the angel capital market at the level of quality and volume it requires, without disappearing from their own company for six months.
The result is that you show up to every group having done the work: the right introduction angle, the right framing for that group’s portfolio, the right timing given their meeting cadence. The relationships — and the cap table they build — remain entirely yours.
Where Things Stand
Angel capital markets have remained active heading into the second half of 2026, with several meaningful structural trends now clearly established. Angel investment syndicates grew by roughly 35% in 2026, reflecting a stronger preference for collaborative funding, with 40% of US angel capital now flowing through syndicates and SPVs. AI and deeptech startups captured approximately 48% of total angel deals in 2026, dominating sector allocation as AI concentration continues.
The median angel check size across the top 50 groups was $127K in Q1 2026, up from $97K in Q1 2025 — a meaningful increase that reflects both larger syndicate pools and groups writing more concentrated bets. July’s reported investments from ACA member groups highlight the continued breadth of innovation being supported, spanning advanced medical technologies, AI-powered enterprise tools, next-generation materials, robotics, wireless monitoring, and defense applications. Most angel group rounds now require 90 to 120 days from first meeting to wire transfer, with extended due diligence, tighter committee requirements, and higher revenue expectations all contributing to longer timelines — a dynamic founders raising in the second half of 2026 should plan for explicitly.
Further reading: angel investors · angel investors for small business · how to get investors for small business · investors for small business · types of investors for small business.
Sources: Learn how to find and work with angel investors · How to Find the Right Angel Investor for Your Startup · Finding and Pitching Angel Investors: A Strategic Guide ….