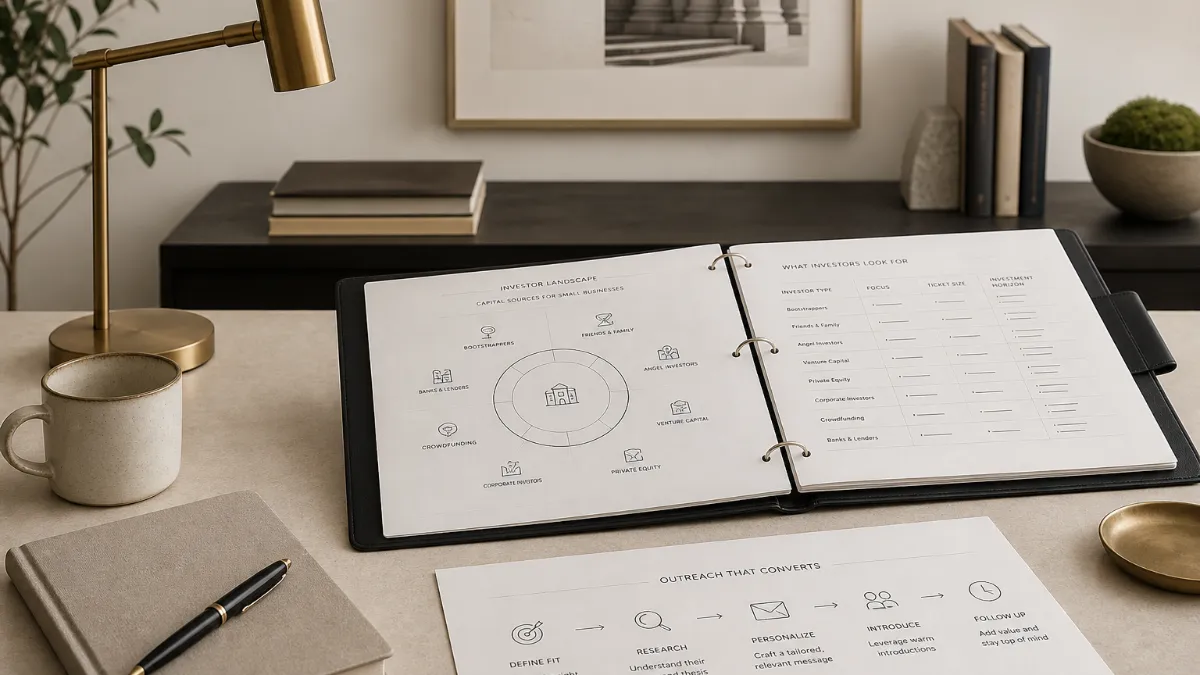
The Investor Landscape Is Wider Than Most Founders Think
When founders talk about “finding investors,” they usually mean one thing: venture capital. It’s the category that dominates the press, the podcasts, and the pitch competition circuit. But venture capital represents a narrow slice of the capital actually available to small businesses and emerging companies, and it comes with structural requirements — on growth trajectory, market size, and exit timelines — that most companies genuinely don’t fit. The result is a predictable waste: founders spend months chasing investors whose mandates were never aligned with their company, collect polite rejections, and conclude that capital is unavailable. Often it isn’t. It’s just in the wrong drawer.
Understanding the full investor landscape — who the different types are, what they actually look for, and why those differences matter for your specific company — is the first act of a serious fundraise. Everything that comes after, the list, the messaging, the outreach, only converts when the underlying fit is real.
The Main Types of Investors for Small Businesses
Angel Investors
Angels are high-net-worth individuals who invest their own money, typically at the earliest stages of a company’s life. Angel investors usually write smaller checks than venture capital firms, and they often invest at the pre-seed or seed stage with individual checks in the tens of thousands. An estimated 300,000+ active angel investors operate in the US, according to ACA and Kauffman data, with steady growth continuing into 2026.
What makes angels valuable to small business founders isn’t just the capital — it’s the speed and flexibility. An angel can make an investment decision after two conversations. They don’t have a partnership to convince or an investment committee to clear. That flexibility comes with a trade-off: angel check sizes rarely fill a round on their own, which is why syndication has grown sharply. Angel investment syndicates grew by approximately 35% in 2026, reflecting a stronger preference for collaborative funding, with 40% of US angel capital now flowing through syndicates and SPVs.
When pitching an angel, the primary signal they’re evaluating is founder conviction and market credibility — not yet the rigor of your unit economics. Research suggests angel-backed startups can have better short-term survival and hiring outcomes than similar companies without angel funding, with one study noting they were more likely to survive over the next 1.5 to 3 years and showed stronger employment growth. Angels know this, which is why they bet heavily on the person as much as the product.
Micro-VCs and Seed Funds
Micro-VCs are institutional funds, typically managing between $10 million and $75 million, that operate with more process than angels but target the same early stage. Unlike their larger counterparts, they are often led by operators-turned-investors who bring genuine domain expertise alongside the capital. The key distinction from angels is mandate clarity: micro-VCs have LPs to answer to, specific return targets to hit, and thesis constraints that shape every deal they do. Seed-stage VC funds and angel syndicates are the typical sources at this stage, and what investors expect is a working product, early users or customers, and a plausible path to product-market fit.
For B2B companies, this usually means a handful of paying customers or active pilots; for consumer, it means demonstrated retention and engagement metrics. Micro-VCs that pass on a company at the seed stage are almost never persuaded by the same pitch six months later with the same data. The bar is real, and arriving before you’ve cleared it wastes the relationship.
Traditional Venture Capital Firms
Larger VC firms — those managing $100M or more — have structural requirements that most small businesses simply don’t satisfy. Typical check sizes range from $500K at seed to $100M or more at later stages, and VC firms raise a fund with a defined size and a mandate to invest in a specific stage and sector. Because a fund of $200 million needs to return multiples of that figure to its LPs, partners can only write checks into companies that have a realistic path to a large outcome. That structural reality isn’t a bias against small businesses — it’s math. A $3 million revenue company with 20% annual growth is a wonderful business; it is not a venture-scale investment. The founders who benefit from understanding this aren’t necessarily the ones targeting large VCs — they’re the ones who stop targeting them once they understand why the fit isn’t there.
Small Business Investment Companies (SBICs)
SBICs occupy a unique and frequently overlooked position in the small business capital stack. An SBIC is a privately owned company that’s licensed and regulated by the SBA; SBICs invest in small businesses in the form of debt and equity, while the SBA doesn’t invest directly into small businesses but provides funding to qualified SBICs, which then use their private funds alongside SBA-guaranteed funding to invest in small businesses.
The program has significant reach. According to SBA data, the SBIC program has made more than 200,000 investments in US small businesses, and the SBIC portfolio closed fiscal 2025 at a record $53 billion.
A typical SBIC investment is made over a three-year period, with loans ranging from $250,000 to $10 million. For founders who want patient, structured capital without giving up the equity stakes that angels and VCs require, SBICs are worth a deliberate look. The trade-off is timeline — SBIC processes are more rigorous and move more slowly than angel or early VC deals — and sector fit matters, since individual SBICs often specialize.
Family Offices
Family offices manage the wealth of ultra-high-net-worth families and increasingly deploy that capital directly into private companies and small businesses. Family offices now oversee more than $3 trillion in assets globally, and they’re deploying that capital with far more intent than many sellers, brokers, and even advisors still assume. 70% of family offices reported making at least one direct deal in the past year, and 64% expect to make six or more direct investments over the next twelve months.
What makes family offices distinctive as investors is their time horizon. Unlike a VC fund that must return capital to LPs within a defined window, a family office can hold for decades. This makes them particularly well-suited to businesses with strong fundamentals and durable cash flows — companies that may not be on a path to a $500 million exit but represent genuinely excellent, defensible businesses. Popular sectors for family offices include artificial intelligence, SaaS, healthcare, cybersecurity, fintech, robotics, and industrial technology, often connected to the family’s own business experience. The challenge with family offices is that many source deals quietly, without public-facing websites or listed contact information. Access is almost always earned through relationship — a trusted introduction from a co-investor, advisor, or portfolio founder carries far more weight than a cold deck.
Revenue-Based Financiers
For companies that are already generating revenue, revenue-based financing (RBF) offers a non-dilutive alternative to equity investment. Rather than selling a stake in the business, founders agree to repay a fixed multiple of the capital raised through a percentage of monthly revenue. Revenue-based financing continues to expand as an alternative to traditional loans and equity rounds, with strong adoption among businesses with recurring revenue models, allowing repayment as a percentage of revenue rather than fixed monthly installments.
RBF providers are not investors in the traditional sense — they don’t take board seats, don’t have return-of-fund requirements, and won’t push for an exit. What they care about is predictable, recurring revenue and a business model that can absorb the revenue share without breaking. For founders who’ve confirmed some revenue traction but don’t want to dilute, RBF sits at the intersection of financing and investment and is worth understanding as part of the overall capital picture.
Investor Fit: The Variable Most Founders Get Wrong
The most common fundraising mistake isn’t a bad pitch deck or weak financials — it’s misdiagnosed fit. Investor fit is a function of three variables working together: your stage (pre-revenue versus meaningful traction), your growth trajectory (lifestyle business versus venture-scale), and your sector. Getting any one of these wrong sends you into a queue of investors who were never going to say yes, no matter how compelling the story.
Stage is the most legible of the three. One of the most significant funding trends in 2026 is the emphasis on profitability — in previous years many startups raised capital based primarily on growth metrics, but now investors want evidence that customers value the solution, and revenue remains one of the strongest indicators of business viability. A company with no revenue talking to seed-stage VCs who expect paying customers isn’t going to close that gap with a better narrative. They need to either build to the stage threshold or redirect to investors — angels, pre-seed funds — whose mandate includes the earlier stage.
Growth trajectory is more nuanced and more dangerous to misread. Founders often use “we could be big” as a substitute for a coherent growth model. A venture fund needs to believe your company can return the fund — which, for a $100 million fund with 20 portfolio companies, means each company needs a plausible path to $300 million or more in value. If your business is strong but structurally capped at a smaller outcome, you’re not a fit for that fund. Saying so clearly, and redirecting toward family offices or SBICs where that profile is a genuine fit rather than a consolation prize, is a better use of everyone’s time.
Sector is the third filter, and the one most easily overlooked in the abstract. Check size and activity levels depend on startup stage, sector, geography, valuation, investor experience, and whether the deal is done solo or through a syndicate. Many funds have sector exclusions — they won’t touch regulated industries, hardware, or certain geographies — that aren’t listed anywhere but are real constraints. Part of building an investor list is understanding each investor’s actual thesis, not just their stated focus.
Getting to Investors: Warm Paths Beat Cold Channels
Understanding investor types and fit is necessary but not sufficient. You still have to get in front of the right people. And here the data on what actually works is unambiguous: warm introductions convert at materially higher rates than cold outreach through platforms or email.
The logic is straightforward. Investors receive hundreds of inbound pitches. Most go unread. An introduction from a founder they’ve already backed, a mutual advisor, or a trusted co-investor instantly answers the question every investor asks first: why should I spend time on this? That answer, delivered by a trusted third party, is worth dozens of cold emails.
Founders can approach family offices through introductions from venture funds, lawyers, accountants, portfolio founders, banks, accelerators, and industry executives. The same channels apply across investor types. This means that building the network you’ll need for a fundraise is not something you begin when the round opens — it’s something you do in the twelve months before, through strategic relationship development with advisors, operators in your space, and founders who have already raised from the investors you want to reach.
None of this means cold outreach is useless. A well-researched, genuinely personalized cold email — one that demonstrates you’ve read the investor’s thesis, understood their portfolio, and have a specific, defensible reason why your company fits — can and does get responses. The key word is personalized. Generic blast campaigns that reach 500 investors with the same message produce almost nothing. Targeted outreach to 40 investors with messages tailored to each person’s stated thesis and recent investments performs meaningfully better.
Investor Readiness: The Prerequisite Nobody Talks About Enough
There’s a version of fundraising advice that focuses entirely on execution — how to write a cold email, how to structure a pitch meeting, how to build a CRM. All of that matters. But none of it saves a founder who approaches investors before they’re ready.
Investor readiness means you can clearly answer four questions before the first email goes out. How much are you raising, and at what terms or valuation? How exactly will the capital be deployed — not “for growth” but specifically, with a use-of-funds breakdown that maps to milestones? What does your current traction tell a skeptical investor about your business’s viability? And why is your team the right team to execute this, in this market, at this moment?
Startup funding in 2026 reflects a more mature and disciplined investment environment; while capital remains available, investors are prioritizing profitability, sustainable growth, efficient operations, and strong leadership teams. In that environment, a founder who can’t answer those four questions clearly trains investors to say no — and the first impression created in that conversation is difficult to undo. Investors have good memories for founders who pitched them before they were ready. When that founder returns six months later with better numbers, the prior mental model is the first thing that gets activated.
The market narrative is equally critical. “Big market” is not a market narrative. A defensible market narrative explains why your specific corner of the market is underserved right now, why your approach creates durable advantage, and why the timing is right. It should be specific enough to be argued with — because an investor who can argue with your thesis is engaged, and an investor who can’t push back on your narrative usually doesn’t believe it.
Structured Outreach: How Rounds Actually Close
Most founders treat fundraising as a series of isolated conversations. They send a pitch, have a call, wait for an answer, and move on if it’s no. That approach fails because it ignores the dynamics of how investor decisions actually get made. Investors rarely say yes after one meeting. They need to see the company over time, watch the founder respond to questions and challenges, and often need social proof from other investors in the process.
Fundraising often begins long before capital is needed. The founders who close rounds do so because they’ve been systematically building relationships with the investors they want to reach, tracking every conversation in a structured pipeline, and following up with updates — traction milestones, new customer wins, relevant market developments — that keep the relationship warm without asking for a decision before the investor is ready to make one.
This is where structure becomes a competitive advantage. A founder who tracks every investor conversation, knows exactly where each relationship stands, and follows up consistently is running a materially different process than a founder who operates from memory and intuition. The difference shows up at the close — in who converted and who drifted away during the weeks of silence that every fundraise produces.
Momentum also feeds on itself during a raise. When investors know others are looking at the company, the cognitive calculus shifts. Timing outreach so that multiple conversations are progressing simultaneously — rather than sequentially — is one of the most practical things a founder can do to accelerate a round.
Where Things Stand
Where Things Stand
The venture capital market in mid-2026 presents a sharply bifurcated picture for founders seeking external investment. Megadeals of $100 million or more captured 87.5% of the $412.7 billion deployed in H1 2026, and AI accounted for 86% of all venture dollars. Deal count is at the lowest it has been in over a decade, meaning a smaller number of mega rounds are propping up the headline totals.
Capital remains available, but it is flowing disproportionately to a small group of large, AI-focused companies, and for founders outside that circle, record funding totals should not be mistaken for an easier fundraising environment. At the same time, the investment environment is becoming more mature and disciplined, with investors prioritizing profitability, sustainable growth, and strong leadership teams — which means that investor readiness and precise targeting matter more than ever for founders who sit outside the AI mega-round cohort. Over the last couple of years there has been a lot of focus on late-stage deals, which has made it difficult for many early-stage startups, particularly those not in the AI space — a dynamic that makes investor fit and targeted outreach the primary levers available to founders raising at the seed and Series A stages.
Running the Process Like an Expert
For founders who have already confirmed their investor fit — who know which investor types match their stage, trajectory, and sector, and who can answer the four readiness questions cleanly — the remaining challenge is execution: building the right list, personalizing outreach to each investor’s actual thesis, tracking every conversation, and maintaining relationship continuity through the weeks of silence that every fundraise produces.
That execution layer is where most rounds are won or lost. Not at the pitch meeting, but in the research that preceded it, the follow-up that kept it alive, and the pipeline discipline that created momentum rather than waiting for it to appear.
For founders who have the conviction and the story but lack the bandwidth to build that infrastructure themselves, working with experienced operators who specialize in investor outreach — who handle the research, personalization, and pipeline management while the founder retains complete ownership of every conversation and every relationship — is not a shortcut. It’s a recognition that fundraising is a full-time job, and building the company is another one. Rupert is built for exactly that moment: when the fit is confirmed, the story is ready, and what’s needed is a disciplined, transparent process run by people who have done this before.
Further reading: angel investors · angel investors for small business · angel investors for startups · how to get investors for small business · types of investors for small business.
Sources: How to find investors for your small business · Guide to Finding Business Investors | CO · Tips for Pitching to Small Business Investors.