Types of Investors for Small Business: Plain-English FAQ
If you’ve recently started exploring how to raise capital, you’ve probably noticed that the word “investor” gets used to describe an enormous range of people and institutions — from a supportive family member writing a $10,000 check to a billion-dollar venture fund making multi-million-dollar bets. Treating all of them as the same category isn’t just imprecise; it leads to real mistakes: wasted outreach, mismatched expectations, and rounds that stall because a founder approached the wrong type of capital for their stage and business model.
This FAQ is designed to give you a clear, jargon-free map of the investor landscape as it applies to small businesses and early-stage companies. It won’t cover every nuance, but it will give you a working framework that prevents the most common mismatches.
What Are the Main Types of Investors for Small Businesses?
Friends and Family
The first round most founders ever raise isn’t from a professional investor at all — it’s from people who already believe in them personally. Friends and family capital is informal, fast, and usually the lowest-friction way to get initial runway. The check sizes are small (often $5,000–$50,000), documentation varies wildly, and the relationship risk is real if things go wrong.
One underrated risk with friends and family rounds is not treating them professionally. Using a simple convertible note or SAFE agreement — rather than a handshake understanding — protects both parties and avoids messy cap table confusion later when institutional investors conduct diligence.
Angel Investors
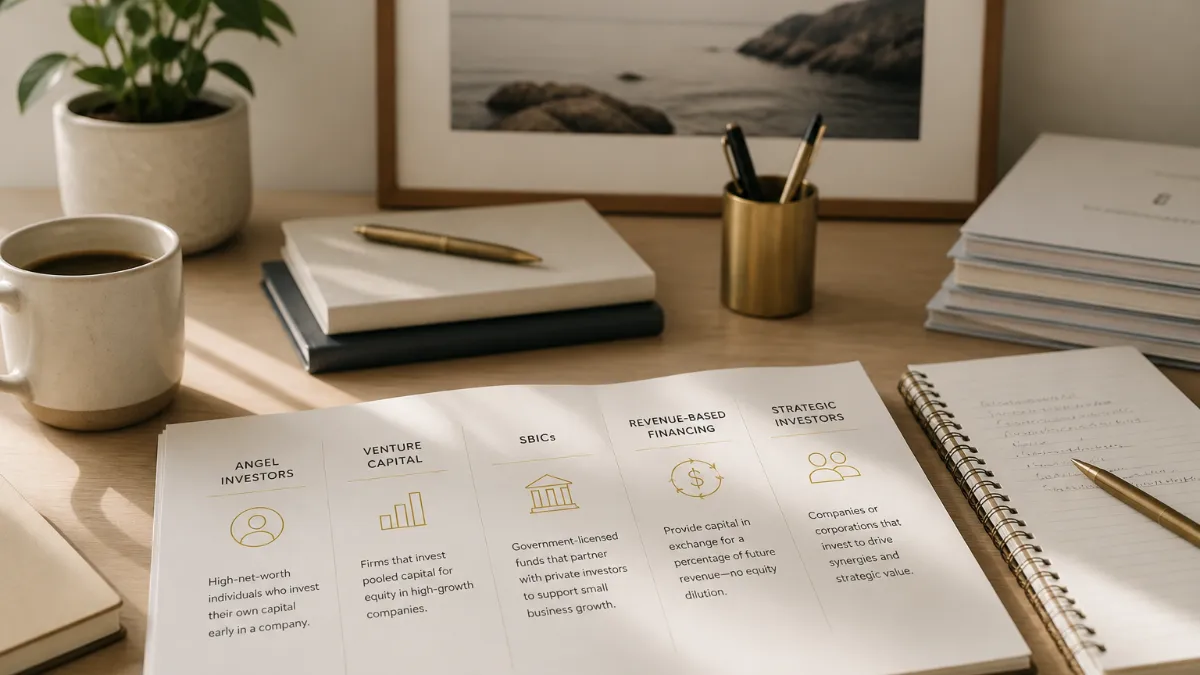
Angel investors are individuals who invest their own money into early-stage companies, typically in exchange for equity. An angel investor is an individual who invests their own personal capital into early-stage startups — they are often entrepreneurs or operators themselves, using their funds and occasionally their expertise to help founders get started. This is the key structural distinction from a venture fund: an angel is writing a personal check, not deploying pooled capital on behalf of limited partners.
That structural difference matters in practice. Unlike venture capital, angels don’t manage outside funds — they make decisions faster, move more personally, and often invest based on instinct, passion, or their network, more so than relying on formal pitch processes. For a small business founder, this means a well-targeted angel outreach can move from first conversation to signed term sheet in a matter of weeks, not months. An estimated 300,000+ active angel investors operate in the US, according to ACA and Kauffman data, with steady growth continuing into 2026. Angel investment deal sizes typically range between $25,000 and $100,000 per individual angel, with syndicates often pushing that to $250,000–$500,000 or more in recent years.
Angel Syndicates
An angel syndicate is a group of individual angels who pool their capital for a specific deal, led by an experienced operator or investor who sources and vets the opportunity. Syndicates let angels participate in deals at a scale no single check could cover, and they give founders a way to bring in multiple investors while only managing one primary relationship. For founders, a syndicate investment can feel faster and more personal than a VC process while delivering a larger aggregate check than a solo angel could write.
Micro-VCs
Micro-VCs are formal venture funds — typically managing anywhere from $10 million to $100 million in assets — that focus on pre-seed and seed-stage companies. Unlike solo angels, micro-VCs have limited partners they report to and an investment committee that signs off on decisions. This adds process and timeline, but it also means micro-VCs bring structured support: they may offer follow-on reserves, LP introductions, and a formal portfolio network. For a founder raising a seed round of $500,000 or more, micro-VCs are often the most appropriate institutional target.
Larger Venture Capital Firms
Traditional venture capital is institutional capital deployed from large funds — often $200 million to several billion dollars — with return expectations that require portfolio companies to pursue very large exits. Venture capital fundraising trends show that while the total cost of VC investments is rising, the money is being distributed across a fewer number of startups. This concentration has real implications for founders: if your business is optimized for profitable, sustainable growth rather than a path to a $500 million or billion-dollar exit, most VC funds are structurally unable to invest, regardless of how good the business is. Their LP obligations require outlier returns that a stable, profitable small business simply cannot deliver.
SBICs (Small Business Investment Companies)
SBICs are privately operated investment funds that are licensed and regulated by the U.S. Small Business Administration. They use a combination of private capital and SBA-backed leverage to invest in qualifying small businesses. The structure means SBICs can offer both equity and debt, and because of the SBA backing, they can sometimes take positions in companies that wouldn’t meet a traditional VC’s return threshold. For founders who don’t fit the hypergrowth VC model but need more than angels can provide, SBICs are a meaningfully different and underused option.
Revenue-Based Financing
Revenue-based financing (RBF) is not equity at all — it’s a capital advance repaid through a percentage of monthly revenue until a multiple of the original investment is returned. There is no dilution, no ownership transfer, and typically no board seat. RBF works best for businesses with predictable, recurring revenue. The cost of capital is higher than a traditional bank loan, but the flexibility — repayments flex with revenue rather than being fixed — makes it attractive for businesses with seasonal or variable cash flows.
Angels vs. VCs: Why the Difference Actually Matters to Your Raise
One of the most common early mistakes founders make is conflating angels and venture capitalists as the same category. The surface behavior looks similar — both write equity checks, take ownership, and expect a return — but the underlying mechanics are completely different, and those mechanics shape everything about how you should approach them.
Angels invest their own money. When an angel says yes, the decision is made. There is no investment committee, no LP approval, no portfolio construction constraint to navigate. This is why angel processes are faster and more personal. It also means angels can invest based on conviction that doesn’t fit a formal thesis — a founder they know personally, an industry they care about, a problem they experienced themselves. The flexibility cuts both ways: they can also say no just as quickly, and there’s no formal appeal process.
VCs manage pooled capital with LP obligations, which imposes a very different operating logic. For founders, current funding conditions mean fundraising is still possible, but expectations are higher — investors want stronger proof of product-market fit, disciplined burn, realistic valuations, and a credible story around growth, margins, and long-term business health. A VC partner who loves your company still has to present it to an investment committee, model a return scenario that satisfies LP expectations, and fit the deal into a portfolio construction that already has existing commitments. All of that adds time, adds conditions, and raises the minimum traction bar before a serious process can begin.
Investors are closely vetting early-stage startups to find companies with traction and massive potential. If your business has strong unit economics and real customers but isn’t chasing a venture-scale exit, the right conclusion isn’t “we can’t raise.” It’s “we need to target the right type of investor for what we’re building.”
Not Every Business Is Fundable by Every Investor Type
This is one of the most important things to understand early, and it saves an enormous amount of wasted effort. The investor type you can credibly approach is largely determined by your business model and exit trajectory, not just your traction level.
Venture capital and most institutional equity requires a credible path to a large exit — typically an acquisition or IPO at a scale that returns a significant multiple of the fund’s investment. This requirement is structural, not preferential. A VC isn’t choosing to skip your profitable local services business because they don’t like it; their fund math simply can’t work without outlier returns. Sending cold outreach to VC firms when you’re building a business optimized for stable profitability is one of the most common forms of wasted effort in early-stage fundraising.
Angels are far more flexible. Because they invest personal capital and set their own return expectations, they can fund businesses that will never go public or be acquired for a billion dollars. A business that will generate strong cash flows and potentially be acquired for $10–$30 million in five years is a perfectly attractive angel investment. The same business would be essentially unfundable by a traditional VC.
SBICs and revenue-based financers occupy the space where equity investors often won’t go: businesses with reliable revenue, real operating history, and reasonable growth — but no hypergrowth trajectory. If you’re running a business in that category, targeting these investor types first isn’t a compromise; it’s the strategically correct move.
Equity vs. Non-Dilutive: Understanding the Capital Structure Question
Every time you take outside capital, you’re making a structural choice, not just a financial one. Equity investors — angels, syndicates, micro-VCs, VCs — receive ownership in your company in exchange for their check. That ownership stakes a claim on future decisions, future proceeds, and in many cases, future rounds. Every dilutive round reduces your percentage ownership and potentially changes the governance dynamic of your company.
Revenue-based financing and SBA-backed SBIC debt are lower-dilution alternatives. They have real costs — interest, repayment multiples, covenants — but they don’t permanently alter your cap table. For founders who are highly sensitive to ownership dilution, or who are raising at a stage where equity valuation is hard to defend, non-dilutive and lower-dilution structures deserve serious consideration alongside pure equity options.
The right capital structure depends on how much control and equity you’re willing to exchange for the capital you need. There’s no universal answer — but founders who think through this question explicitly before going to market are better positioned to negotiate from strength rather than accepting whatever structure the first interested investor proposes.
Accreditation Status: What Founders Need to Know About Legal Solicitation
When you raise money from private investors in the United States, securities law applies — even if you’re raising a small round from people you know personally. The central concept founders need to understand is the accredited investor definition.
In 2026, accredited investor status is defined by rules set under SEC Rule 501 of Regulation D. The two most widely used qualification pathways are an individual income exceeding $200,000 in each of the past two years ($300,000 combined with a spouse or domestic partner), or a net worth exceeding $1 million excluding the primary residence. A third pathway — qualifying through certain professional credentials — has been available since the SEC expanded the definition in 2020.
Why does this matter to your fundraising process? Understanding these requirements matters because they determine who can participate in private investment offerings — real estate syndications, private equity funds, venture capital, and other alternative investments that are exempt from SEC registration and not available to the general public. Practically, it shapes which investors you can legally approach and how you can communicate about your raise.
Under Rule 506(b), the traditional Reg D exemption, you can raise unlimited amounts from an unlimited number of accredited investors, plus up to 35 non-accredited investors — who must be sophisticated and capable of evaluating the merits and risks of the investment. However, if you make any public announcement or general solicitation about your raise, you trigger 506(c) rules, which require all investors to be verified as accredited. This is the practical reason most founders raising a seed round avoid posting publicly about their round until it is closed: the moment you solicit publicly, your investor universe narrows and your compliance obligations increase.
The landscape here is also actively evolving. The accredited investor filter has been cracking open since 2020, and reforms are actively being drafted — if the SEC moves on inflation-adjusted thresholds, millions of current qualifiers could be pushed out, while credentialing expansions could bring millions of new investors in. Founders raising capital in 2026 should stay current on these rules and work with a startup attorney to structure their raise correctly from the start.
Finding the Right Investor Once You Know the Type
Understanding the taxonomy is the first step. Knowing that you’re targeting angels rather than VCs, or syndicates rather than institutional funds, clarifies the universe you’re working with and the approach you need to take. But clarity on type doesn’t automatically translate into a quality list of specific individuals to contact, a personalized outreach strategy, or a managed pipeline that keeps conversations moving.
The work of identifying which specific investors within a category are the right fit for your company — by sector, stage, check size, and portfolio fit — and then reaching them in a way that earns a genuine response rather than a polite pass, is where most founders lose significant time. Researching individual angels, writing personalized notes, tracking responses, and following up consistently is a full-time effort layered on top of actually running a company.
That’s precisely the gap Rupert is built to fill. Rupert’s expert-managed outreach campaigns do the research, personalization, and pipeline management on your behalf, so you’re spending time on actual investor conversations rather than sourcing and cold-email logistics. Every campaign is run by experienced operators who understand how different investor types think and what earns their attention — and the full record of every outreach, every response, and every relationship stays with you. You own the relationships. Rupert does the work to get them started.
Where Things Stand
The early-stage funding environment in mid-2026 underscores why understanding investor type fit matters more than ever for small business founders. Fundraising is still possible across categories, but expectations have risen sharply — investors want stronger proof of product-market fit, disciplined burn, realistic valuations, and a credible story around growth and long-term business health.
VC funding reached $300 billion across 6,000 startups in early 2026, with early-stage startups accounting for around 1,800 deals worth $41.3 billion — up over 40% year-over-year , but that activity is heavily concentrated in AI, fintech, and deep tech, meaning founders in other sectors must be especially precise about which investor category is actually accessible to them. An estimated 300,000+ active angel investors now operate in the US , giving non-hypergrowth businesses a large and growing pool of potential backers outside the VC system. Meanwhile, the regulatory environment governing who qualifies to invest is also in flux: the accredited investor filter has been cracking open since 2020, and reforms are actively being drafted — potential SEC moves on inflation-adjusted thresholds could push out millions of current qualifiers, while credentialing expansions could bring millions of new participants into private markets. Founders navigating outreach in this environment are best served by targeting investor types that structurally match their business model, rather than defaulting to the most visible category.
Further reading: angel investors · angel investors for small business · angel investors for startups · how to get investors for small business · investors for small business.
Sources: How to find investors for your small business · Guide to Finding Business Investors | CO · Types of Investors: A Guide for Early-Stage Startup Founders.