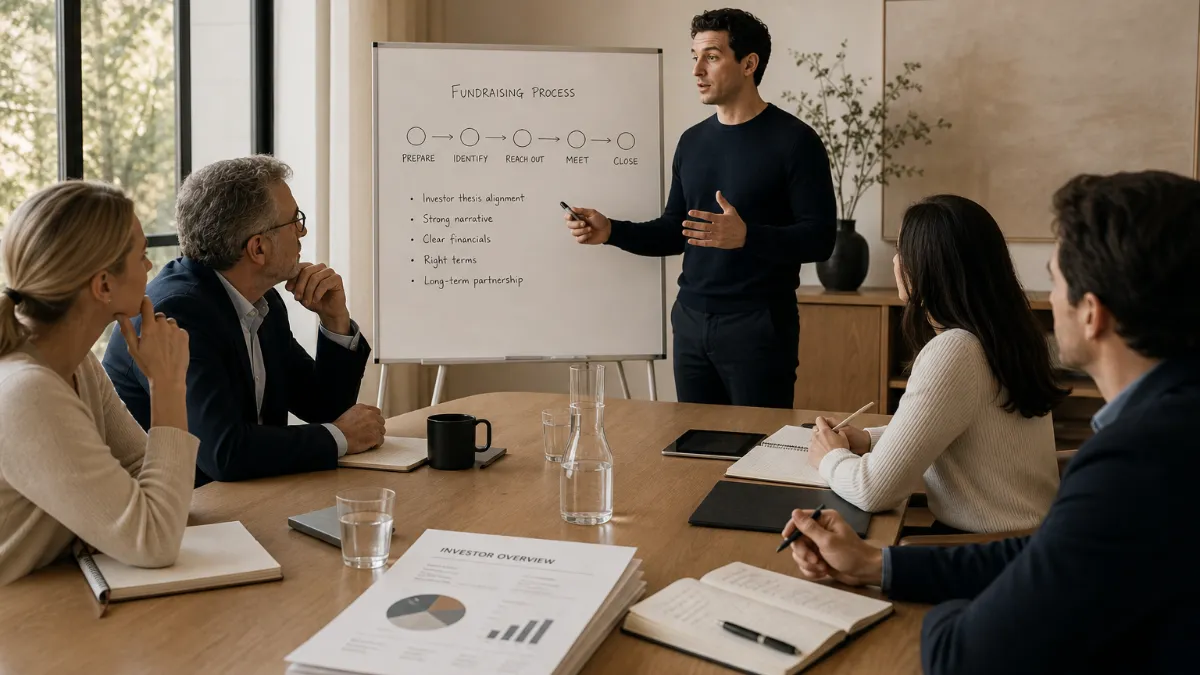
Getting investors for your business is not a single conversation — it is a structured campaign with a defined beginning, a disciplined middle, and a clear close. Founders who raise successfully do not stumble into capital through one well-timed email or a lucky coffee meeting. They treat fundraising the way a great sales leader treats a pipeline: qualified targets, consistent follow-up, and a process that creates its own momentum. This guide covers every stage of that process, from understanding which investors are right for your company to closing the round without losing months to “we’re still interested” conversations that never convert.
Know What You’re Raising — And From Whom
Before you approach a single investor, you need to understand the landscape well enough to know exactly where your company fits. Investor type is not a minor detail. It determines check size, involvement level, decision speed, and the stage of company each type is actually built to back — and pitching the wrong type wastes time you cannot recover.
Angels
Angels are individuals investing their own money at pre-seed and seed, typically writing checks in the $25K–$100K range. Because they deploy their own capital rather than a fund’s, their decision-making is faster and more personal. Paperwork is lighter and the relationship is more personal; some angels are operators who want to stay close to the ecosystem, others are financial investors looking for asymmetric returns, and a growing number are former founders who want to pay it forward. Angels are also more comfortable with thin or zero traction — they back teams and theses more than revenue lines. Angels rarely ask for a board seat at pre-seed, usually settling for an update email or an observer role, which matters enormously for founders who want to preserve governance flexibility early on.
Seed VCs and Institutional Funds
Seed stage investors, on average, deploy $500,000 to $5 million, drawing from limited partners rather than personal capital. The evaluation process is more structured than an angel’s, and the bar is higher: at seed, founders have typically settled the validation question, and investors need proof that customers use the product, pay for it, and retain it.
A VC leading a priced round typically expects a formal board seat, protective provisions, and standing information rights. For founders, that trade-off — structured capital in exchange for governance — is one of the most consequential decisions of the early company. Choose your seed investors as carefully as you would a co-founder.
Family Offices and Corporate VCs
Family offices manage private wealth and can write checks at any stage, often with longer time horizons and less pressure to mark to market than institutional funds. They are particularly valuable for founders in sectors where patient capital matters — deep tech, healthcare, climate. Corporate VCs are strategic arms of larger companies; they bring distribution, partnerships, and sector expertise, but their investment thesis is anchored to their parent company’s roadmap, which creates alignment risks worth understanding before you take their term sheet.
Knowing this landscape shapes everything: which investors belong on your list, how you approach them, what you lead with, and how long you should expect each decision to take. Pitching a $2M lead check to an angel who typically writes $10K, or an idea-stage story to a fund that only leads $3M-plus rounds, burns time and relationships you may want again later.
Get Investor-Ready Before You Start
The single most common mistake in fundraising is starting outreach before the foundation is solid. A bad first impression with a target investor is rarely recoverable — investors have long memories and short inboxes, and a “no” from a misaligned or premature pitch can close a door you needed open six months later.
Materials That Need to Be Right
Your pitch deck needs to tell a coherent story about the problem, your solution, why now, why you, and what you’ll do with the money. Keep it to 12–14 slides — investors form their first impression in under a minute. Your financial model needs to be buildable: it does not need to be a precise forecast, but it does need to demonstrate that you understand unit economics, burn, and the path to the milestone this round is funding. Your data room — cap table, incorporation documents, contracts, key metrics — should be organised before you start, because the moment a serious investor asks for diligence materials, speed of response becomes its own signal.
Knowing When You’re Ready
Most founders outreach too early. A six-item readiness rubric — financials, traction, pitch deck, founder story, unfair advantage, and growth rate — separates winning campaigns from those that just generate noise.
The average time between seed and Series A has stretched to around 616 days, and investors are not penalising founders for taking longer — they are penalising founders for raising too early with thin metrics. Rushing into market before you have a compelling data story guarantees a harder process and worse terms.
Build a Qualified Target List
Most founders build their investor list by Googling “top VCs” and pulling names from generic databases. The result is a list of 200 names with no real filter, no warm paths, and no thesis alignment. That is the spray-and-pray approach — and it converts at roughly the same rate as sending cold emails into the void.
The right approach is research-intensive but focused. Build a tight list of 60–100 funds that have led a round in your category in the last 12 months, then rank by fit and by warm path. For each name, you want to understand their check size, their stage preference, which partner would own the deal, what their current portfolio says about their thesis, and whether they have a conflict. An investor who already backed your direct competitor will not fund you. An investor whose fund is three years old and nearly deployed cannot lead your round even if they love the story.
Founders without investor segmentation see 3–5% response rates. Those with targeted lists see 12–15%. The difference is a 30-minute list-building framework and a research protocol. Qualification is not busywork — it is the highest-leverage work you will do before a single email goes out.
Build Warm Paths Before You Need Them
The data on warm introductions versus cold outreach is not subtle. Roughly 58% of VC deals originate through professional networks, co-investor referrals, or portfolio-company introductions — against just ~10% from unsolicited cold inbound.
Research consistently reveals a stark gap: warm introductions convert to a first meeting at 20–30%, while cold emails convert at 1–2%. A founder sending 100 cold emails might get 1–2 meetings; the same founder with 100 warm introductions could get 20–30.
That gap exists because of how investors process their inbox. A warm introduction works because someone the decision-maker already respects is vouching for you — that borrowed credibility lets them skip the question every cold message has to answer first (“is this person worth my attention?”) and move straight to evaluating the opportunity.
The most valuable connectors are the people already inside the VC’s trust network: the most effective path to investors runs through existing investors in your company, then founders in the investor’s portfolio, then mutual connections like advisors or accelerator contacts, with cold outreach as a last resort. An introduction from a current investor carries significantly more weight than one from a distant LinkedIn connection, because they have capital at stake and their reputation on the line.
Building these relationships before you need them is the single highest-leverage pre-fundraise activity. Attend events where investors and their portfolio founders are present. Make introductions for other people — reciprocity is real and remembered. Be genuinely useful in your ecosystem before you ask it to be useful for you. Founders who arrive at the start of their raise with a warm path to 60–70% of their list are in an entirely different position from those who are cold everywhere.
When Cold Outreach Is Your Only Option
Cold outreach can work — particularly at pre-seed and seed, where some investors actively seek undiscovered companies — but it demands exceptional personalization. Reference the investor’s portfolio, their content, or a specific reason they’re the right fit. Generic templates get deleted. Lead with your strongest metric in the first two sentences, make the opportunity obvious immediately, and keep it to four to six sentences — VCs decide in seconds whether to keep reading.
Run a Disciplined Outreach Campaign
Getting investor meetings is a campaign, not a series of one-off events. The founders who close rounds do not drift through casual coffee chats for six months — they run a time-boxed, structured process with defined waves, consistent follow-up, and a close date that creates real urgency.
Launch in Parallel
The most important tactical choice in fundraising is to schedule first meetings in a compressed window — ideally within two to three weeks — rather than sequentially. Running parallel conversations within one to two weeks creates competitive tension and prevents information asymmetry where later investors know earlier ones passed. When investors believe they are competing for a spot in your round, the dynamic changes: responses come faster, diligence moves faster, and the conversations you do have carry more weight.
Follow Up Systematically
Most deals are not closed in the first email — or the first meeting. Send two to three follow-ups spaced five to seven days apart; most responses come from follow-ups, not initial emails.
This structure turns silence into meetings, and it is why most founders miss capital by not following up. Silence is not a no. A well-timed, relevant follow-up that adds new information — a new customer win, a retention milestone, a press mention — reactivates stalled conversations and demonstrates the forward momentum investors are betting on.
Track Everything
Run your fundraise the same way you would run a sales pipeline. Every investor needs a status, a next action, and a date. Conversations that go dark need a follow-up trigger. Partners who requested materials need a check-in. If you are tracking 60 conversations in your head, you will drop the ball on the ones that matter most. A simple CRM or even a well-structured spreadsheet is not optional — it is the difference between a process and a hope.
Create a Real Close Date
Define a date by which you intend to close the round, then communicate it consistently. A close date is not an ultimatum — it is a signal that you are running a process, not an open-ended search for capital. It creates the urgency that moves investors from “we’re interested” to “send us the SAFE.” Without a close date, rounds drift. With one, the final weeks of a campaign compress in a way that can turn three soft commitments into a closed round.
What a Successful Round Actually Looks Like
A typical seed round sits at around $2.0M at the median, stepping up to $9.0M at Series A. The economics of seed investing have changed dramatically since the AI boom began: seed rounds are larger than ever, with some startups now raising $8M–$10M deals once associated with later stages. Understanding where your round sits relative to these benchmarks matters — it shapes how many investors you need, what dilution to model, and how ambitious to be about lead check size.
The environment rewards companies with strong fundamentals. Investors are leaning into efficiency, repeatability, and real value creation rather than pure velocity. The founders who close in this environment come prepared: qualified investor lists, investor-ready materials, warm intro paths in place, and a process that runs on a defined timeline rather than optimism.
Where Rupert Fits
All of the above — building a qualified list, researching each investor, crafting personalised outreach, managing follow-ups, tracking a 60-name pipeline — takes significant time and expertise to do well. For most founders, that time comes directly out of what should be their primary focus: building the product and talking to customers.
This is where Rupert was built for you. Rupert’s experienced operators research your investor universe, personalise every outreach to specific thesis and portfolio fit, and manage the full campaign on your behalf — while you retain complete visibility into every conversation and own every investor relationship directly. There is no black box: you see what goes out, who responds, and what each conversation looks like. The relationships built are yours to keep.
If you have the story, the product, and the traction — but not the bandwidth to run a disciplined, expert-level fundraising process alongside everything else you are managing — Rupert is the infrastructure that closes the gap.
Where Things Stand
The fundraising environment for Seed and Series A founders has intensified further as of late summer 2026. Global venture capital hit a record $510 billion in H1 2026 alone — already approaching the entire 2021 peak — but the concentration has deepened sharply: AI now captures roughly 86% of U.S. VC dollars, with OpenAI and Anthropic alone accounting for 43% of all H1 funding. Over 40% of seed and Series A investment has gone to rounds of $100 million or more, compressing the available pool for everyone else. For founders outside AI, the Series A bottleneck has worsened: only about 15% of seed-funded startups from 2022–2023 cohorts converted to a Series A within two years, down from 30%+ for 2018–2020 cohorts, and the median time from seed to Series A now stands at 616 days. Median seed rounds have risen to the $4.5–5.5M range. Investors remain active at early stages, but the bar is unambiguous: proven unit economics, clear defensibility, and demonstrated customer demand are now the minimum — not differentiators — for getting a serious conversation started.
See Related below for more on this topic.
See Sources below for the references behind this article.