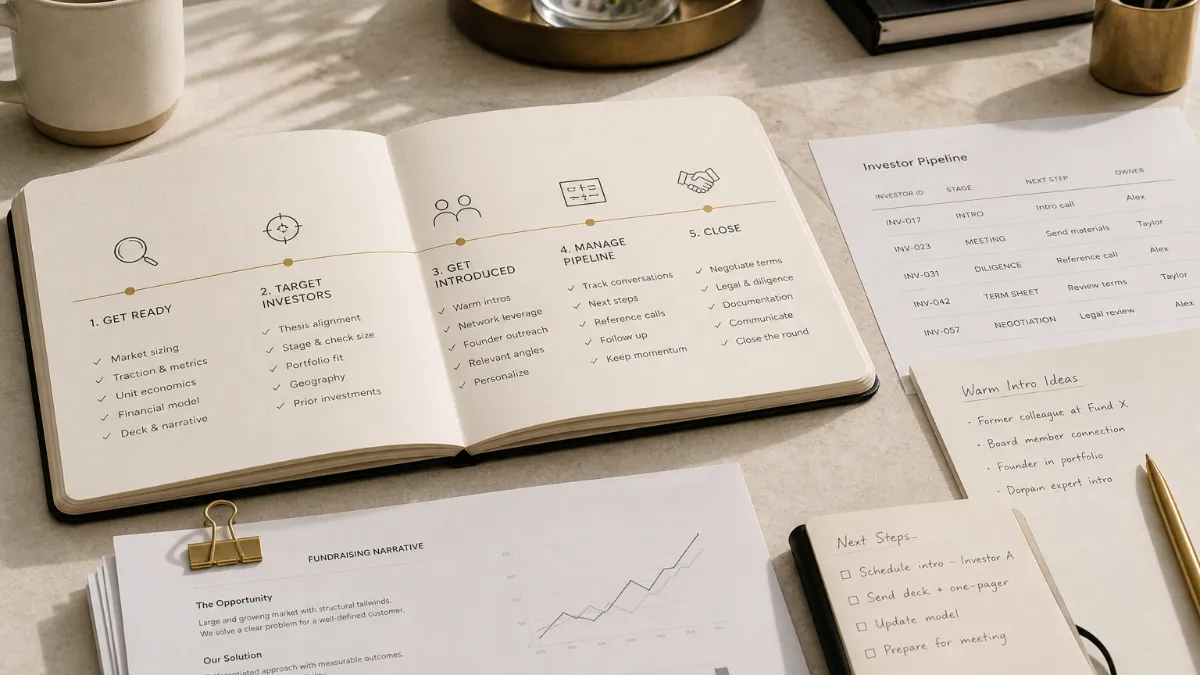
Before You Send a Single Email, Audit Your Readiness
Raising capital is not a marketing exercise. It is a qualification process — and investors are doing the qualifying. Before you send your first outreach message, the most valuable hour you can spend is an honest audit of what an investor will actually see when they look at your company.
Investors evaluate four things in quick succession: the credibility of the team, the size and shape of the market, the traction signals that prove the idea is working, and the clarity of how you intend to use the money. A gap in any one of these does not just reduce your odds with a given investor — it can stall the entire raise before it gains momentum, because early passes circulate quietly through networks.
Team credibility does not require famous names. It requires a coherent answer to the question: why is this the right group to win this market? If that answer is murky, sharpen it before you start outreach. On the market side, investors are not looking for large markets in the abstract — they want to see that you have thought carefully about the specific wedge you are entering and how it expands. For traction, even modest signals matter: pilot customers, letters of intent, week-over-week growth in a metric that correlates with revenue, or early retention data. What investors are pattern-matching is evidence that someone other than you believes this is real. Finally, use-of-funds clarity is chronically undervalued. “Grow the team and build product” is not a use-of-funds statement. Knowing that $1.8M gets you to a specific milestone — a dataset licensed, a sales hire made, a compliance filing completed — communicates operational maturity and tells the investor exactly what they are buying. Founders who walk into outreach with all four of these tightened are fundamentally easier to fund.
Build a Targeted Investor List, Not a Large One
The instinct at the start of a raise is to compile every investor name you can find and begin working through the list. That instinct is expensive. A list of 200 poorly matched investors generates friction, produces discouraging pass rates, and consumes weeks of follow-up time that should be spent building the business.
A focused list of 40 to 60 genuinely matched investors consistently outperforms volume. The matching criteria are not complicated, but they require research. Start with stage fit: a pre-seed angel writing $25K–$150K checks operates with entirely different thesis logic than a seed-stage VC targeting $1M–$3M leads, which in turn differs from a Small Business Investment Company structured around debt-equity hybrids. Pitching the wrong vehicle for your stage is one of the most common and most avoidable errors founders make.
Sector expertise is the second filter. Targeting investors whose focus and thesis align with your startup is crucial — venture firms have become highly selective, backing startups that fit precisely into their sweet spot of stage, industry, and business model. An investor who has never backed a company in your space may still write a check, but the probability is lower, the diligence will be slower, and the post-investment value they add will be thinner. Prioritize investors who have written at least one check in your sector at your stage within the past 18 to 24 months.
Recent deal activity is the third filter, and it is often overlooked. A firm that closed its flagship fund three years ago and is now in harvest mode is unlikely to lead your round regardless of how well you match their thesis on paper. Check fund vintage, recent announcements, and whether partners at the firm have been active at conferences or on social platforms — investors who are actively deploying tend to signal it.
Once your filtered list is built, tier it. The top tier consists of investors you are genuinely excited about and who have a high match score. The middle tier is strong but not ideal — useful for creating momentum and urgency. The bottom tier is backup. Work the tiers in sequence rather than blasting all 60 simultaneously, so that early conversations can surface objections you can address before the most important meetings.
Warm Introductions Are Infrastructure, Not a Nicety
A warm introduction to an investor dramatically boosts your odds of getting in the door. This is not a soft social preference — it reflects how deal flow actually works inside most firms. An investor who receives 500 cold emails per week and three warm introductions will read the three warm introductions first. The cold emails are triaged by pattern-match and subject line. The warm introductions are read because someone whose judgment they trust has vouched for the quality of the opportunity.
For every name on your investor list, map the warm path before you default to cold outreach. Start with LinkedIn and look for second-degree connections between yourself, your advisors, your co-founders, and the investor. The most valuable introduction source is often a founder in that investor’s existing portfolio — someone who has already earned the investor’s trust and whose reference carries genuine weight. If you can identify one or two portfolio founders willing to make brief introductions on your behalf, those introductions will outperform dozens of cold emails.
Engaging investors before you formally pitch is another underused strategy. Following their writing, commenting thoughtfully on their posts, attending events where they speak, and introducing yourself without a pitch attached — these interactions create familiarity that transforms a cold email into something closer to a warm one. The best outcomes come from building momentum before you reach out, working your warm paths first, and using cold outreach as a strategic fallback rather than your opening move. Founders who treat warm-path cultivation as ongoing relationship infrastructure — not a pre-raise scramble — enter each raise with a dramatically shortened runway to first meeting.
When a warm path genuinely does not exist, cold outreach can still work, but only when it is specific. A good email has a hook, a real reason for reaching out, a short value proposition at a high level, your team and traction, a hint at how much of the round is already committed, and a clear call to action. Generic cold emails that read like they were sent to 200 people perform exactly as poorly as they deserve to.
Structure Every Touchpoint as a Step in a Managed Process
The most common failure mode in investor outreach is not a bad pitch — it is a disorganized process. Founders send an email, wait, follow up once, get no reply, and quietly move on. Investors, meanwhile, are not ignoring them out of malice; they are managing an inbox and a calendar under constant pressure. The founders who advance through the funnel are those who treat each touchpoint as a deliberate step in a sequence, not a one-off message.
Structure the outreach sequence explicitly. The initial email is not a pitch — it is a request for a conversation, supported by just enough credibility and traction to earn the meeting. If there is no response within five to seven business days, a brief, confident follow-up is appropriate. When the meeting is secured, prepare a focused narrative for the call itself: your opening should answer the “why you, why now, why this market” question within the first few minutes, before the investor’s attention fractures. Immediately after the meeting, send a concise post-meeting memo — a one-pager summarizing what you discussed, what questions came up, and the specific next step you agreed on. This document alone distinguishes you from the majority of founders who leave meetings without a clear follow-up artifact.
Investors pattern-match professionalism against the hundreds of founders they have seen before. A founder who arrives prepared, communicates clearly, and follows up without being pushy signals something important: that this is a person who will operate with similar discipline once the investment is made. The founders who handle fundraising best don’t romanticize it — they run a process, protect time, and establish a strong position before they ask anyone for a check.
Track the Pipeline Actively and Use Momentum Strategically
A fundraising pipeline that lives in your head will leak. Investor conversations that feel warm in week two go cold by week six if there is no active follow-through, and by the time you resurface, the partner who was interested has moved on to another deal. Pipeline management is not optional — it is the operational backbone of a successful raise.
Build a simple tracker with at least four fields for each investor: current status, next action, the date of last contact, and a notes column that captures the specific objection or question raised in the last conversation. Status labels can be as simple as “to contact,” “in conversation,” “due diligence,” “passed,” and “closed.” The point is not sophistication — it is that you have a live view of where every conversation stands and what needs to happen next to move it forward.
Active pipeline management also enables one of the most powerful dynamics in fundraising: momentum. When one investor signals strong interest or commits, that information — shared tactfully with other investors who are in the consideration phase — creates genuine urgency. Most investors are not trying to lead; they are trying not to miss. Visible momentum from a credible co-investor can accelerate decisions that might otherwise drift for months. Compressing outreach into a defined window generates parallel conversations and competitive tension — stretched timelines kill momentum. Pipeline management is what makes that compression possible, because you can only run parallel conversations if you have visibility into all of them simultaneously.
Getting the Process Right — and Getting It Done
Knowing the process for how to get investors for a small business and executing it with consistency are different skills. The process described here — readiness audit, targeted list, warm-path mapping, structured touchpoints, active pipeline tracking — is not complicated in principle. What it requires is time, sustained attention, and the kind of operational discipline that is genuinely difficult to maintain when you are also building a product, managing a team, and serving customers.
Most founders at the Seed or Series A stage are not lacking a compelling story or a fundable company. What they are short of is bandwidth. The outreach cadence slips. The follow-ups get delayed. The pipeline tracker falls behind. Investor conversations that should have closed in eight weeks drift into five months, and the raise that should have built momentum instead limps across the finish line.
This is precisely where an experienced team running the fundraising operation on your behalf changes the outcome. Rupert is built for founders who have the product and the story but need a disciplined, professional process executed consistently — investor research, personalized outreach, warm-path mapping, meeting scheduling, and pipeline tracking, all managed by experienced operators who have run these campaigns before. Crucially, every investor conversation and every relationship stays entirely yours. Founders retain complete visibility into the process and full ownership of the connections being built. The outreach is handled; the company and the relationships remain the founder’s. If the raise is the priority and time is the constraint, that is exactly the trade-off Rupert is designed to solve.
Where Things Stand
Venture capital deal flow has remained active through August 2026, with seed and Series A rounds continuing to close across sectors including enterprise software, health technology, and AI infrastructure. The broader funding environment reflects a more mature and disciplined investment climate — while capital remains available, investors are prioritizing profitability, sustainable growth, efficient operations, and strong leadership teams. For founders actively planning a raise, this selective posture reinforces every step in the process above: in 2026, a spray-and-pray approach to investor targeting is not only inefficient — it is likely to fail, and targeting investors whose focus and thesis align with your startup has become crucial. Recent data also confirms that warm introductions remain the fastest path into an investor’s serious consideration, with cold outreach continuing to function primarily as a fallback rather than a primary channel. There are no significant structural shifts in the mechanics of investor outreach from the past 45 days — the fundamentals of readiness, targeting, and process discipline remain the defining variables between rounds that close and rounds that stall.
Further reading: angel investors · angel investors for small business · angel investors for startups · investors for small business · types of investors for small business.
Sources: How to find investors for your small business · Guide to Finding Business Investors | CO · Tips for Pitching to Small Business Investors.