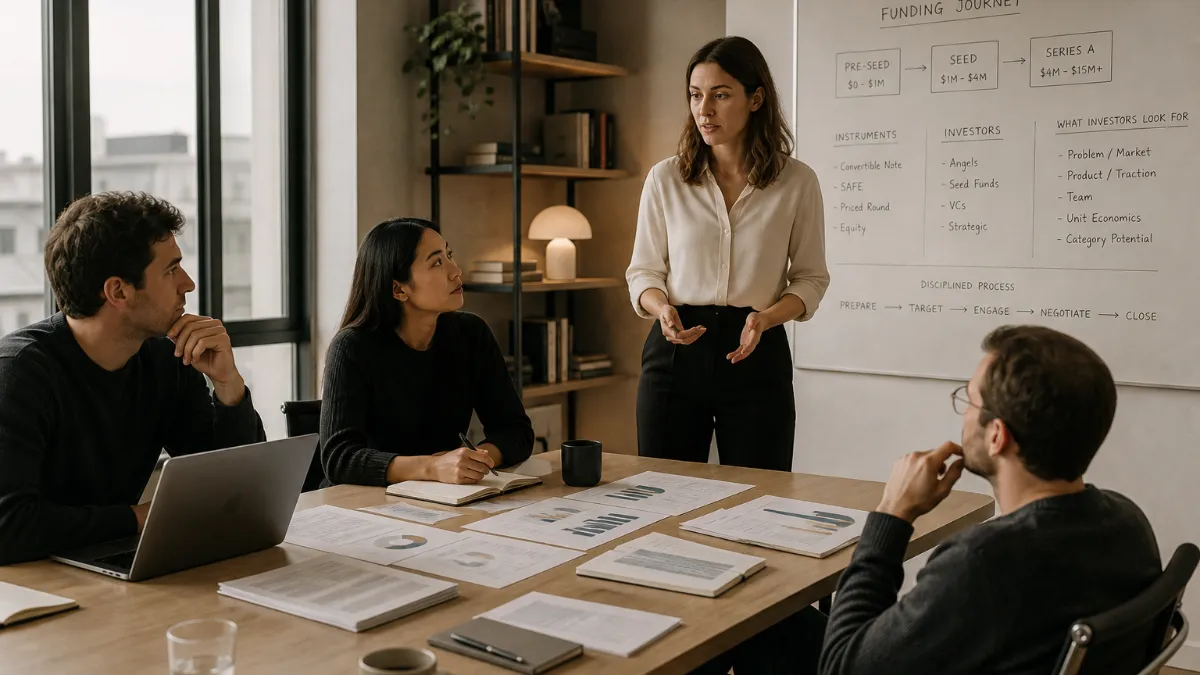
What Startup Funding Actually Is — and What It Isn’t
Startup funding is not a single event. It is not a pitch competition prize, a government grant, or a bank loan with repayment terms. At its core, startup funding is a structured exchange: a founder offers investors equity — ownership in the company — in exchange for capital that accelerates growth faster than revenue alone could support. That exchange happens in discrete stages, each with its own investor type, risk profile, milestone expectation, and financing instrument. Understanding this architecture before you walk into a room — or send a cold email — is what separates founders who raise efficiently from those who spend six months in unproductive conversations.
The mistake most first-time founders make is treating fundraising as a single episode. In reality, each round is a chapter in a longer story, and every chapter has to be written for a specific audience. A pre-seed investor is underwriting a person and a hypothesis. A Series A investor is underwriting a repeatable business motion. Conflating the two — showing up to a Series A conversation with pre-seed evidence, or vice versa — is one of the most efficient ways to burn credibility with investors you may need later.
This guide covers the full landscape: what each stage of startup funding looks like, which instruments apply at each stage and why, what investors are actually evaluating, how the 2026 market has bifurcated in ways that affect founders differently depending on their category, and what a disciplined fundraising process looks like in practice. If you are approaching a pre-seed, seed, or Series A raise, read the entire guide before you start. The pieces are interconnected in ways that matter.
The Funding Stages: What Each Round Is Actually Buying
Pre-Seed: Funding the Founder
Pre-seed is the earliest formal stage of startup financing. At this stage, there is typically no product, no revenue, and no proof that the market exists in the form the founder imagines. What exists is a founder — ideally with a credible background — a thesis about a problem worth solving, and some early signal that others agree the problem matters. The check sizes are small: the 2026 median pre-seed raise sits at around $1 million , with most rounds structured as a stack of individual SAFE notes from angels and micro-VCs rather than a single institutional check.
The investors who show up at pre-seed are making a fundamentally different kind of bet than those who appear at later stages. At pre-seed, investors are betting on the founder and the possibility — there is typically no revenue, often no product, and sometimes no customers. That means the diligence is heavily qualitative: domain expertise, founder-market fit, the team’s ability to move fast, and the quality of the insight behind the idea. Founders often underestimate how much pre-seed investors are reading these signals relative to the pitch deck itself.
Pre-seed de-risks two things: the team and the concept. If a pre-seed raise succeeds, it means enough credible people believe those two risks are manageable. Everything else is still open.
Seed: Funding the Hypothesis
Seed is where startup funding enters a more structured phase. By the time a company reaches a seed raise, investors expect to see a working product, early users or customers, and some evidence that the problem is real and the proposed solution is resonating. A typical seed round is $2.0M at the median , though the market has been moving upward — in Q4 2025, the median seed round size rose to about $4 million , reflecting a broader trend toward larger checks into fewer companies. Seed rounds typically dilute founders in the range of 18–25% , though this figure can climb significantly when multiple pre-seed SAFEs convert at the same time.
The seed round de-risks the product and the early market. Investors at this stage want evidence that the product works and that at least a narrow wedge of the target market is willing to pay for it, use it consistently, or both. They are not yet funding scale — they are funding the answer to: does this work, and do real customers care?
Series A: Funding the Machine
The simplest way to keep the stages straight: pre-seed funds the founder, seed funds the hypothesis, Series A funds the machine. By Series A, investors expect a repeatable, defensible go-to-market motion — not just evidence that some customers like the product, but evidence that the company knows how to acquire customers predictably at an acceptable cost. The median U.S. Series A deal was $15 million last year, with the upper quartile at $25 million, and that trend has continued into 2026 with median Series A rounds moving still higher.
The bar to reach Series A has moved significantly. Series A investors expect roughly $1M–$2M ARR with strong growth of 50–100% year-over-year and clean unit economics — and that bar has hardened. More specifically, the median ARR needed to raise a Series A has risen to approximately $3.5M at top-tier funds , a figure that would have been considered Series B territory just a few years ago. The Series A de-risks the go-to-market motion: can this company acquire customers in a repeatable, scalable way?
Series B and Beyond: Funding Scalability
Series B and later rounds move the question from “can we find customers?” to “can we scale?” At this stage, the company has proven a repeatable business model and is using additional capital to scale the team, expand into new markets, and build the infrastructure that a larger business requires. The typical Series B sits at $20M at the median , and valuations at this stage are substantial. The de-risking at Series B is about scalability: can the economics hold as volume increases?
Funding Instruments: Choosing the Right Vehicle for Your Stage
The amount of capital you raise matters. But the structure of how you raise it — the legal and financial instrument — has long-term consequences for dilution, cap table health, and your ability to raise future rounds. Founders who focus only on the dollar amount without understanding the instrument they are signing are leaving real value on the table.
SAFE Notes: The Default at Pre-Seed and Seed
The Simple Agreement for Future Equity (SAFE) has become the dominant early-stage financing instrument, and for good reason. A SAFE has no interest and no maturity date, making it one of the most attractive fundraising options for early-stage startups. Unlike convertible debt, it does not accrue interest or create a liability on the balance sheet. Unlike a priced equity round, it does not require a formal valuation negotiation or an expensive legal process.
The market has converged on SAFEs with striking speed. At the pre-seed stage, SAFEs comprised a record high of 93% of all deals on Carta in Q1 2026, while convertible notes fell to a record low of just 7% of pre-seed rounds. In 2025, the majority of early-stage rounds under $4 million were completed using SAFEs or convertible notes.
Two terms inside a SAFE carry the most weight for founders: the valuation cap and the discount rate. The valuation cap is the maximum pre-money valuation at which the SAFE investor’s capital will convert into equity when a priced round occurs. The cap protects early investors from excessive dilution if the startup raises its priced round at a far higher valuation — and from a founder’s perspective, the cap determines exactly how much ownership the early check costs. In 2026, the median post-money SAFE valuation cap sits at $6M–$10M at pre-seed and $10M–$15M for non-AI startups, while AI and ML companies command a 2–3x premium, with pre-seed caps reaching $12M–$25M.
The mechanics founders most often miss: if you stack multiple SAFEs before a priced round — each with its own cap — they all convert at once, and the cumulative dilution can be materially higher than any individual instrument suggests. Modeling the full conversion waterfall before signing each new SAFE is not optional.
Convertible Notes: Now a Niche Tool
Convertible notes were once the standard bridge instrument, but they have been largely displaced by SAFEs at the early stage. Convertible notes have fallen to just 7% of pre-seed deals, carrying legal overhead including an interest rate, a maturity date, and potential downside if the company never closes a priced round — SAFEs win on speed almost every time now. Convertible notes remain appropriate in specific contexts — certain regulated industries, international deals with different legal standards, or situations where the investor requires the maturity mechanism — but they are no longer the default.
Priced Equity Rounds: When Institutional Capital Arrives
Priced equity rounds — where a formal valuation is set, lead investors negotiate terms, and new shares are issued — become standard as round sizes grow. Among larger deals, priced rounds predominate; just 20% of seed deals larger than $5 million are SAFEs, while 70% are priced equity. Priced rounds involve more legal complexity: term sheets, investor rights agreements, board seats or observer rights, and anti-dilution provisions. That complexity is appropriate at the scale where institutional investors are writing meaningful checks and expecting governance in return.
Venture Debt and Revenue-Based Financing
Equity is not the only option, particularly for companies with predictable revenue. Venture debt — typically available to companies that have already raised a priced equity round — provides capital without additional dilution, in exchange for interest payments and warrants. Revenue-based financing offers capital in exchange for a percentage of future revenue until a multiple of the original investment is repaid. These instruments are powerful for specific use cases: extending runway between rounds, financing receivables, or funding growth in businesses with strong unit economics. Founders should understand these alternatives exist before assuming equity is the only path.
The 2026 Market: A Bifurcated Reality
The headline numbers in the 2026 venture market can be actively misleading for founders trying to benchmark their raise. Roughly $425 billion flowed into startups in 2025, and about 50% of it went to AI-related companies — which sounds like a strong market, but for most early-stage founders it signals tighter competition, slower access, and a funding picture much narrower than the headline implies.
The bifurcation is real and consequential. Seed-stage AI startups generally command valuations about 42% higher than non-AI peers, because investors believe AI startups can grow faster. Meanwhile, the conversion rate from seed to Series A has dropped from roughly 50% to around 38%, and investors are underwriting to profitability paths they were ignoring a few years ago. More than ever, VCs want proof of user growth, revenue, profitability, or breakthrough technology before writing big checks — and the enormous focus on AI means other industries must compete harder.
For non-AI founders, the market in 2026 requires a materially stronger evidence package at each stage than was required in 2021. Key investor evaluation metrics in 2026 include ARR growth rate of 30–100%+ for early stage, net revenue retention above 100%, gross margin above 65% for SaaS, burn multiple below 1.5x, and CAC payback period under 18 months — with capital efficiency metrics receiving far more scrutiny than during the 2020–2021 growth era.
The AI premium also distorts benchmark data in ways that trap founders. Carta’s Q4 2025 data put the median seed post-money at a record $24M, and the Q1 2026 PitchBook-NVCA Venture Monitor put the median Series A deal at $19.6M with a $78.7M post-money — but much of that increase is concentrated in AI deals, and non-AI Series A rounds are still pricing closer to a $40–42M pre-money. Using the blended median as a benchmark when you are not an AI company will lead to overpriced rounds and damaged relationships with investors who will do the math before you do.
Understanding the valuation implication in the other direction is equally important: raising at too high a valuation at seed creates a Series A math problem. If your seed post-money is $24M and you have not materially outperformed expectations by the time you approach Series A, you will either face a flat round or a down round — both of which complicate future raises and team morale. Valuation is not validation.
What Investors Are Actually Evaluating
Every investor evaluates the same core questions, but the weight assigned to each shifts dramatically by stage. Knowing which risk category your current stage is primarily designed to address — and pitching to that — is the difference between a meeting that goes somewhere and one that ends in polite silence.
At pre-seed, investors are primarily evaluating team and thesis. Is this founder capable of executing on this insight? Does the insight reflect a genuine understanding of a real problem? Is the market large enough to matter at scale? At seed, the weight shifts to product and early market evidence. Does the product work? Are early customers staying, paying, and referring? At Series A, the weight shifts again to process and scalability. Is there a repeatable acquisition motion? Are unit economics sustainable? Can the team hire and execute at the next level of complexity?
These are not just bigger checks as you go — they are completely different investments, with different evidence requirements, dilution expectations, and evaluation frameworks at each step. Pitching the wrong story to the wrong stage investor does not just result in a “no” — it wastes a relationship you may need later in a different context.
Beyond stage-matching, investors evaluate the quality of the process itself. A well-constructed, research-backed target list signals that the founder understands the venture ecosystem and is running a disciplined raise. A spray-and-pray list — mass emailed to every fund that has ever invested in a vaguely adjacent company — signals the opposite. Investor targeting precision is one of the highest-leverage activities in any raise. Mismatching stage, sector, check size, and geography with the wrong investor is one of the most common — and most avoidable — reasons founders fail to close rounds they should have won.
The Seed-to-Series A Gap: The Hardest Filter in Startup Funding
The gap between closing a seed round and successfully raising a Series A is where the majority of venture-backed startups stall. The Series A conversion rate — the share of seed-funded companies that raise a priced Series A within 24 months — sits at roughly 15–20% as of 2026, according to Carta and Pitchbook cohort data. That figure is down from roughly 30% for the 2018 cohort, leaving 70–85% of seed-funded startups that never graduate to a priced Series A.
The causes are structural. The bar has risen from a strong team and deck to roughly $1M–$2M ARR growing 3x year-over-year, while seed deal volume far outpaced the growth in Series A capacity.
While companies funded at the seed stage are typically raising larger checks, they are also taking longer to move on to Series A and face lower odds of graduating to that phase at all — since 2023, U.S. startups have been taking longer to raise a Series A following an initial seed round of $1 million or more, with that time frame now stretching to more than two years.
The implication for seed-stage founders is direct: the seed round is no longer a sign that you are on your way — it is the beginning of a two-year sprint to hit a specific set of metrics that are higher than they have ever been. Founders raising big seed rounds without a path to Series A metrics are setting themselves up for the graveyard.
Most founders who do not make it across are not failing because of the product. They are failing because of the process: insufficient pipeline of Series A relationships built during the seed stage, poor targeting of investors who are actually active and interested in their category, weak narratives on the metrics that matter at that stage, and inadequate time spent on fundraising relative to what the task demands. These are execution failures, not product failures — and they are almost entirely preventable with the right systems and support in place.
What a Disciplined Fundraising Process Looks Like
Founders who treat fundraising as a part-time activity between product sprints consistently underperform those who treat it as a parallel discipline with dedicated time, structured systems, and clear process ownership. Managing a fundraise while also managing a company is one of the hardest operational challenges in the startup lifecycle. Most founders underestimate both the volume of work and the precision required to do it well. A disciplined process has a small number of specific components that distinguish it from an ad hoc approach.
Define the target list with precision. Before any outreach begins, build a researched list of investors who are genuinely likely to invest: right stage, right sector, right check size, active fund not in harvest mode, and no undisclosed conflicts from portfolio companies. A focused list of 50–80 well-matched investors will consistently outperform a list of 300 weakly matched ones. The quality of the list determines the ceiling on the process.
Warm introductions over cold outreach. Investor response rates to cold email from unknown founders are low enough to be statistically irrelevant at most stages. The goal of network development activity — which should begin 6–12 months before you plan to raise — is to generate warm introductions from people the investor already trusts. Roughly 30% of Series A leads come from prior seed backers , which is why maintaining consistent, high-quality investor updates to your existing investors is not a courtesy — it is a pipeline strategy.
Sequence and parallelize meetings. The dynamics of a fundraise reward momentum. Running meetings sequentially — waiting to hear from one investor before approaching the next — destroys that momentum and extends the process by months. The standard approach is to create a compressed window where multiple investors are seeing the company at approximately the same time, generating competitive pressure and forcing decisions on a reasonable timeline.
Maintain a managed pipeline. Every investor conversation needs to be tracked: current status, last contact, next action, and timeline. Without a pipeline management system — whether a simple spreadsheet or purpose-built software — investors fall through the cracks, follow-ups miss optimal timing, and the founder loses situational awareness of where the round actually stands.
Set a fundraising timeline and defend it. Startup fundraising rounds typically take 3–6 months from first outreach to close for seed and Series A rounds, with due diligence periods in the current environment extending to 6–10 weeks for institutional rounds. Founders who enter a raise without a clear sense of their own timeline — and without the discipline to protect it — let investors stall, let runway compress, and end up negotiating from weakness. Plan for 4–5 months, start 12–18 months before you expect to need the capital, and treat time as your scarcest asset.
Keep investor updates consistent and metrics-led. Monthly investor updates — shared consistently with existing investors and, where appropriate, with prospective investors who have opted into your communications — build the relationship and the data trail that a future lead investor will use to evaluate you. Founders who disappear between raises are fundraising from cold every time. Founders who maintain consistent, transparent communication are fundraising from warm.
Why Execution Is Where Fundraising Is Won or Lost
Understanding the architecture of startup funding — the stages, the instruments, the market dynamics, the investor evaluation criteria — is the necessary foundation. But it is not sufficient. The gap between a founder who understands the landscape and a founder who closes a round in 60 days is almost entirely execution.
Running a disciplined fundraise requires research, personalization, pipeline management, consistent follow-up, and the cognitive overhead of tracking dozens of relationships simultaneously — all while running a company. Founders who try to manage this entire process alone, without dedicated bandwidth or experienced support, routinely leave rounds unclosed that they deserved to win. Not because the company was not fundable, but because the process was not run well enough.
This is where working with experienced operators — people who have run fundraising processes before, who know how to research investors, personalize outreach at scale, and manage a pipeline without letting relationships go cold — pays for itself many times over. The key distinction to insist on: any support should be transparent, not a black box. Every conversation, every investor relationship, and every piece of outreach should remain visible to and owned by the founder. The goal of expert support is to amplify the founder’s process, not replace the founder’s presence in it.
Rupert is built specifically for this problem. Founders who work with Rupert retain complete visibility into every investor conversation and own every relationship — nothing is hidden, nothing is abstracted away. Experienced operators handle the research, the personalization, and the pipeline management that consume time a founder cannot afford to lose. The result is a raise that runs like a professional process without the founder stepping away from the company to run it. If you are approaching a seed or Series A and want to raise with the precision the 2026 market demands, that combination is worth having.
Where Things Stand
The startup funding market in mid-to-late 2026 continues to reflect deep concentration rather than broad recovery. U.S.-based startups on Carta raised $3.19 billion across more than 11,500 pre-seed instruments in Q2 2026, compared to $3.22 billion across 14,825 instruments in Q2 2025 — similar total dollars but materially fewer deals, as the average instrument size in Q2 2026 reached $276,000, a 27% year-over-year increase and a record high over the past four-plus years. At the growth end of the market, in the week of August 3–10, 2026 alone, global startups raised over $6.9 billion across 53+ tracked rounds, with the U.S. accounting for approximately $4.58 billion — but global VC funding in 2026 is concentrated rather than distributed, with fewer deals but larger individual checks, and the mega-round trend has accelerated while seed and early-stage deal volume has moderated. For early-stage founders outside the AI infrastructure cohort, the practical message is consistent: capital is clustering around companies linked to high-cost infrastructure, regulated industries, or proprietary technical work; investors remain willing to finance earlier companies but expect a sharper proof story; and the gap between a fundable company and a merely interesting idea has widened.
See Related below for more on this topic.
See Sources below for the references behind this article.
Further reading: Startup Funding Stages: The Definitive Guide for Founders · early-stage venture capital · startup funding rounds · startup funding stages explained · types of funding for startups · angel investors · investor database · pitch deck · series a · venture capital.