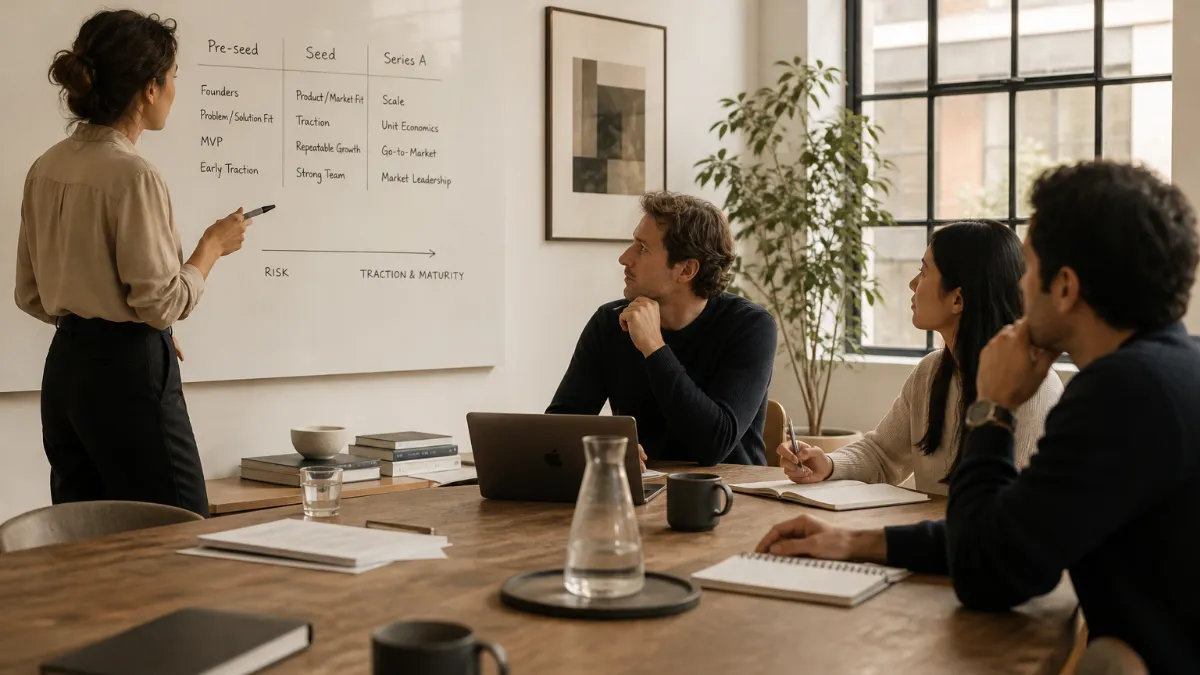
Early-stage venture capital is one of the most written-about topics in the startup ecosystem — and one of the most misunderstood. Founders approach it as though it were a single market with a uniform set of rules, when in practice it is three distinct sub-markets layered on top of each other, each with different investors, different check sizes, different evidence requirements, and different relationship dynamics. Getting your mental model right before you start outreach is not an academic exercise. It directly determines whether you spend the next three months in productive conversations or chasing the wrong funds.
What “Early-Stage” Actually Covers
The term early-stage venture capital is typically used to describe institutional investment from pre-seed through Series A — the period of a company’s life before it has proven, scalable financial performance. An early-stage venture capital firm is an institutional investor that invests in startups during their earliest phases, typically seed through Series A, in exchange for equity stakes and governance rights. Pre-seed extends that window back further still, to the moment when a founding team has little more than a thesis and early validation work.
What unites all three sub-stages is what investors are not betting on. At pre-seed through Series A, there are no audited financials, no sustainable unit economics, and often no proven repeatability in customer acquisition. Unlike traditional lenders, VC firms are not looking for predictable returns or low-risk businesses. They are making probabilistic bets on teams, markets, and ideas — which is precisely why the rules of engagement are so different from later-stage institutional capital, and why founders need to understand what evidence is appropriate to present at each step.
This is a fundamentally different game from Series B and beyond, where due diligence is anchored in financial models, cohort analyses, and proven GTM engines. At pre-seed, an investor is backing a person and a hypothesis. At seed, they are testing whether the hypothesis is becoming a business. At Series A, they want to see that the business has a repeatable model worth scaling. Treating these three moments as interchangeable — or pitching them with the same narrative — is one of the most reliable ways to generate soft passes from investors who would otherwise have been genuinely interested.
The Three Tiers of the Early-Stage VC Landscape
Understanding the landscape requires mapping it properly, because the investors operating at each tier are structurally different from one another.
Tier One: Micro-VCs and Solo GPs (Pre-Seed)
Micro-VC funds — typically defined as venture firms managing less than $50 million in assets under management — concentrate their firepower on pre-seed and seed investments and have become a dominant force in early-stage funding. Angels write $25K–$250K, accelerators write $125K–$500K, and pre-seed VCs write $250K–$2M. The structural advantage of this tier is speed and conviction: micro-VCs move in one to three weeks from first meeting to wire transfer — they don’t have Monday partner meetings with fifteen people voting. You’ll meet one or two partners who make the call.
The growth of pre-seed reflects a fundamental market dynamic: as seed rounds have ballooned to $3–5M at $15–25M valuations, founders need earlier capital to build enough traction to command those seed valuations. Pre-seed fills that gap, providing $250K–$1.5M to get from idea to initial product-market fit signals. This is an important point for founders to internalise: the pre-seed market exists precisely because the seed market moved upmarket. If you have an MVP but no meaningful traction, you are pre-seed — regardless of how far along you feel.
Tier Two: Dedicated Seed Funds
The middle tier consists of funds with $50M–$200M in AUM that write lead checks of $500K–$3M into seed rounds. These funds need to own meaningful stakes to make their model work, which means they generally want to lead or co-lead a round rather than fill out a syndicate. The median seed round size is $3–$3.2M, but the median seed post-money valuation hit a record $24M in Q4 2025, up from $18M a year earlier. At this tier, investors expect more than a strong team and a large market. They want a working product, early customer conversations, and some signal — however thin — that people will pay for what you’re building.
The seed market has bifurcated. If you have early product-market fit signals — $50K–$200K ARR, strong week-one retention, or a credible enterprise pilot — you can raise a $3–4M seed at a $15M post-money without much trouble. If you have a prototype and a vision, you are competing in a much harder pool.
Tier Three: Multi-Stage Firms with Dedicated Seed Programs
The largest firms — those with hundreds of millions to billions in AUM — have increasingly moved downmarket to participate at seed and Series A. Multistage investors with unlimited follow-on capital have increasingly invested in seed and Series A rounds, and several of the top twenty most active seed and early-stage investors are large multistage firms, who have been consistent in their increased appetite for investments in pre-Series B financings over the last two years.
This matters to founders because it changes the competitive dynamics of seed rounds. Early-stage funds split into three patterns: pre-seed/seed specialists writing $250K–$2M; multi-stage Series A leads at $2M–$15M; and corporate-VC participation at $1M–$5M follow-on. A multi-stage firm writing a $3M seed check is not doing it out of charity — they are buying the right to lead the Series A. That creates a specific relationship dynamic: if you take their seed check, their Series A is effectively your path of least resistance. That can be powerful if the partnership is right, and constraining if it isn’t.
Why Investor-Stage Fit Is the Filter Most Founders Skip
One of the costliest mistakes early-stage founders make is building a target list based on brand recognition rather than stage fit. A firm with $500M in AUM that describes itself as “early-stage” on its website may write its first institutional check at Series B. If a seed-stage founder lands a meeting with that firm, the best realistic outcome is a pass and an offer to reconnect later. The worst outcome is spending four weeks in a process that goes nowhere while consuming time and generating awkward market signals among investors who talk to each other.
The bar has risen since 2023: most early-stage VCs now require a working product, $10K+ MRR, or named operator credentials before writing the first institutional check. But the bar varies significantly by tier. What a micro-VC means by “working product” and what a multi-stage firm means by “traction” can be separated by twelve months of company-building. Stage mismatches happen because founders conflate these standards.
Most founders treat “early-stage VC” as one bucket. It’s actually three — pre-seed, seed, and Series A — typically $250K–$15M total at $5M–$80M valuations. The practical implication is that your target list needs to be filtered by fund size, recent check size, and actual stage of the last ten investments — not by what a fund’s website says. Founders close seventy percent faster when they target early-stage VCs whose check size, stage, and sector actually match — not by mass-DMing two hundred partners.
What Early-Stage VCs Actually Evaluate
Because early-stage investors are not anchored to financial performance, they evaluate founders on a different set of dimensions. Getting these right — and understanding how they shift across the three tiers — is what separates founders who consistently generate term sheets from those who get polite rejections.
Domain Credibility and Team Completeness
Investors increasingly favor founders with firsthand experience because they understand customer pain points and already possess valuable networks. This is not about credentials for their own sake — it is about a fund’s ability to believe that this specific team can outcompete every other team attacking the same problem. Solo founders pitching highly technical markets without a technical co-founder face structural skepticism not because the individual isn’t talented, but because the team has an obvious gap that will need to be filled at cost.
Market Size and Timing
Early-stage VCs are making ten-year bets. A fund’s return model depends on at least one portfolio company returning the entire fund — which means the market opportunity needs to be large enough to support a company worth hundreds of millions or more. But market size alone is not enough. Early-stage investing thrives on discipline and finding pre-consensus bets. The best early-stage investors are looking for founders who can see a market shift before it is obvious — which means timing the argument is as important as sizing the market.
Early Evidence of Customer Demand
For early-stage investors, traction matters the most — but it looks different at every stage. At pre-seed, traction is about validating the idea, not scaling it. This is a crucial nuance. At pre-seed, evidence can be qualitative — customer interviews, letters of intent, a waiting list, an early pilot. At seed, investors want quantitative signals: retention curves, early revenue, or pilot results. At Series A, they need a model they can project forward. Founders who present the wrong kind of evidence for their stage signal that they don’t understand what investors are actually evaluating.
Revenue helps, but investor-grade traction can also mean repeat usage, paid pilots, successful deployments, regulatory progress, or proof that a painful workflow is being adopted. The key is credible de-risking, not vanity metrics.
The Founder’s Ability to Sell
Early-stage investors know that a founder who cannot sell the company’s vision to an investor will struggle to sell it to customers, to future hires, and to the next round of investors. The pitch process is itself an evaluation of a core founder capability. Founders seeking VC in 2026 should focus on demonstrating execution rather than simply presenting ambitious projections. Execution at the early stage looks like customer conversations completed, product shipped, pivots made intelligently, and learnings documented — not a polished five-year model built in Excel.
The Narrative Changes by Stage — So Must the Pitch
One of the most important structural insights for early-stage founders is that the story you tell evolves with your stage — and getting that wrong is nearly as costly as approaching the wrong fund entirely.
At pre-seed, the narrative is almost entirely about the team and the insight. You are asking an investor to believe that you see something others don’t, and that you are the right people to build the solution. The evidence is qualitative, the vision is long, and the relationship with the investor is close — you are about to spend years together building from scratch.
At seed, the narrative shifts toward validation. You have evidence that the problem is real, customers are engaging, and the team can ship. In 2026, success at the seed stage is measured by early signs of product-market fit: real user adoption, consistent growth, and strong customer retention. The pitch now includes the model — not a proven one, but a coherent hypothesis about how the business scales and where the unit economics point.
At Series A, the narrative is about the model working. You are not asking an investor to believe in a vision — you are presenting evidence that the machine runs. Series A capital in 2026 is going not to broad horizontal AI tools, but to deep vertical applications in industries where regulatory complexity and data fragmentation have historically limited software penetration. This specialisation extends beyond AI: across every sector, Series A investors want to see differentiation, defensibility, and a repeatable path to revenue.
Access Is a Function of Timing, Targeting, and Follow-Through
The common advice to founders — “get a warm introduction” — is correct but incomplete. Warm introductions improve conversion rates, but the quality of the introduction matters more than its existence. A lukewarm intro from a tangential connection buys you exactly one more email before the same silence. A targeted, well-researched cold email to a fund whose thesis aligns precisely with your company can outperform it.
Access to early-stage VC also depends on where a fund sits in its cycle. A fund that closed its latest vehicle six months ago is in active deployment mode. A fund approaching the end of its deployment window is increasingly reserving capital for follow-ons into its existing portfolio. This information is not always public, but it can often be inferred by checking when the fund’s last close was announced and how many new portfolio companies they have added in the past year.
Finally, follow-through through a structured pipeline is what separates founders who raise from those who generate a handful of promising meetings that slowly go cold. The fastest fundraises usually come from a tighter target list, stronger investor-fit research, and better execution after first contact. Building and maintaining a tracking process — who has been contacted, what stage each conversation is at, when to follow up — is unglamorous but essential.
How to Build a Stage-Matched Early-Stage VC Target List
The research required to build a genuinely useful target list is significant. For each fund under consideration, you need to verify: the fund’s current vehicle and when it closed, the actual check sizes of their last ten investments, the stage those investments were made at, the sectors they have backed, and which partners within the fund are actively leading deals in your space. This is not a two-hour Crunchbase session. Done properly, it is days of structured research — and it needs to be refreshed, because funds’ mandates and deployment status change.
The payoff is material. Your first institutional investor will shape your company for years, from how you price your product to what happens in the boardroom when growth stalls. A strong stage-matched lead compresses fundraising timelines and sends a signal to every downstream investor. The wrong lead — or worse, a round assembled from mismatched followers because the right leads were never targeted — creates friction that compounds over time.
This is exactly the kind of research-heavy, detail-intensive work that founders consistently say they don’t have the bandwidth to do properly while also running their companies. Building a prioritised, stage-matched early-stage VC target list — cross-referenced by check size, fund cycle, sector thesis, and relevant partner — is precisely the work Rupert handles on a founder’s behalf. Rather than spending weeks on investor databases only to approach mismatched funds, founders working with Rupert get a curated, verified target list built by experienced operators who understand the landscape, alongside managed outreach that keeps every conversation and every relationship firmly in the founder’s hands.
Where Things Stand
The early-stage VC market is in an active phase heading into the second half of 2026. The early-stage surge anticipated at the start of the year has arrived ahead of schedule, driven by AI’s compression of company-building costs and the continued deepening of megafund participation at seed and Series A — with first financings on track to exceed 7,000 by year-end, a new record by more than 1,300 deals. At the same time, capital concentration remains a structural feature of the market: 401 Series A and early-stage deals collectively raised $4.45B in July 2026, but the median deal size of $6.0M tells a very different story than the average of $39.5M — the majority of funded companies are early and mid-stage, operating at conventional venture scales, while a small number of platforms are capturing an outsized share of available capital. For founders navigating this environment, the practical implication is that the early-stage market remains genuinely open and active, but the bifurcation between well-targeted founders with stage-matched investor lists and those pursuing undifferentiated outreach is widening rather than narrowing.
See Related below for more on this topic.
See Sources below for the references behind this article.