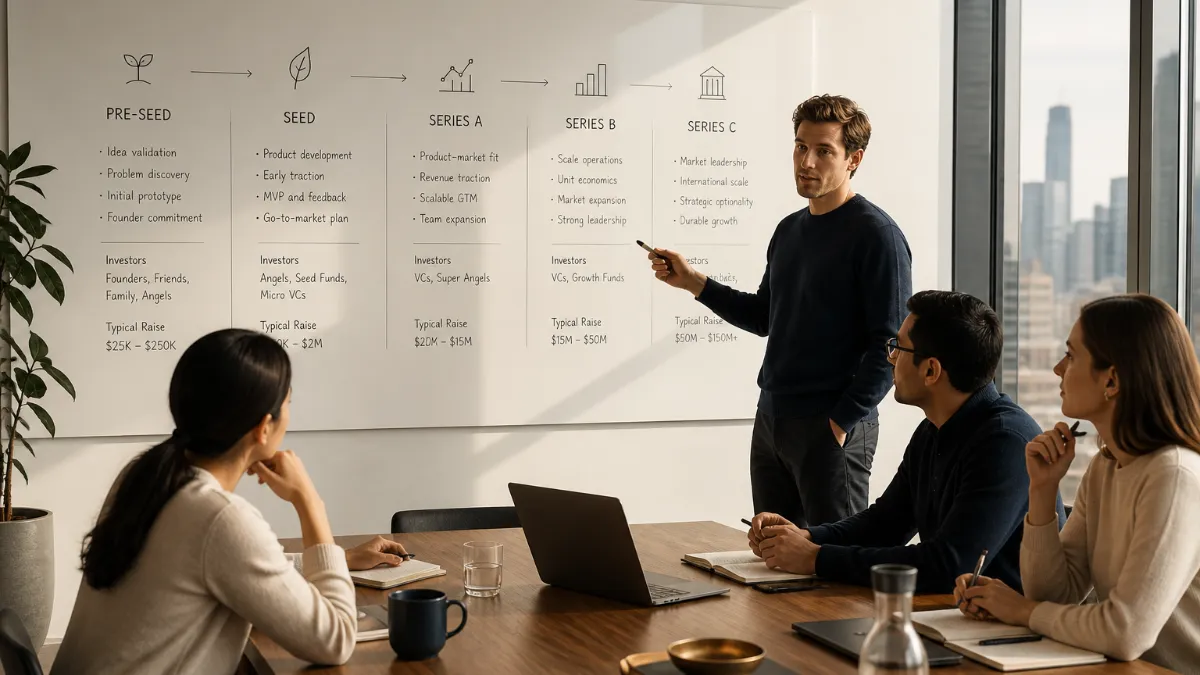
What Startup Funding Stages Actually Are — and Why They Matter
Startup funding does not arrive as one continuous stream. It moves in discrete rounds — each named, each sized, and each tied to a specific level of company maturity. That structure is not arbitrary. Startup funding stages are discrete rounds of investment that correspond to specific moments in a company’s growth, and they exist because investor risk tolerance changes as a startup matures.
At the earliest stage, there is almost nothing to evaluate except the founder and the idea. By Series C, investors are underwriting a proven business with millions in revenue and a clear path to dominance.
Understanding which stage you are actually in — not where you wish you were — is the most important strategic decision you will make before opening a raise. The stage names matter because investors are stage-specialised. Pitching a Series B fund with a pre-seed deck wastes everyone’s time. Match the stage first, then the sector. Misreading your own stage leads to targeting the wrong investors, telling the wrong story, and spending months building a pipeline that was never going to convert.
This guide moves through each stage in turn — what it is, who invests, how much capital is typically involved, what you must prove, and what dilution to expect. The benchmarks reflect where the market actually sits in 2025–2026, not where it sat in the easy-money years.
Pre-Seed: Betting on the Founder
What It Is
Pre-seed is the first outside money your company receives. At this point, a startup is often little more than an idea, a problem hypothesis, or an early prototype. At this point, a startup is often little more than an idea, a prototype, or an early MVP, and the founding team is usually just one to three people, with zero revenue. The pre-seed round exists to convert that early stage into something testable — an MVP that allows you to generate the initial signals seed investors will later require.
Who Invests
Pre-seed is typically $250K to $1M raised on a SAFE with a $3M to $8M valuation cap. The investors are angels, tiny pre-seed funds, and accelerators like Y Combinator with its $500K standard deal. Friends, family, and former colleagues also contribute meaningfully at this stage. Institutional venture firms rarely write pre-seed checks; the round is simply too small and too early for their fund economics.
2025–2026 Benchmarks
Typical pre-seed in 2026 is $250K–$1.5M at a $3M–$8M post-money valuation, with the median around $1M. Geography matters: top-tier markets like NYC and San Francisco skew higher, with some pre-seeds closing at $2–3M on $8–10M caps for strong repeat founders.
Most pre-seed and many seed rounds in 2026 close on SAFEs — simple agreements for future equity — not priced equity. Series A is usually the first priced round.
What You Must Prove
Founder-market fit is the single biggest factor at this stage — why are you the person who wins this market? Beyond that, investors want to see a working prototype and early signal that a real problem exists. In 2026, with AI tooling now widely available, “we have not built anything yet” reads as a red flag. Shipping is cheap now, so ship. Pre-seed investors are making a bet on the team’s ability to learn and iterate quickly; everything else is context.
Dilution
Pre-seed typically results in 10–15% dilution. With SAFE caps at $10–15M and rounds of $250K–$2M, founders give up approximately that range.
Seed: Proving the Product Has a Market
What It Is
The seed round is where the hypothesis becomes evidence. You have an MVP in users’ hands, early revenue or strong engagement data, and enough signal to argue — credibly — that a real market exists for what you’re building. The seed round funds the work of confirming and expanding that signal.
Who Invests
Seed-stage VCs with $10M to $100M funds lead most rounds, while angel syndicates, micro-VCs, and family offices fill out syndicates. A typical lead check runs $500K to $2M, surrounded by three to five co-investors.
2025–2026 Benchmarks
Seed round sizes have moved up sharply in recent cycles, even as deal count has declined. Median seed round size reached approximately $4 million in Q4 2025, up from $2.5 to $3.5 million in 2024, while deal count at seed fell 29% year-over-year — but median valuations rose 19%.
In Q4 2025, the median seed post-money valuation reached $24 million, up from $18 million in Q4 2024. The upward pressure on valuations does not mean the market has loosened; it means the deals that do close are landing at higher prices. According to Carta’s 2025 pre-seed review, U.S. startups raised $10.4 billion across 50,316 SAFEs and convertible notes in 2025 — a 13% decline in instrument count despite flat total dollars. Fewer deals are getting done, but the deals that close are larger. For founders, this means the bar at each stage has risen.
What You Must Prove
In 2026, seed investors demand more than promising ideas. They are looking for early revenue signals — many expect $300K–$500K in ARR — a functional MVP with real user feedback, customer validation from early adopters demonstrating genuine demand, and evidence of efficient unit economics. The median seed round is now $4M on Carta — investors writing checks that size need more than a prototype.
Dilution
Expect to give up 15–20% at seed. That dilution, combined with pre-seed, means founders typically enter the Series A process with roughly 65–75% of their company.
Series A: Funding a Repeatable Engine
What It Is
Series A represents the first major growth round after seed funding. At this stage, companies have validated their product and initial business model and now need capital to scale operations, expand their team, and prove they can grow efficiently. Series A capital is often used to formalise a go-to-market engine, expand engineering and operations, and build the infrastructure required for larger customers.
The critical distinction from seed is this: seed proves your product solves a problem; Series A proves you can build a machine that acquires and retains customers repeatedly and at scale. Investors are no longer evaluating whether your solution works — they are underwriting the scalability of the entire business model.
Who Invests
Institutional VCs with $50M to $500M in assets under management lead most Series A deals. One lead investor takes a board seat with a $5M to $12M lead check. These are typically dedicated early-stage VC firms with enough conviction to take an active governance role. Seed investors may follow on, but they are rarely leading at this stage.
2025–2026 Benchmarks
Carta’s Q4 2025 data put the median seed post-money at a record $24M, and the Q1 2026 PitchBook-NVCA Venture Monitor put the median Series A deal at $19.6M with a $78.7M post-money for the broader market — a 37% year-over-year jump. For non-AI companies, the picture is somewhat more moderate: a typical Series A valuation in 2026 ranges from $25M to $100M pre-money, depending on the sector, traction, and market conditions, with SaaS companies at $1–3M ARR typically seeing valuations of $30–60M.
What You Must Prove
Series A investors need to see clear evidence of product-market fit. In 2026, the bar has risen compared to the 2020–2021 era. Top VCs typically expect revenue of $1M–$3M ARR for SaaS companies, or equivalent traction metrics for consumer or marketplace businesses; year-over-year revenue growth of 2–3x, or 15–20% month-over-month growth; positive gross margins of 60% or more for SaaS, a reasonable CAC payback period under 18 months, and strong net revenue retention of 110% or better; and a team of 10–30 employees with key hires in engineering, product, and go-to-market roles. The minimum ARR for a competitive Series A pitch in 2026 is $1.5M, with top-performing companies showing $3M or more.
Dilution
Dilution at Series A is typically 18 to 22 percent. A founder who has managed pre-seed and seed dilution carefully can still enter Series A with 50–60% ownership.
The Series A Crunch: Why the Gap Between Seed and A Is the Hardest Crossing
No section on startup funding stages would be honest without confronting the statistics that sit between the seed and Series A rows of the table. The Series A crunch is not a myth or a historical artefact — it is a structural feature of the market that every seed-funded founder is navigating right now.
Historically, 20–30% of seed-funded companies have successfully made the leap to Series A, with top VC funds boasting rates as high as 50–75%. Recent cohort data tells a more sobering story. Of companies that raised a $1 million-plus seed round in 2023, only 24% have progressed further, according to a May 2026 Crunchbase report, with rates falling sharply since 2021. For the 2024 cohort, the figure is 16%.
Fewer Series A dollars are available relative to seed companies hunting for capital, with seed deals currently outpacing Series A deals by a 3:1 ratio. The structural implication is clear: raising a seed round is increasingly a prerequisite for a harder race, not a confirmation that the next round will follow. While companies that are funded at the seed stage are typically raising larger checks, they are also taking longer to move on to Series A and face lower odds of graduating to that phase at all. Since 2023, U.S. startups have been taking longer to raise a Series A round following an initial seed round of $1 million and over, with that time frame now stretching to more than two years.
Timeline to Series A: plan 24 to 30 months of operating runway, not 18. Founders who design their seed rounds around an 18-month runway and then miss their ARR targets by month 22 find themselves in a bridge-round or closure conversation that could have been avoided with more conservative planning from the start.
The crunch makes investor targeting and milestone discipline at the seed stage critical, not optional. Knowing which Series A funds invest in your sector, at your stage, at your traction level — and reaching them at the right moment — is what separates the roughly one-in-six seed companies that graduate from the five-in-six that do not.
Series B: Scaling a Proven Engine
By Series B, the question has fundamentally shifted. You are no longer proving the model — you are proving you can scale it. The 2025 Series B market demonstrated a clear shift toward quality over quantity. Fewer startups reached this stage, but those that did came with stronger financials, established customer bases, and clear profitability paths.
2025–2026 Benchmarks
Median Series B is a $40M deal on a $120M–$160M or higher post-money. Investors expect $5M to $10M ARR, 80 to 120 percent year-over-year growth, Rule-of-40 economics approaching the threshold, and a 20-plus person team with proven operations and finance leadership, alongside multi-channel traction and a clear path to market leadership in the initial segment.
The investor profile evolves at Series B. Growth equity funds and multi-stage firms with larger funds begin to appear alongside the early-stage VCs who led the Series A. Governance expectations deepen: you will face requests for audited financials, formal board committees, and institutional-grade reporting.
Dilution
Dilution at Series B is typically 20 to 25 percent. Founders who have been disciplined about dilution through the earlier stages are better positioned to hold meaningful ownership here.
Series C and Beyond: Category Leadership
Series C funding is raised by companies that have already proven the engine works and are now competing for category leadership — expanding into new markets, making strategic acquisitions, or preparing for a liquidity event.
2025–2026 Benchmarks
Among Series C companies between May 2025 and May 2026, the average fundraising amount was approximately $81.7 million, up from roughly $69 million during the full 2025 calendar year. The median tells a more conservative story: the median fundraising amount during the period ending in 2026 was $44.1 million, which is likely a more realistic indication of what most companies can expect. Valuation at this stage is substantial: the PitchBook Q1 2026 cross-sector median Series C pre-money valuation is $203 million, with AI-native companies reaching $270.8 million versus $174 million for non-AI, a 55% AI premium at this stage.
What You Must Prove
Investors no longer evaluate whether the business works — that is settled. The question is how large it can become and what the path to public-markets readiness looks like. Series C is typically the last round before either an IPO, an acquisition, or a transition into private equity ownership.
You need $15M or more in ARR and 100% or better net dollar retention to get meetings with leading growth funds. Series C investors expect you to have product-market fit and a clear path to $100M ARR. They are not funding experiments — they want to see a repeatable sales motion, predictable growth, and unit economics that work at scale.
Dilution
Typical dilution at Series C runs 7–12%, with founders increasingly able to hold the lower end as competition for late-stage quality assets intensifies.
How to Read the Stage Map: Knowing Where You Actually Are
One of the most common and costly mistakes founders make is raising for the stage they wish they were in, rather than the one they are actually in. Describing a pre-product idea as a seed raise, or approaching Series A funds with seed-stage metrics, does not accelerate your timeline — it damages your reputation with the investors you will eventually need.
For founders, the bar at each stage has risen. Pre-seed investors now frequently require early revenue. Seed investors want demonstrable product-market fit. The minimum ARR for a competitive Series A pitch in 2026 is $1.5M, with top-performing companies showing $3M or more. Calibrating your position against current benchmarks — rather than benchmarks from the ZIRP era — is the starting point for every raise.
A useful frame: work backwards from the round you are trying to raise. Identify what the median investor in that round expects to see, then determine honestly whether you are there, nearly there, or still building toward it. If you are nearly there, a narrow bridge or extension may be the right move. If you are still building, the better use of your time is hitting milestones rather than opening a process that the market is not yet ready to fund.
The stage table also determines investor targeting. Stage names matter because investors are stage-specialised. Every week you spend pitching investors who are structurally unable to fund your round — because their fund size, investment thesis, or ownership targets don’t match your stage — is a week you are not building and not talking to the right people.
The Practical Challenge: Finding the Right Investors for Your Specific Stage
Once a founder understands their stage clearly, the next problem is almost always the same: finding and reaching the investors who are actually right for that round, right now. This sounds straightforward — it is not. The investor universe is large, stage-labelling is inconsistent, and the difference between an investor who will take a meeting and one who will write a check often comes down to sector focus, portfolio construction, current fund cycle, and a dozen other variables that are not visible on a firm’s website.
According to research by Techstars, it typically takes 100 to 200 investor conversations to close a solid pre-seed or seed round. Most of those conversations can be de-risked by doing the research upfront — understanding which investors have recently written checks at your stage, in your sector, and at your traction level. The founders who compress their fundraising timelines are almost always the ones who start with a tight, well-researched target list rather than a mass-market approach.
This is the work Rupert was built to do. Rather than handing founders a database and leaving them to build outreach infrastructure from scratch, Rupert’s experienced operators research the investor universe on a founder’s behalf — identifying which funds are actively deploying at the right stage, mapping portfolio overlaps and competitive conflicts, and building personalised outreach for each contact. Every conversation that results is one the founder can have with full context already in place, rather than cold-starting from a generic email.
The appeal for founders who are focused on hitting their milestones is straightforward: the research, personalisation, and pipeline management that drives a disciplined fundraising process gets handled by people who have run these processes before, while the founder retains complete visibility into every outreach sent and every investor relationship built. Nothing is a black box. Every contact, every reply, and every resulting conversation belongs to the founder — not the service.
For a company navigating the narrow passage from seed to Series A, or preparing to open a first seed process, that combination of expertise and transparency can be the difference between a raise that closes and one that quietly stalls.
Where Things Stand
The global venture market entered 2026 in an unusual position: headline numbers are at record highs, but the underlying picture for most founders is more nuanced. Global seed funding totalled $12 billion in Q2 2026, with $5 billion going to seed rounds of $10 million and under, according to Crunchbase data.
The US picture from PitchBook-NVCA shows $412.7 billion deployed in H1 2026, a figure that already exceeded the full-year 2025 total — but 87.5% of that H1 2026 capital went to megadeals of at least $100 million, meaning the headline total says almost nothing about a $3 million seed round. At the early-stage level, the pre-seed market shows signs of stabilising: about 3,000 US-based startups had raised more than $2.3 billion at pre-seed in Q1 2026, a total Carta expected to reach roughly $2.9 billion as more data was entered, and Carta characterised the pre-seed market as stabilising. Meanwhile, the Q1 2026 PitchBook-NVCA Venture Monitor recorded a 37% year-over-year jump in the median Series A deal size to $19.6M , reflecting continued concentration of capital in fewer, higher-quality companies. For the majority of founders raising outside of AI infrastructure or deep tech, the structural dynamics remain constant: fewer deals, higher bars, and longer timelines between rounds than the market data headlines suggest.
See Related below for more on this topic.
Sources: The 8 Stages of Startup Funding · Startup Funding Stages Explained (Bootstrapping to Series C) · Startup Funding Stages: From Pre-Seed to Series A.