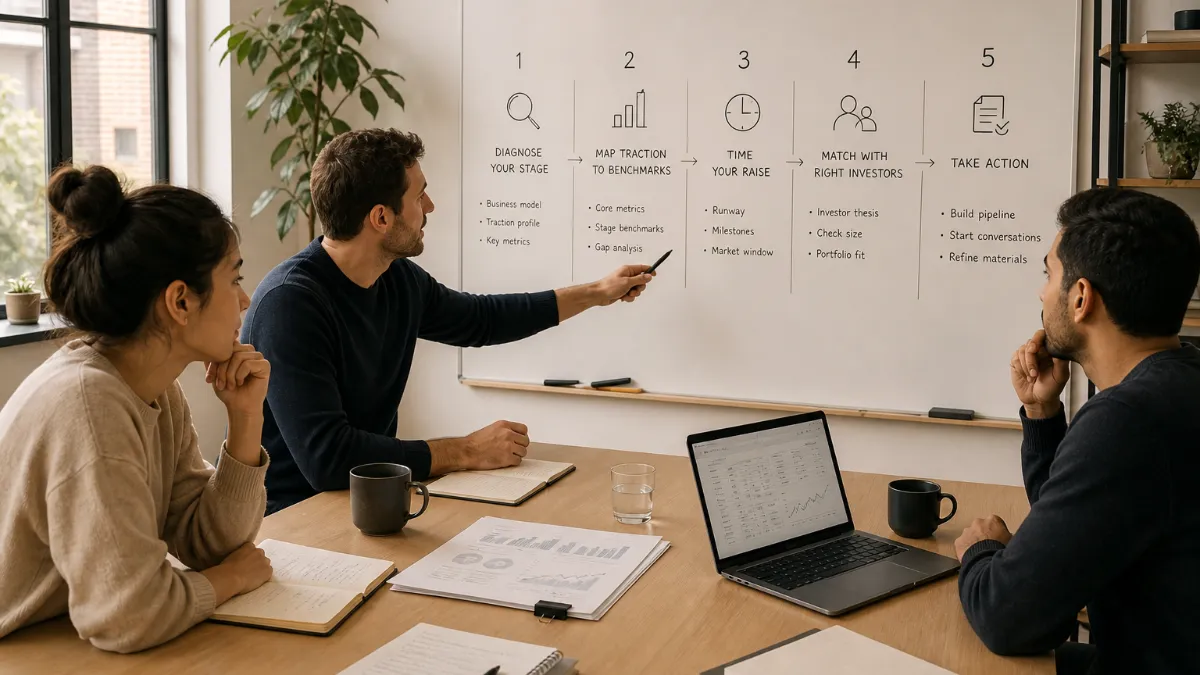
The Question Before the Pitch
Most founders approach fundraising as a sales problem: build a compelling deck, get into meetings, and close investors. But the more consequential question comes before any of that — and it is a diagnostic one. Which stage are you actually at? Which round should you be raising? And are you genuinely ready for it, or are you optimistically early?
Getting this wrong is expensive in ways that compound. Raising too early dilutes your cap table before you have leverage, attracts the wrong investor profile, and strains relationships when milestones get missed. Raising too late bleeds runway and forces you into a desperate process where investors sense the pressure before you say a word. The four-step framework below will help you answer these questions with honesty, structure, and the kind of precision that actually moves investors.
Step One: Map Your Traction to Stage Benchmarks
The first thing to understand is what each stage is for. Pre-seed funds a thesis. Seed funds the search for product-market fit. Series A funds the scaling of a proven model. Those are not marketing definitions — they are investor risk frameworks, and the capital that flows at each stage is calibrated accordingly.
The audit starts with a single, uncomfortable question: what is still unproven about your business? If the answer is “whether customers will pay for this at all,” you are pre-seed. If the answer is “whether we can acquire customers repeatedly and efficiently,” you are seed. If the answer is “whether we can turn a working GTM motion into a scalable one,” you are approaching Series A territory. What you have already proven tells investors where to price your risk. What remains unproven tells them which investor type should be sitting across the table.
According to Carta’s 2025 pre-seed review, U.S. startups raised $10.4 billion across 50,316 SAFEs and convertible notes in 2025, a 13% decline in instrument count despite flat total dollars — fewer deals are getting done, but the deals that close are larger, meaning the bar at each stage has risen.
Pre-seed investors now frequently require early revenue, seed investors want demonstrable product-market fit, and the minimum ARR for a competitive Series A pitch in 2026 is $1.5M, with top-performing companies showing $3M or more.
The honest audit, then, is this: list every milestone you have already hit — MVP shipped, first paying customers, MoM growth rate, net revenue retention, burn multiple — then compare it directly to the benchmarks for the round you think you want to raise. If there is a meaningful gap between where you are and where those benchmarks sit, that gap has a name and a timeline. That is your milestone gap, and it drives the next step.
Step Two: Identify the Milestone Gap and Name It
Once you have mapped your current traction to stage benchmarks, you need to be clinical about what still needs to be true before a round is fundable. This is where founders most often mislead themselves, because they conflate “interesting to investors” with “ready for a check.” The two are very different things.
At seed, investors back your vision with minimal proof. At Series A, investors evaluate actual metrics and growth trajectories — the distinction changes what you need to demonstrate: evidence that your model works and can scale, not potential alone. For B2B SaaS, that evidence has a specific shape. Most institutional VCs expect $1M–$3M in annual recurring revenue with 15–20% month-over-month growth sustained for at least six months.
Revenue growth rate matters more than absolute numbers — a startup growing 15–20% month-over-month with $500K ARR often attracts more interest than a company doing $2M ARR with 5% monthly growth, because investors bet on trajectories, not snapshots. Beyond ARR, in 2026, investors filter Series A candidates on burn multiple before they get to growth rate, and a burn multiple above 2x eliminates most candidates before the second meeting. Top-quartile Series A candidates carry burn multiples below 1.8x, with the median company that successfully closes a Series A sitting closer to 1.6x.
Name your gap precisely. “We need to get from $800K ARR to $1.5M ARR” is a fundable goal. “We need more traction” is not. The more specific and measurable the gap, the more honestly you can build the plan to close it — and the more credibly you can explain it to investors when the time comes.
Step Three: Build a 12–18 Month Plan to Close the Gap
A milestone gap requires a plan to close it, and that plan needs to be tied to a fundraising calendar, not just a product roadmap. The reason is simple: fundraising has its own timeline that runs in parallel with, and completely separately from, your operating timeline.
Startup fundraising rounds typically take 3–6 months from first outreach to close for seed and Series A rounds, with due diligence periods having extended to 6–10 weeks for institutional rounds in the current environment. That means if you want to close a round in Q1, the process needs to begin in the prior summer. It also means the preparation — the investor list, the materials, the warm relationship-building — needs to begin before that.
Start your next fundraise when you have 6–9 months of runway remaining. That is not conservative advice; it is arithmetic. If your runway is shorter than the time it takes to close a round, you are already negotiating from weakness. Investors can smell desperation in the calendar math even before they see it in your tone.
Many investors emphasize the importance of starting the preparation for raising Series A well before you run out of cash, with experienced advisors suggesting founders focus on their critical metrics 12 to 18 months before seeking Series A investment.
The median time from seed to Series A in 2025 was over 24 months — and that is not a failure timeline; it is the actual process. Plan for it deliberately rather than discovering it under pressure.
The 12–18 month plan should specify: the exact revenue and retention targets you need to hit, the quarter in which you will begin soft investor conversations, the quarter in which you will formally open the round, and the runway threshold below which you will not launch a process no matter what. Treat that last line as a hard stop.
Step Four: Match Your Stage to the Right Investor Profile
The fourth step is often skipped entirely, and it is the one that causes the most wasted time. Sending your Series A-sized pitch to a pre-seed angel, or pitching a seed deck to a growth-stage VC, does not just result in a no — it results in a conversation that poisons your name in that investor’s network.
Every stage attracts a distinct investor type with distinct portfolio needs, check size ranges, governance expectations, and time horizons. The structural differences between seed and Series A are significant — seed rounds are often raised on SAFEs or convertible notes with minimal governance requirements, while Series A is a priced equity round using full NVCA model documents that introduces a lead investor who takes a board seat and active governance role, liquidation preferences, anti-dilution protections, and information rights. Pitching an investor whose model requires a board seat to a company that is not ready for that level of governance is a mismatch that hurts both parties.
Series A rounds typically raise $10M–$25M (median around $15M) at $40M–$120M post-money valuations, used to scale a validated product-market fit into a repeatable go-to-market motion that typically requires $1M–$3M ARR for SaaS — with typical dilution of 18–25% and a time to close of 3–5 months.
The practical output of stage-matching is a tiered investor list: a primary list of 30–50 investors who are specifically mandated to invest at your stage, in your sector, at your check size, followed by a secondary list of 20–30 who are adjacent but worth testing. Building this list is not a shortcut exercise — it requires reading each investor’s recent portfolio, thesis, and check size carefully. The right investor for your stage is one where your round is consistent with what they have already done, not one who is intrigued by your story but structurally wrong for your company.
Why Raising Too Early Is More Expensive Than Founders Think
The most consistent pattern among founders who struggle to close rounds is not a weak product or a bad market. It is a timing problem: they started the process 6–9 months too early and spent their credibility before their metrics had the chance to catch up. As of 2025 cohort data, fewer than 15% of seed-funded startups raised a Series A within two years, down from 30% just six years ago.
Less than 40% of seed-funded startups successfully raise Series A, and timing matters — raising too early with thin metrics will slow the process and weaken your terms. The dilution math is cumulative in ways that founders who model only one round at a time consistently underestimate. Each premature attempt results in either a pass, a bridge on unfavorable terms, or a priced round at a discount to what the business would have commanded six months later.
The ARR that would have closed a Series A in 2021 gets a “come back when you’re at $2M” response in 2026 — the stages of startup companies have shifted, and founders who are still playing by 2021 rules will feel the gap. This is not a reason for pessimism; it is a reason for precision. The benchmarks exist because they represent the actual threshold at which investors believe a business has de-risked the model enough to deserve growth capital. Treating them as gates rather than guidelines is not conservatism — it is the fastest path to a clean, well-priced round.
Bridge Rounds and Extensions: Tools, Not Lifelines
No guide to startup funding stages is complete without an honest account of bridge rounds, because the decision of whether to bridge is often where stage diagnosis gets most distorted. In 2026, roughly 38% of seed-funded startups raise a bridge before they ever see a priced Series A term sheet. That normalization is structural, not a symptom of widespread failure. The Series A market in 2025 showed an 18% decline in deal volume year-over-year with total capital invested down 23%, and the average time between seed and Series A has stretched to around 616 days. With gaps that long, a bridge can be the right answer — but only when it is tied to a defined, measurable outcome.
A bridge round strengthens your position when the startup has clear traction and a defined path to the next round; it signals trouble when existing investors sit out and the bridge is used to cover operating losses without improving fundamentals. The signal to future investors is not that you bridged — it is whether the bridge accomplished what it set out to do. Bridge rounds keep the company alive and provide time to hit the higher milestones that Series A investors now demand, but they often come with less favorable terms: shorter maturities, conversion discounts that dilute founders further, and the implicit signal to future investors that the company could not raise a priced round.
The test for a bridge is simple: can you articulate the specific milestone you will hit with this capital, the timeline in which you will hit it, and the investor who has indicated they would fund a priced round once you do? If the answer to any of those three is “not yet,” you are not ready to bridge — you are ready to cut burn and extend runway until the answer becomes yes.
Execution Is Where Rounds Are Won or Lost
Once a founder has completed the four-step process — mapped traction, named the milestone gap, built the timeline, and matched to the right investor profile — the bottleneck shifts from diagnosis to execution. And execution is, by most accounts, where rounds are actually won or lost.
Running a full seed process while managing operations is one reason early-stage companies often underperform operationally during fundraising windows — the process is more time-consuming than most founders expect before they have done it. The investor research alone — identifying who actually invests at your stage and sector, finding warm paths in, personalizing outreach at a level that generates a genuine response — is a part-time job measured in weeks, not days.
This is the gap that Rupert is built to close. Once you know exactly which stage you are raising and exactly which investor profile that stage requires, the next constraint is outreach quality and pipeline discipline. Every campaign Rupert runs is researched and personalized by experienced operators who understand what moves investors at each stage of the funnel. Founders retain complete visibility into every conversation and every relationship — there is no black box, no loss of ownership — but they do not have to choose between executing on their product and executing on their raise. The two processes run in parallel, the way they should, without one cannibalizing the other.
Fundraising is ultimately a sequenced, disciplined process that rewards founders who treat it like one. Know your stage. Know your gap. Know your timeline. And when the time comes to put your investor list to work, make sure the outreach is worthy of the business you have built.
Where Things Stand
As of mid-August 2026, the fundraising environment for seed and Series A founders remains sharply bifurcated. Valuations have moved up meaningfully at the top end of the market: Carta’s Q4 2025 data put the median seed post-money at a record $24M, and the Q1 2026 PitchBook-NVCA Venture Monitor placed the median Series A deal at $19.6M with a $78.7M post-money — a 37% year-over-year jump — though much of that increase is concentrated in AI deals, with non-AI Series A rounds still pricing closer to a $40–42M pre-money.
Meanwhile, the conversion rate from seed to Series A has dropped from roughly 50% historically to around 38%, and investors are underwriting to profitability paths they were largely ignoring a few years ago. Down rounds have pulled back from their 2023 peak — Carta recorded 11.4% of new funding rounds as down rounds in Q1 2026, compared with a 22% peak in 2023 — but bridge rounds accounted for 16.6% of all cash raised on Carta in Q2 2025, reflecting the persistent gap between seed metrics and Series A requirements. For founders not in the AI concentration zone, the practical picture is one of available capital paired with meaningfully higher bars: stage benchmarks are real, investor diligence is longer, and the window between deciding to raise and actually closing continues to run longer than most first-time founders anticipate.
See Related below for more on this topic.
See Sources below for the references behind this article.