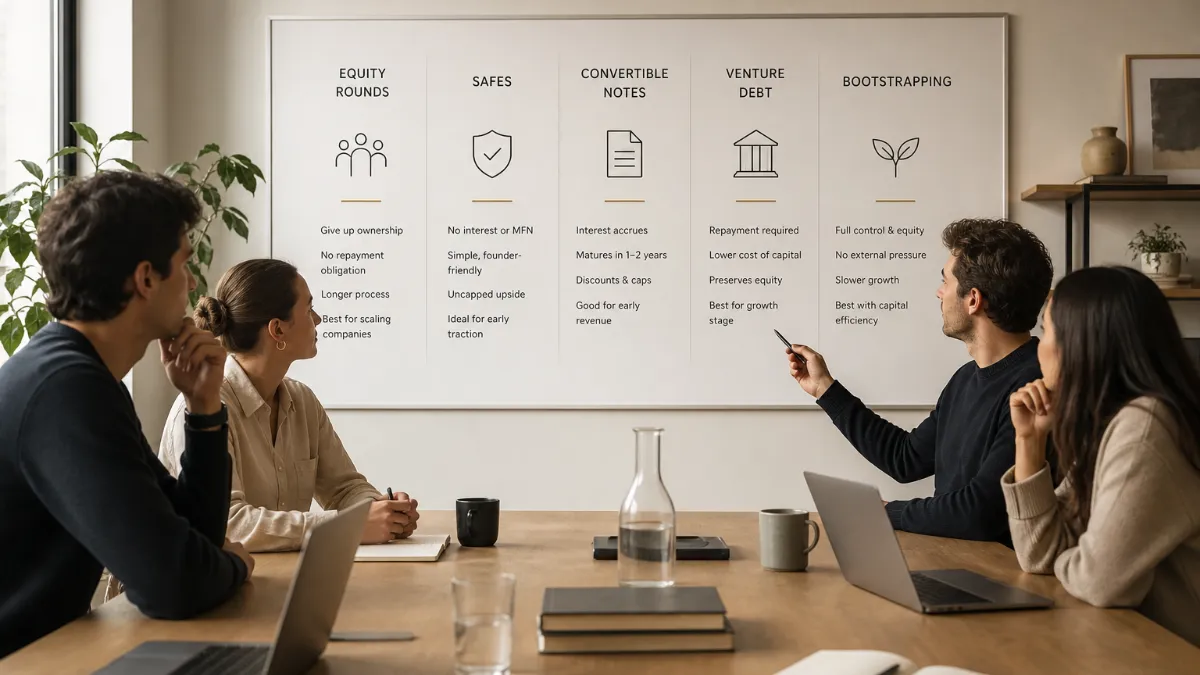
The Real Cost of Each Funding Type Is Not What You Think
Every founder learns the funding menu quickly — equity, SAFEs, convertible notes, venture debt, bootstrapping. What takes longer to understand is that each instrument carries a fundamentally different kind of cost. Equity costs ownership, permanently. SAFEs defer that cost but do not eliminate it. Debt costs cash and introduces repayment risk. Bootstrapping costs speed. None of these costs are inherently bad, but choosing the wrong instrument for your stage can compound in ways that are genuinely hard to undo — dilution that arrives at the worst moment, debt covenants that constrain your next raise, or a cap table that confuses Series A investors before you even get to the first meeting. This article compares the four primary funding types side-by-side, examining when each makes sense, what it actually costs, and how the choice today shapes your options tomorrow.
Priced Equity Rounds: Permanent Dilution With Full Structure
A priced equity round — whether it is labeled a Seed, Series A, or Series B — is the clearest transaction in venture capital. Investors receive preferred shares at a negotiated price per share, which implies a specific pre-money valuation. Everyone on the cap table knows exactly what they own from the moment the round closes.
Founders typically give up 15–25% per round at pre-seed through Series A, narrowing to 5–12% at later stages as the cap table thickens. The cost is permanent: unlike debt, there is no repayment event, and unlike convertible instruments, there is no ambiguity about what the investor owns. That clarity cuts both ways. Investors who lead priced rounds almost always receive preferred stock with protective provisions, board representation at Series A and beyond, and information rights. The governance overhead that comes with a priced round is real.
In 2026, seed investors demand more than promising ideas — many expect $300K–$500K in ARR before they will price a round. The median Series A in 2026 is a $19.6 million deal, with most investors requiring $1–3 million in ARR and strong growth of 150% year-over-year, along with a clear path to $10 million ARR within 18–24 months. Priced rounds make sense once you have enough data to defend a valuation — attempting one too early simply means selling cheap, because investors will price the uncertainty into the number.
Priced equity rounds require more legal work and typically cost $15,000–$25,000 in attorney fees , which is a small figure relative to round size but meaningful context when comparing against the near-zero execution cost of a standard SAFE.
SAFEs and Convertible Notes: Deferred Dilution With Hidden Compounding Risk
The Simple Agreement for Future Equity — SAFE — was introduced by Y Combinator in 2013 precisely to solve the problem priced rounds create at the earliest stages: there is simply not enough data to justify setting a formal valuation, yet the company needs capital now. With a SAFE, investors provide funds upfront in exchange for the right to convert their investment into shares when the company raises its next priced round. Three features separate SAFEs from debt instruments: no interest, no maturity date, and no repayment obligation.
The market has voted decisively for the SAFE structure at early stages. At the pre-seed stage, SAFEs comprised a record high of 93% of all deals on Carta in Q1 2026, while convertible notes fell to a record low of just 7% of pre-seed rounds. The trend is accelerating: a majority of early-stage rounds under $4 million in H1 2025 were SAFEs or convertible notes.
The appeal is straightforward: SAFEs are fast, cheap to execute, and avoid the friction of a formal valuation negotiation. SAFEs are the cheapest deal structure to execute, with legal costs running $0–$2,000 if you use Y Combinator’s free templates. The valuation question gets deferred to the next priced round, where there will presumably be more data to support a higher number.
But the deferral is not free. The risk that founders consistently underestimate is dilution stacking. The most consequential change in SAFE design came with the post-money SAFE in 2018, which shifted the dilution burden entirely onto founders — each new SAFE dilutes only the founder pool, not earlier SAFE holders. This means that issuing three or four SAFEs before a priced round does not spread dilution evenly across all investors. It concentrates the damage on the founding team. Total dilution through Series A typically reaches 40–50% of founder equity , and founders who stack multiple unpriced notes before reaching that point often arrive at the seed or Series A negotiating table already meaningfully diluted.
How Convertible Notes Differ
Convertible notes occupy a middle ground between SAFEs and priced equity. Like SAFEs, they convert to equity at the next priced round. Unlike SAFEs, convertible notes accrue interest — typically 4–8% annually — and carry a maturity date, usually 12–24 months. That maturity date matters: if the company has not raised a priced round by the time the note matures, the noteholder has a legal claim that a SAFE holder does not. The discount rate on convertible notes typically runs 10–25%, rewarding early investors when the note converts to equity. Convertible notes remain useful for bridge financing between priced rounds, where the debt-like structure is actually desirable — it signals urgency to close the next round rather than letting the bridge linger indefinitely.
Venture Debt: Runway Extension Without Dilution — With Strings
Venture debt is structurally different from every other instrument on this list. It is not equity, and it does not pretend to be. You borrow a defined amount, pay interest, and repay the principal — typically over 36–48 months, often with an initial interest-only period. The benefit is that you extend your runway between priced rounds without issuing new shares.
Nearly 60% of venture debt deals now occur at late or growth stage , which signals something important: this is not an early-stage instrument. Venture debt is best used to extend runway 6–12 months between equity rounds without resetting valuation, and it requires recent VC backing — lenders underwrite based on your investors’ credibility, not your cash flow. A founder who has never raised an institutional equity round will find the venture debt market largely closed to them.
For those who do qualify, the economics are meaningful. Total interest rates for venture debt generally range from 8–15% annually in 2024–2025, and can climb above 20% for higher-risk startups. Lenders also typically receive warrant coverage — a small equity stake — in exchange for taking on startup risk, so the instrument is not entirely non-dilutive, but the dilution is minimal compared to issuing a new equity round. In most cases, lenders size loans based on a combination of revenue scale, growth trajectory, and the startup’s most recent equity financing round — for example, a SaaS company with $8 million ARR and strong growth may be able to raise $4 million in venture debt, depending on investor backing and burn profile.
The risk is structural, not just financial. Venture debt can increase company risk if it defaults on covenants, forcing an immediate, desperate, and often low-valuation equity raise to repay the debt. Venture debt taken against a weak business is not a bridge — it is an anchor. Used correctly, in the 12–18 months after a strong equity round when growth trajectory is clear, it buys real runway without the dilutive cost of pricing a new round early.
Bootstrapping: Underrated, Misunderstood, and Strategically Powerful
Bootstrapping is often framed as the path for founders who cannot raise money. That framing is wrong. It is more accurate to describe bootstrapping as the path that maximizes optionality — at the cost of speed.
Bootstrapping preserves ownership, keeps control concentrated with the founding team, and enforces capital discipline. It typically results in slower hiring, incremental experimentation, and a sharper focus on revenue quality and cash flow. Those constraints, properly understood, are features rather than bugs. A founder who has built $500K in ARR without external capital has demonstrated product-market fit, customer willingness to pay, and operational discipline — three things that investors prize and that are extremely difficult to fake.
Bootstrapping demonstrates resourcefulness, capital efficiency, and product-market validation, since the company survived without external cash. Investors view a bootstrapped founder as a lower-risk investment because they have proven they can build and sell with minimal resources. This investor perception is a genuine and underappreciated advantage. A founder arriving at a seed raise with real revenue and full ownership is in a structurally stronger negotiating position than one who has burned through multiple SAFEs and has no revenue.
The trade-off is speed and scale. Bootstrapping can be challenging due to limited financial resources, slower growth compared to funded startups, and the pressure of bearing financial and operational risks solely as a founder. In markets where network effects, distribution, or regulatory positioning must be seized before competitors lock them up, bootstrapping is rarely viable. A winner-take-all marketplace, a deeply capital-intensive hardware product, or a regulated financial services platform — these are contexts where external capital is not optional. Bootstrapping is still realistic in 2026, especially for startups with simple operating models, clear customer demand, and products that can start earning revenue early — it is often a better fit for B2B SaaS, agencies, niche software products, and service-backed tech companies than for capital-heavy businesses.
Matching Instrument to Stage: A Practical Framework
The right funding type is not universal — it depends on what your company is, what stage it is at, and how fast your market is moving. A useful way to think about it is to map the instrument to the information available at each stage.
Pre-seed: Almost no data. No valuation defensible. SAFE is the correct instrument for most founders. Keep the cap table simple — one or two SAFEs, not five.
Seed: Early revenue signals available. The median seed round as of Carta’s July 2026 benchmark was $4.1 million raised on a $24.3 million valuation, with 18% median dilution. A priced seed round makes sense once you can defend a number. If you cannot, a larger SAFE or a SAFE bridge is preferable to pricing at a low valuation that you will struggle to step up from at Series A.
Post-seed, pre-Series A: This is the window where venture debt becomes relevant. If you have raised a seed round from credible institutional investors and have 12+ months of predictable revenue, a venture debt facility can extend your runway to the metrics that unlock a Series A, without repricing your equity midway through the journey.
Series A and beyond: Priced equity becomes the norm. SAFEs usually fit pre-seed and seed stages, not the Series A itself — Series A investors want a priced round with preferred stock, governance rights, and board terms that a SAFE does not provide.
For hardware or deep-tech founders, the timeline is longer and the instrument mix is different. Grants and strategic partnerships often precede any equity round, because the capital requirements are too large and the de-risking required is too extensive to attract typical seed capital before significant technical milestones have been achieved.
Choosing the Instrument Is Step One. Finding the Right Investor Is Step Two.
Understanding which instrument fits your stage is necessary, but it does not solve the actual fundraising problem. The same company at the same stage can raise successfully or unsuccessfully depending almost entirely on whether it is talking to the right investors — people who are actively writing the specific instrument you need, at your stage, in your sector, at this moment.
That gap between knowing what to raise and knowing who to raise from is where most founder fundraising time gets lost. Building an investor list from scratch, researching who is active versus who last deployed capital two years ago, personalizing outreach at a level that actually generates responses — these tasks are time-consuming enough to distract from building the business, and getting them wrong is expensive in both time and cap table.
That is the problem Rupert is built to solve. Rather than leaving founders to research the market themselves, Rupert’s team of experienced operators handles investor identification, outreach research, and pipeline management on the founder’s behalf — while making every conversation and every investor relationship fully visible to the founder. If you have done the work of choosing the right instrument and building the right story, the next step is making sure the right people are seeing it. That is where expert-managed outreach, executed with genuine personalization and complete transparency, makes the difference between a raise that closes and one that drags.
Where Things Stand
The funding instrument landscape is actively shifting heading into the second half of 2026. SAFEs reached a record high of 93% of all pre-seed deals on Carta in Q1 2026, while convertible notes fell to a record low of just 7% — a consolidation that shows no sign of reversing. Global seed funding totaled $12 billion in Q2 2026 alone , but capital concentration remains stark: a large share of that total flowed to AI companies and mega-rounds, while non-AI founders face a more selective environment. On the debt side, late-stage venture debt deals hit a decade high in Q1 2026, with the median deal reaching $10.8 million and the average climbing to $68.2 million , driven largely by AI infrastructure needs. Eight of the ten largest transactions in Q2 2026 were debt instruments, and every one funded physical infrastructure — chips, data centers, or energy — suggesting the AI buildout has migrated from the venture equity market to the credit market. For seed-stage founders outside the AI infrastructure wave, the core instrument dynamics remain stable: SAFEs dominate early-stage fundraising, priced seed rounds are setting valuation records, and venture debt remains a post-institutional-backing tool rather than an early-stage alternative.
See Related below for more on this topic.
See Sources below for the references behind this article.