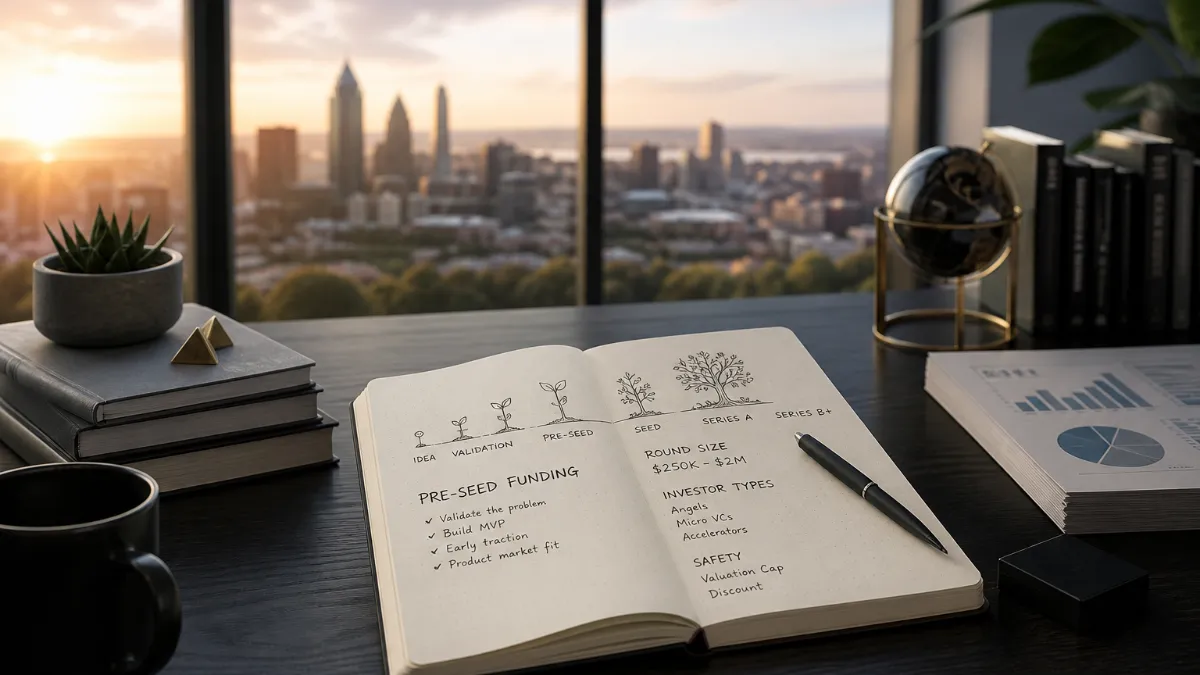
What Pre-Seed Funding Actually Is — and What It Isn’t
Pre-seed funding is the first formal capital a startup raises from outside investors. It is not a friends-and-family check, not a bank loan, and not a government grant. It is equity financing — specifically, the stage at which an idea has enough shape to attract people who invest for a living, even before the company has revenue, a full team, or a proven product. It is the first of the startup funding stages, and it sets up everything that follows.
The canonical pre-seed round exists to fund three things: validating the core idea, building a minimum viable product, and hiring the first one to three people who aren’t the founders. Everything else — scaling, go-to-market, building sales infrastructure — comes later, and trying to fund those activities from a pre-seed round almost always means raising too little money at terms that will haunt later rounds.
That framing matters because the word “pre-seed” has become slippery. Pre-seed in 2026 is not what a 2021 fundraising playbook describes. The median check is up, lead time to term sheet is shorter, and a handful of verticals are eating the majority of all deals. Many founders arrive at their first raise with an outdated mental model of what pre-seed looks like — how much to ask for, who to ask, and what those investors actually need to see. Getting that model right before you start is the difference between a coherent process and a frustrating one.
The 2026 Pre-Seed Market: What the Numbers Actually Show
The data that matters most for founders raising right now comes directly from cap-table and instrument-level reporting. In Q2 2026, the average pre-seed instrument size reached $276,000 — a 27% year-over-year increase from Q2 2025 and a record high over the past four-plus years. That figure understates actual round sizes, because pre-seed rounds above $1M in H1 2026 numbered roughly 2,990, and rounds under $1M numbered about 5,060 — meaning a substantial share of founders are assembling multiple instruments to reach their target.
The median pre-seed check has climbed to roughly $1.1M, up from $750K in 2023. The shift is driven by two forces: pre-seed funds raising larger vehicles — with median fund size moving from $40M to $62M — and the continuing blur between what used to be called pre-seed and what used to be called seed. Most rounds now classified as pre-seed look like 2019-era seed rounds. Founders who benchmark their raise against a five-year-old playbook will undershoot on target size and overcalibrate on what they think investors need to see.
The instrument itself has also standardized sharply. Unpriced instruments have become the default for a company’s first fundraise, with SAFEs now used in the large majority of pre-seed rounds on Carta. The practical effect is that nearly all pre-seed conversations are structured around a valuation cap rather than a negotiated share price — which simplifies closing but introduces its own complexity around dilution math, as discussed below.
Who Invests at Pre-Seed — and What Each Type Brings
Understanding your investor options isn’t just useful for building a target list; it shapes how you structure the round, what terms you accept, and what support you can realistically expect after the money clears.
Angel Investors
Angel investors write checks in the $25,000 to $250,000 range. Most angels at the smaller end of that range participate as part of a syndicate, organized through platforms or through regional networks. Angels are often the fastest-moving capital at pre-seed — a single founder-to-angel relationship can close in days — but their checks rarely anchor a round on their own. They are most valuable as complementary capital that fills out a round once a lead has set the terms.
Micro-VCs and Pre-Seed Specialist Funds
Micro-VCs are institutional funds, usually under $100M in assets under management, that specialize in early-stage deals. They write checks from $250,000 to $2M and typically want to lead the round, set SAFE terms, and take a board observer seat. This is the investor type that has professionalized most rapidly at the pre-seed stage. Pre-seed specialist funds move faster than traditional institutional VCs and make decisions based primarily on founder signal rather than traction benchmarks — but they also have portfolio construction logic that shapes who they back and when.
Accelerators
Accelerators occupy a distinct position. Programs like Y Combinator and Techstars invest relatively small checks — accelerators write checks from $125,000 to $500,000 — but the value compounds through the network, the cohort, the demo day exposure to later-stage investors, and the credentialing effect that survives the program itself. Accelerator acceptance is worth treating as a fundraising strategy in its own right, not just a source of small checks.
What Pre-Seed Investors Prioritize Beyond Traction
Because most pre-seed companies have limited or no revenue, investors at this stage are making a bet on people and insight rather than metrics. The questions being answered are: Does this team have the background and judgment to identify a real problem? Do they understand the market deeply enough to build something people will pay for? Is there evidence — even qualitative — that the hypothesis is directionally right?
Pre-seed vs. seed in 2026 comes down to team signal versus traction signal. That distinction has real implications for how founders should present themselves. A seed investor needs to see the proof that something is working; a pre-seed investor needs to believe you’re the right people to find out whether it will.
How Much to Raise: The Milestone Math Approach
Round sizing is one of the decisions founders get most wrong, usually in one of two directions: raising too little because they’re worried about dilution, or picking a round number because they heard it at a conference.
The right framework is milestone math. The goal of pre-seed capital is to reach the specific proof point that makes you fundable at seed — typically some combination of a working MVP, early user data, and enough signal to anchor a seed thesis. Everything flows backward from that milestone: what does your monthly burn need to be to build it, how many months will it realistically take, and what contingency cushion do you need for the inevitable delays? Targeting 12 to 18 months of runway, plus a 15 to 25 percent contingency buffer, is the standard starting point for sizing a pre-seed raise.
The dilution math then follows from the amount and your cap. Carta’s Q2 2026 medians by round size ran $10M for rounds under $250K, $12M from $250K to $499K, and $12.5M from $500K to $999K. Raising $700K at a $12.5M cap means selling 5.6% of the company. Those numbers are more favorable than most founders expect — the persistent myth that pre-seed rounds cost 15 to 20 percent of the company at the SAFE stage reflects outdated mechanics and pre-money SAFE conventions that have mostly given way to post-money structures.
The strategic question is whether your milestone math produces a number that fits the market’s range. The typical pre-seed round in 2026 runs $250K to $2M, with SAFEs as the default instrument, and no revenue requirement as the norm. If your milestone math lands well below $250K, you may be able to reach your proof point through revenue or non-dilutive sources before raising at all. If it lands above $2.5M, you may be raising a seed round whether you call it that or not.
SAFE Mechanics, Cap Tables, and Why This Matters More Than Founders Expect
Most first-time founders treat the SAFE as a formality — a simple agreement that delays the real equity conversation until a later priced round. That framing is dangerous, and understanding why is one of the most important things you can do before signing your first instrument.
The shift from pre-money to post-money SAFEs changed the dilution calculus in a way that catches founders off guard. Under post-money SAFEs, each investor is guaranteed their fixed ownership percentage as if no other SAFEs exist. That guarantee has a cost: every new SAFE issued dilutes only the founders, not existing SAFE holders. This means that stacking multiple SAFEs — a common pattern when founders raise in tranches — compounds dilution faster than any individual instrument suggests.
The problem is almost never any single SAFE; it is the aggregate, including the option pool expansion that typically happens pre-money at the seed round.
The option pool pre-money shuffle is a standard mechanism where Series A and lead seed investors require the option pool to be topped up pre-money, meaning the dilution comes out of existing shareholders — founders and early SAFE holders — rather than being shared with the new investor. The practical effect is that a round that looks like 20% dilution on the headline terms often costs founders 25 to 30 percent in total when the SAFE conversions, option pool refresh, and new-money shares are all calculated together.
The takeaway is not that SAFEs are bad — they remain the right instrument for most pre-seed situations because they are fast, simple, and avoid the governance complexity of priced equity at a stage where the company is still finding its shape. The takeaway is that cap-table hygiene matters from the first dollar. The specific failure mode is stacking SAFEs to raise a little extra at pre-seed without modeling the conversion math before signing. Founders who build a conversion model before signing each instrument — and who negotiate the valuation cap with the downstream seed round in mind — protect their ownership in ways that compound meaningfully by Series A.
Pre-Seed vs. Seed: Understanding the Line You’re Working Toward
Knowing what pre-seed is for also means knowing what it has to deliver. The pre-seed round ends when you’ve reached the proof point that unlocks seed capital. Understanding what seed investors need to see — and working backward from that — keeps your milestone math honest.
The seed round in 2026 typically ranges from $2M to $6M, at a post-money valuation cap of $10M to $20M, with a typical revenue expectation of $0 to $1M ARR and institutional VCs or micro-VCs as lead investors. That gap between pre-seed terms and seed terms is where the proof point lives. The pre-seed investor is betting you’ll cross that gap; the seed investor needs evidence you’re already most of the way there.
That number is a useful reality check, not a reason for pessimism. Most pre-seed companies fail to raise seed not because their product is bad, but because they ran the wrong process — they raised from the wrong investors, built toward the wrong milestone, or burned through capital before reaching the proof point they needed.
The advance-rate figure also underscores something that gets underweighted in most pre-seed conversations: the pre-seed round is not just about surviving to the next milestone. It is about building the proof point that a specific type of seed investor will find credible. That means knowing your target seed investors before you close your pre-seed, understanding what they need to see, and building your pre-seed milestone plan explicitly around that bar.
Building and Running Your Pre-Seed Process
Having the right thesis, the right amount, and the right terms is necessary but not sufficient. The process of actually finding and closing investors is where most pre-seed rounds stall.
The mechanics matter: founders should expect to pitch their deck 30 to 50 times before closing, ultimately reaching 8 to 15 investors who write individual checks of $25K to $250K. That volume requires a structured pipeline — a live list of investors, their status in the conversation, the next action, and the expected check size. Without that structure, it is easy to mistake activity for progress.
The quality of your investor list matters as much as its length. Pre-seed investing is highly relationship-mediated: warm introductions consistently outperform cold outreach, and the relevance of an investor’s portfolio to your category matters more than their fund size. Spending two weeks building a precise list of the right investors — people who have funded comparable companies at the same stage, in the same space, in the past 24 months — produces better outcomes than blasting a generic pitch to hundreds of names from a database.
Research, personalization, and pipeline management are the operational core of fundraising, and they are also the part that takes founders away from building. For founders who understand what pre-seed capital is for — and who are ready to run a disciplined process to raise it — working with experienced operators who handle the investor research, personalize every outreach, and manage the pipeline while founders stay focused on building is one of the most leveraged decisions a pre-seed company can make. Rupert is built for exactly that: every campaign is researched and managed by experienced operators, with full founder visibility into every conversation and every relationship from start to close.
Four Pre-Seed Misconceptions That Trip Up First-Time Founders
“Pre-seed is just bootstrapping with a different name.”
Not at all. Bootstrapping means funding your company with personal savings or early revenue, with no outside investors and no dilution. Pre-seed funding involves external investors who receive future equity in your company in exchange for capital. The two approaches are structurally and philosophically different — and conflating them leads founders to either underestimate the fundraising work ahead or overestimate what outside capital requires.
“I need a formal valuation to raise pre-seed.”
In most cases, you don’t. Because the dominant instrument at pre-seed is the post-money SAFE, you are not agreeing to a formal company valuation — you’re agreeing to a valuation cap, which is different. The cap sets the ceiling for the price at which the SAFE converts; it’s not a statement about what your company is worth today. This is one of the features that makes SAFEs attractive: they defer the valuation negotiation until a priced seed round, when there’s more data to anchor it.
“Pre-seed is only for Silicon Valley companies.”
From Q2 2025 to Q2 2026, some significant differences emerged in the map of the pre-seed market, with certain states, cities, and regions rising up the fundraising ranks and others falling back. California’s lead over the rest of the nation grew even larger, while Texas surpassed New York and the Northeast lost market share. California does attract a disproportionate share of pre-seed dollars, but that’s a concentration story, not an exclusion story. The proliferation of pre-seed micro-VCs with national mandates and the normalization of remote investor relationships have made it genuinely viable for founders in Atlanta, Austin, Miami, or Chicago to raise pre-seed capital without relocating.
“Raising pre-seed means I’m committed to raising a seed round.”
Raising pre-seed funding does not obligate you to raise again. SAFE instruments are designed to convert when a future priced round occurs, but that trigger event only happens if you choose to raise one. Some companies use pre-seed capital to reach profitability and never need another round. What you’re committing to when you sign a SAFE is the possibility of future equity conversion — not a mandate to keep fundraising on a venture timeline.
Close the Round in a Focused Sprint
Pre-seed rounds rarely have a single lead investor who writes the whole check. Deals that exceed $2.5 million typically involve ten or more instruments stacked together. This means closing is itself a process of sequencing — getting the first committed check as an anchor, using that anchor to convert the next, and building to the target through a series of commitments that reinforce each other.
The goal is to treat closing as a focused sprint rather than an open-ended process. Set a clear target close date — usually tied to a natural milestone like “by end of the quarter” or “before we need to make this hire” — and communicate it to investors who are close. SAFE notes simplify the mechanics: SAFEs are used in the large majority of pre-seed rounds , and their relative simplicity means that once an investor verbally commits, getting to a signed document is typically a matter of days, not weeks. The legal infrastructure for a pre-seed close is not complex; the main cause of delay is usually the founder failing to create the conditions that make signing feel urgent.
A realistic timeline for the full process looks like this: three to four weeks of preparation (phases one through three), six to ten weeks of active outreach and meetings (phases four and five), and two to four weeks of diligence and close. Pre-seed startup funding in Q1 2026 matches recent quarters, suggesting a stabilization of the market. In a stable market, founders who run a disciplined, phased process can expect a 12–20 week end-to-end timeline. Those who treat fundraising as a background task alongside product work almost always run longer.
Where Things Stand
Carta’s State of Pre-Seed report for Q2 2026 shows a market that is stable in dollars but more selective in deal count: roughly the same capital as a year earlier went into about 22% fewer instruments, pushing the average pre-seed instrument to a record $276,000. California collected 52% of all pre-seed capital raised on Carta in Q2 2026. The pattern rewards founders who run a targeted, well-researched process.