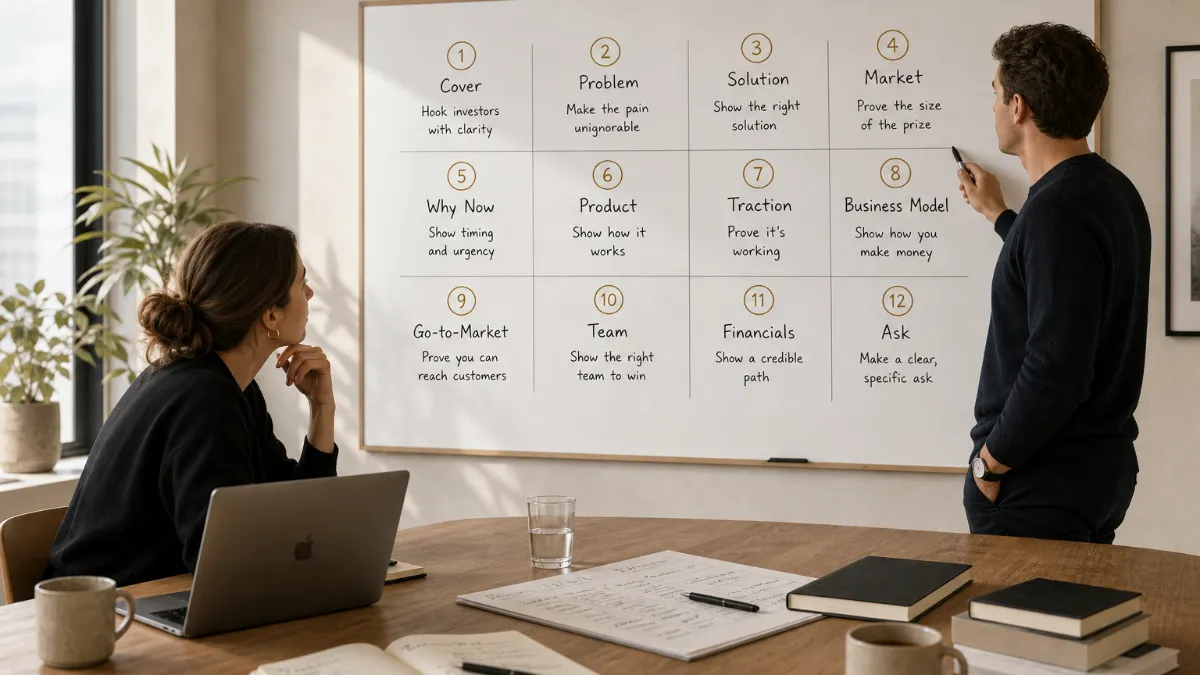
A seed round pitch deck is not a company brochure. It is a sequenced argument — a series of claims, each building on the last, designed to move a skeptical investor from “I’ve never heard of this company” to “I want to take a meeting.” The sequence is not arbitrary. Every slide has a job. And the order in which you make your case determines whether the story lands or quietly falls apart before the fifth slide.
Most investors will see your deck before they meet you, and many will decide whether to take a meeting based on it alone. That means your deck is doing sales work without you in the room. It needs to be structured to answer investor questions in the exact order those questions arise — and those questions always start with the same one: Is this a real problem worth solving?
This guide walks through all 12 slides of a seed round pitch deck, in order, with a clear explanation of what each slide must prove and why that proof matters. Treat each slide as a single argument, not a data dump.
The Narrative Arc That Underlies Every Slide
Before touching any individual slide, understand the architecture. A well-structured seed deck follows a problem-first narrative: open with the pain, establish the market, demonstrate that demand is real, present your solution, explain how you make money, show the team, and close with a specific ask. Deviation from this sequence isn’t creative — it’s confusing.
Investors do not read a deck like a design review. They read it like a fast screening document. They want to understand the business quickly, see whether the opportunity is real, and decide if the company deserves a meeting. That cognitive reality should shape every decision you make about what goes where.
A 10 to 15 slide deck works consistently for seed-stage companies, with 10 to 12 slides being optimal for initial investor meetings. The 12-slide structure below hits that sweet spot: enough depth to earn conviction, tight enough to hold attention.
The 12 Slides, in Order
Slide 1: Cover
The cover slide is not decoration. It is the first five seconds of the investor’s experience. It should carry your company name, a single one-line descriptor of what you do, and nothing else. The descriptor should be specific enough that an investor immediately knows the category and customer — not “AI-powered workflow automation” but “AI that writes and files insurance claims for independent adjusters.” Specificity signals founder clarity. Vagueness signals hand-waving.
Slide 2: Problem
The problem slide is where the deck either pulls investors in or loses them. Its job is to make investors feel the pain — not acknowledge it abstractly, but viscerally understand why a particular group of people is suffering right now without your solution.
The most common failure here is describing a problem that is technically real but emotionally inert: “The market for X is inefficient.” That is not a problem; that is an observation. A strong problem slide names a specific person, describes what their day looks like today without your solution, and quantifies the cost — in time, money, or lost opportunity — of that pain. If investors have worked in or around your industry, this slide should make them nod. If they haven’t, it should give them enough context to imagine the pain clearly.
Slide 3: Market Size
Demonstrating market potential is critical for securing seed funding. Highlight the size of your target market, growth trends, and any gaps your business can fill. This information reassures investors that your startup has room to thrive and scale.
The market slide has one job: make the opportunity feel worth a fund-returning bet. Venture investors need to believe that if your company captures a reasonable share of the market you’re describing, the outcome could be a hundred-million-dollar business. That means the number you show needs to be large — but it also needs to be credible.
Make your market sizing rigorous and bottoms-up rather than top-down. A top-down TAM pulled from a market research report (“the global HR software market is $45 billion”) signals that you don’t actually understand your customer. A bottoms-up calculation — “there are 180,000 independent insurance adjusters in the US, each filing an average of 400 claims per year, and we charge $3 per claim” — signals that you’ve talked to customers, you understand the unit economics, and you’ve done the math. That’s the version that lands.
Slide 4: Solution
The solution slide comes after the problem and market for a reason. By the time investors reach it, they should already be convinced that the problem is real and the market is worth pursuing. Now they want to know: how does your product actually fix this?
Keep this slide tight. Show the product — a screenshot, a workflow diagram, or a before-and-after view — rather than describing it in prose. Your solution description should make two things clear: what specifically your product does, and why that approach is meaningfully different from what exists today. The differentiation doesn’t have to be technology; it can be distribution, pricing, or focus on a customer segment competitors have ignored. But it has to be real.
Slide 5: Traction
The traction slide is the pivot point of the entire deck. It is where the story shifts from “here is what we’re building” to “here is evidence that it works.” At seed stage, most investors are evaluating four things above all else: team, problem, timing, and traction signal — and even a small proof point such as a paying customer, strong retention, or a notable pilot matters enormously.
The cardinal rule of the traction slide is this: show quantitative metrics that signal genuine demand, not vanity metrics that signal activity. MRR, retention curves, week-over-week growth rate, net revenue retention, and pilot-to-paid conversion rates all tell investors that demand is real. Total app downloads, registered users, and social media followers tell them almost nothing. Investors have learned to discount these numbers precisely because so many founders lead with them to obscure the absence of actual revenue signal.
Your metrics at this stage are limited, so use what you have to show trajectory: how many customers you had three months ago versus now, what changed when you shipped a new feature, and why your churn dropped after you revised onboarding. Trajectory is what seeds conviction — not the absolute number, but the direction and rate of change.
Slide 6: Business Model
The business model slide answers one question: how does this company make money? It should cover your pricing model, the key revenue line, and any secondary revenue streams. It does not need to be a full P&L — that belongs in the financials slide. What it needs to show is that you have thought clearly about how value creation translates to captured revenue, and that the economics are coherent at scale.
Lay out the revenue engines and pricing that will drive cash flow. Map each go-to-market stage and the resources required so investors see concrete traction milestones. The most convincing business model slides also include a simple unit economics view: what does it cost to acquire a customer, and what is that customer worth over time? Even rough numbers at seed stage signal that you understand the levers of your business.
Slide 7: Go-to-Market
The go-to-market slide is where many seed decks go soft. Founders often describe a strategy that is too broad (“we’ll grow through content, SEO, partnerships, and enterprise sales”) and therefore impossible to evaluate. A good go-to-market slide does the opposite: it names the one or two channels where you have early evidence of traction, explains the unit economics of acquiring customers through those channels, and describes the sequencing of expansion as the business grows.
If you already have a distribution insight — a channel, a partnership, or a community where your target customer already congregates — lead with that. Earned distribution advantages are enormously valuable at seed stage because they compress the time and capital required to reach product-market fit.
Slide 8: Competition
The competition slide is not a 2x2 matrix where you conveniently occupy the top-right quadrant. Every investor has seen hundreds of those, and none of them are believed. What works instead is an honest framing: who else is solving this problem (including alternative approaches, not just direct competitors), what are those approaches’ meaningful weaknesses, and what is specifically different about your approach?
The best-performing decks tend to follow the same underlying logic: start with the problem, explain the solution, show the market, prove traction, and end with a credible raise — and the competition slide belongs in that arc as a proof point for differentiation, not as a marketing exercise. If you can name the customers you’ve won from a specific competitor, do it. Concrete evidence of competitive displacement is worth ten 2x2 matrices.
Slide 9: Team
Your seed stage pitch deck should show your conviction as a founder. You need to tell the investor why you’re the right person to build this, what makes this approach work, and what you see that others don’t.
The team slide answers one underlying question: why are these specific people the ones most likely to win in this market? The most compelling team slides do this by naming unfair advantages — domain expertise accumulated over a decade, a prior exit in the same vertical, or deep relationships with the customer base you’re targeting. Titles and university names are not advantages; they’re context. Specific, relevant achievements are what move the needle.
If your team has gaps — and at seed stage, most do — name them and explain how the capital will address them. Investors who find gaps on their own will worry; investors who see you’ve already identified the gaps will trust your self-awareness.
Slide 10: Financials
Investors know that seed-stage financials are projections built on assumptions, not track records. They are not expecting precision. What they are evaluating is whether your assumptions are grounded in reality, whether you understand the key drivers of your business, and whether the opportunity is large enough to justify venture returns if things go well.
Your financials slide should cover a three-year projection at minimum, with a simple revenue model, a path to gross margin improvement, and a view of your burn rate relative to the capital you are raising. Keep it to one or two slides. A dense spreadsheet screenshot signals that you do not know what matters; a clean chart with a few key numbers signals that you do.
Slide 11: Roadmap
The roadmap slide bridges your current traction to your future milestones. It shows investors where the company will be in 12 and 24 months if the round closes — not in terms of features shipped, but in terms of business outcomes achieved. Think revenue milestones, customer count benchmarks, and product capability thresholds that unlock the next phase of growth.
The roadmap also functions as implicit validation of your ask: if the milestones you describe are achievable with the capital you’re raising, your plan is credible. If the milestones require significantly more capital than you’re asking for, investors will notice the mismatch.
Slide 12: The Ask
The ask slide is the most underbuilt slide in the average seed deck. Founders either treat it as an afterthought — a single number floating on a white slide — or bury the key details in fine print. Neither approach works.
A strong ask slide specifies four things: the exact amount you’re raising, the deal structure (SAFE with a valuation cap, or a priced round with an implied valuation), how the capital will be deployed across 18 to 24 months of runway, and the specific milestone that positions you to raise your Series A. Being explicit about what you will use the seed funding to prove — clearly stating “we will use this capital to reach X milestone by Y date” — shows investors you understand what de-risking looks like even before the data exists.
Vague asks signal that you haven’t thought through your capital plan. A fundable ask sounds like: “We’re raising $2M to reach $1M ARR by Q1 2027.” An unfundable one sounds like: “We’re raising $2M to grow the team and expand.” The difference is not just in the words — it’s in whether investors can picture the specific value creation their capital is buying.
Design Discipline: One Claim Per Slide
Before you send this deck to anyone, apply a single test to every slide: what is the one claim this slide is making, and what is the one data point supporting it? If you can’t answer those two questions cleanly, the slide is doing too much.
Minimalist design is redefining pitch decks, offering startups a fresh way to communicate ideas with precision. Simplified slides with clear visuals are gaining traction for their ability to sharpen storytelling and enhance investor focus. This is not a design preference — it’s a cognitive one. The first four slides get 60% of total deck attention. Overloading early slides with text or secondary data points means the primary argument gets lost in noise precisely where it matters most.
Use a font size large enough to read on a phone screen. Most investors encounter a deck for the first time on mobile, often forwarded by a colleague or pulled up between meetings. If your key claim requires zooming in to read, it will not be read.
From a Strong Deck to a Funded Round
A well-structured seed round pitch deck is necessary but not sufficient. The deck earns you the right to have a conversation; the outreach determines whether that conversation ever happens. Early stage funding grew meaningfully in 2025, with seed deal sizes hitting record highs even as deal counts compressed. Founders preparing a deck in this environment need to recognize that conviction-level evidence in your slides earns disproportionate rewards. Building a focused investor target list before you start sending the deck also matters more in a concentrated market.
That concentration means spray-and-pray outreach is actively counterproductive. Sending a generic deck to 200 investors who don’t focus on your stage or sector doesn’t build pipeline — it builds a reputation for not doing your homework. The founders who close seed rounds efficiently are the ones who send fewer, better-targeted messages to investors with a demonstrated history of writing checks into their specific category.
That’s exactly where Rupert comes in. Once your deck is built, the work shifts to figuring out which investors are most likely to fund a company like yours — by stage, sector, check size, and portfolio fit — and reaching them with outreach that’s researched, personalized, and sequenced properly. Rupert’s experienced operators handle that entire process while founders retain complete visibility into every conversation and every investor relationship. The deck gets you to the table. The outreach gets investors to sit down.
Where Things Stand
The seed funding environment in the second half of 2026 is one of record headline numbers and severe concentration underneath them. US startups raised more than $400 billion in the first half of 2026, surpassing every previous full-year total on record — yet megadeals of $100 million or more accounted for the overwhelming majority of invested capital, and just twelve firms captured three-quarters of every dollar raised into venture funds. Q2 2026 set new highs for both venture dealmaking and exits, but the PitchBook-NVCA Venture Monitor is explicit that the recovery remains uneven. For seed-stage founders, the two-speed market is the operative reality: seed deal sizes hit record highs even as deal counts compressed, and large platforms are now writing seed checks alongside their growth funds, squeezing standalone seed vehicles. KPMG’s Q2 Venture Pulse flags early-stage deal activity as a critical watch area for H2 2026, with meaningful improvement contingent on IPO liquidity returning. The practical implication for any pitch deck going out right now is unchanged: proprietary traction, capital efficiency, and a defensible path to Series A are not differentiators — they are the entry ticket.
See Related below for more on this topic.
See Sources below for the references behind this article.