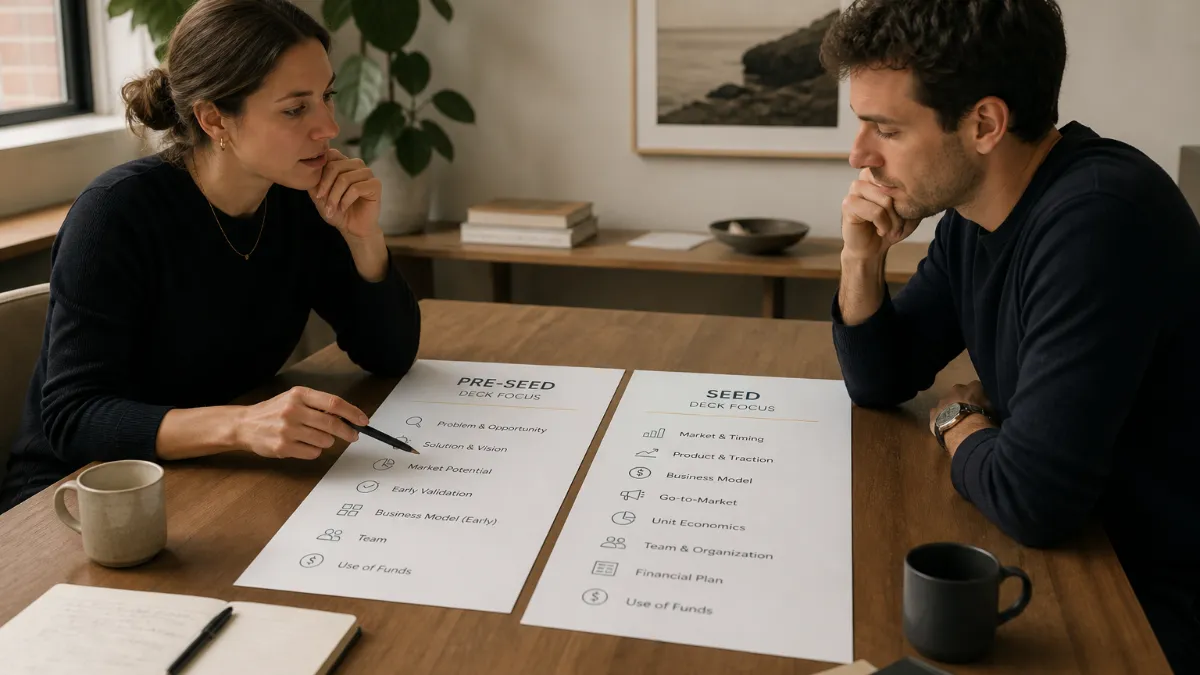
Most founders discover the mismatch the hard way: they send a deck they spent weeks refining, the investor replies with a polite pass, and the feedback — if it comes at all — is vague enough to be useless. The deck wasn’t bad. It was just built for the wrong stage. Pre-seed and seed pitch decks share most of the same slide titles — problem, solution, market, team, ask — but what sits behind those titles is entirely different. The evidence standard changes. The narrative logic changes. The slide that carries the most weight changes. Understanding exactly how is the difference between a deck that earns meetings and one that quietly filters you out.
The Core Distinction: Thesis vs. Proof
Pre-seed is vision; seed is proof. Pre-seed decks sell the founder and the problem. Seed decks sell the early product-market fit and the traction. That one sentence contains most of what you need to know, but the practical implications ripple through every slide in your deck.
When you are at the pre-seed stage, your company is an experiment. The product likely does not exist yet. You might have templates to guide you, but you lack hard performance data. The investor is betting on your unique insight into the market. They are answering one question: Can this team build version one? That is a fundamentally different question from what a seed investor asks, which is closer to: Does this thing actually work, and is the market responding?
At pre-seed, investors are buying into three things: the severity of the problem you’ve identified, the elegance of your proposed solution, and your credibility as the person to pull it off. Credibility here is almost entirely qualitative — it lives in the team slide, in your problem framing, and in the specificity of your insight. At seed, credibility shifts to quantitative: the data in your traction slide either supports the thesis or it doesn’t.
Slide Structure: Similar Titles, Different Substance
The broad structure of both decks looks nearly identical on a whiteboard. Both include a problem slide, a solution slide, a market slide, a team slide, and an ask. Most founders fail to raise their targeted rounds because they do not understand the functional differences between a seed vs pre-seed pitch deck. They recycle the same ten slides, update a few charts, and expect a bigger check. That approach burns runway. You need to understand exactly what investors expect at each stage. Your narrative, your data, and your design must align with the specific risk profile of the round you are raising.
Pre-Seed: Lead With the Problem, Not the Product
Most successful pre-seed decks fall in the 10–14 slide range. YC’s recommended structure uses 10 slides, and analysis of over 100 funded decks from 2024–2025 confirms this range as the sweet spot. Going under 8 usually means you’ve skipped something important. Going over 15 usually means you’re including seed-stage content that doesn’t belong yet.
The sequencing of a pre-seed deck prioritizes problem and context above everything else. The problem slide should present a specific, felt pain point — not a market trend, but a moment. The best problem slides describe a scene a real person is stuck in right now. The “why now” slide is not optional at this stage: at pre-seed, 92% of successful decks worldwide have a why-now section, and investors back the founder before any metrics. This slide — explaining what regulatory, technological, or behavioral shift makes your solution possible and urgent today — is one of the most differentiating elements of a strong pre-seed deck.
Pre-seed relies almost entirely on how well you communicate the opportunity. Most pre-seed rejections happen in the first three slides. Investors decide whether to keep reading based on problem clarity and solution uniqueness. That means your opening slides must do the heavy lifting. You are not presenting evidence of a working business; you are presenting evidence that the problem is real, painful, and large enough to matter.
Seed: Lead With Your Strongest Metric
A seed deck covers more ground, and its logic runs in the opposite direction. Where a pre-seed deck builds from problem to solution to plausibility, a seed deck often leads with traction — the strongest metric the company has — and then works backward to explain why that number makes sense. According to DocSend’s 2025 Pitch Deck Report, investors spend 3x longer on the traction slide than any other page in a seed deck — and 76% of ‘no’ decisions cite weak traction as the reason. That asymmetry should shape every structural decision you make when building a seed deck.
The seed market has bifurcated. If you have early product-market fit signals — $50K–$200K ARR, strong week-1 retention, or a credible enterprise pilot — you can raise a $3–4M seed at a $15M post-money without much trouble. If you have a prototype and a vision, you are competing in a much harder pool. This bifurcation is why sending a pre-seed narrative to a seed investor is so costly: it signals immediately that you may not have crossed the threshold they’re looking for.
Seed decks typically run 10–14 slides, and the additional slides compared to a pre-seed deck are almost always justified by deeper traction, unit economics, and go-to-market specificity. A growing emphasis on data-driven storytelling means that metrics and data visualization are no longer optional; they are essential tools for building investor confidence. By presenting key metrics in a visually compelling way, startups can substantiate their claims and demonstrate market potential effectively.
The Traction Slide vs. the Validation Slide
This is the single most concrete structural difference between the two decks, and it is also the most misunderstood. At pre-seed, you almost certainly don’t have the data to fill a seed-style traction slide. Pre-seed decks emphasize vision, founder–market fit, and early product demos over revenue metrics. Most successful startups at this stage don’t have meaningful traction yet — and investors know that. Rather than leaving the slide empty or padding it with proxies that feel thin, reframe it entirely as a validation slide. This is where you present the demand signals you have gathered: customer discovery interviews, waitlist numbers, pilot letters of intent, design-partner commitments, or early engagement data from an alpha. The company typically has evidence of real demand — like interviews, waitlists, or letters of intent — rather than hard performance metrics. The goal is to prove the problem is real and that people want a solution, not to simulate revenue you don’t have.
At seed, the validation slide is replaced by hard data. What investors expect includes a working product (not a prototype), early traction ($5K–$50K MRR for SaaS, 50–500 users for consumer, 5–15 customers for enterprise), retention signals, founder-market fit, and a plausible path to Series A metrics. Early traction benchmarks are $5K–$50K MRR for SaaS and 50–500 users for consumer, with D30 retention above 25% for consumer and logo retention above 85% for SaaS.
For a seed-stage company, 10–20% month-over-month growth is the target. Anything less suggests you haven’t found a repeatable growth playbook yet.
Seed-stage traction in 2025 isn’t about ticking boxes on a universal scorecard — it’s about showing that your growth is real and repeatable. The benchmarks differ across SaaS, consumer, social, marketplaces, biotech, and deep tech, but the through-line is the same: investors want confidence that your early momentum can compound into something much bigger.
The Team Slide: When It Peaks and When It Recedes
The team slide is the clearest indicator of which round you’re raising — not because the slide looks different, but because of how much weight it carries. At pre-seed, investors are primarily betting on your ability to execute. The team slide matters more at this stage than at any other. Specifically, what investors are looking for is founder-market fit: evidence that you have the domain expertise, technical depth, or lived experience that maps directly to the problem you’ve identified. Before a product exists, the team is the thesis. Every other slide in the deck is context for the bet investors are placing on you personally.
At seed, the dynamic shifts. Team credibility is assumed — if you’ve built something that users are paying for and coming back to, you’ve already demonstrated the ability to execute. The team slide also shifts at seed: investors want early sales and customer success leadership, not just founders. The team slide becomes about showing that you’re building the right organization to scale what you’ve started, not proving that you’re capable of starting at all.
The practical consequence: founders raising pre-seed who bury their team slide near the end of the deck are making a structural mistake. At pre-seed, moving the team slide to position two or three is common advice from reviewers. Founders raising seed who open their deck with a lengthy team section are signaling the wrong priority — they should be opening with the metric that proves the business is working.
The Financial Slide: What Level of Detail Is Expected
This is another area where founders routinely over-build at pre-seed and under-build at seed. At pre-seed, you should have a financial model — but it should focus on your key assumptions, unit economics, and cash burn for the next 12–18 months, not a detailed five-year forecast. In the deck itself, one summary slide is enough. The full model goes in your data room. Investors know long-term projections at pre-seed are speculative; they’re using your model to test operational discipline, not predict revenue. A three-year revenue model with fabricated precision actively hurts you at this stage — it signals either naivety about what investors value or a misunderstanding of where your company actually is.
At seed, the financial slide gains more weight, though it still shouldn’t dominate the deck. Investors want to see that you understand your unit economics, that you have a clear view of burn, and that you can articulate what the seed capital will achieve in specific terms. Founders should present startup metrics in a pitch deck by choosing two to three core traction metrics, showing them visually, and tying each number to the business story. Investors do not want a spreadsheet pasted into a slide. They want to know what is growing, why it is growing, whether the growth can continue, and how the next round of capital will improve the numbers.
The Cost of Getting This Wrong
Sending the wrong deck to the wrong stage of investor isn’t just inefficient — it actively signals something unflattering about your self-awareness. Most founders fail to raise their targeted rounds because they do not understand the functional differences between a seed vs pre-seed pitch deck. They recycle the same ten slides, update a few charts, and expect a bigger check. That approach burns runway. A pre-seed narrative in front of a seed investor reads as an admission that you haven’t hit the traction bar they need. A seed-style deck — heavy on metrics, light on problem framing — sent to a pre-seed investor signals that you don’t understand what they’re actually evaluating at this stage. Either mismatch ends the conversation quickly.
In 2024, pre-seed startups in the US raised $4 billion through more than 25,000 convertible instruments, with the median round size settling at $700K. The median pre-seed check sits between $50K and $250K per investor. You’re typically raising from 8–15 investors, which means you’ll pitch this deck 30–50 times before you’re done. With that much repetition at stake, a deck that’s structurally misaligned with investor expectations doesn’t just lose one meeting — it systematically burns through your investor pipeline.
Different investors have different thresholds. Some seed VCs invest at $20K MRR; others want $100K+. Targeting investors whose expectations match your current metrics dramatically improves conversion rates. The implication is direct: knowing which deck to build is necessary, but it’s only half the problem. The other half is making sure that deck reaches investors whose stage expectations actually match where you are.
Building the Right Deck for the Right Investors
The good news is that building the right deck is not mysterious once you understand the logic. Pre-seed decks earn meetings by proving founder conviction and problem depth. Seed decks earn meetings by proving that the market is responding. Both rely on honesty about what evidence you actually have — and both suffer from founders trying to appear more advanced than they are.
Build your pre-seed deck around the problem, the insight, and the team. Frame whatever evidence you have as validation, not traction, and don’t pretend the absence of revenue is a secret. Build your seed deck around your strongest metric, lead with it, and make the rest of the deck the story of why that metric is going to keep growing. In both cases, every slide should feel like it was written for the investor who is reading it — not for the investor you hope to have in eighteen months.
Knowing which deck to build is only part of the challenge. The other part is directing that deck to the investors who are actually in the market for what you’re selling at the stage you’re at. Rupert handles the research and personalized outreach that connects founders with the right investors at the right moment — not a blast to a generic list, but a disciplined, transparent process where founders retain full visibility into every conversation and every relationship being built on their behalf.
If your deck is ready but your pipeline isn’t, the problem isn’t the slides — it’s who’s seeing them. Rupert helps founders solve the second half of the equation: identifying the specific investors whose stage criteria, sector focus, and recent portfolio activity align with where you are right now, and reaching them in a way that earns a real response.
Where Things Stand
The early-stage funding environment in H1 2026 reflects a market that has bifurcated sharply between founders with evidence and those without. Carta’s Q2 2026 State of Pre-Seed report confirms 2026 is already slightly ahead of 2025 in total pre-seed cash invested during the first half of the year, with roughly 3,000 U.S. startups raising over $2.3 billion in Q1 alone. But the headline recovery masks a structural barbell: average instrument size hit a record $276,000 in Q2 as more dollars flowed into fewer companies, while the typical pre-seed round is simultaneously getting smaller. AI is the primary driver — capturing 49% of all pre-seed dollars in H1 2026 — and at the 90th percentile, SAFE valuation caps on rounds above $2.5M are reaching $100 million. The conversion rate from seed to Series A has meanwhile dropped from roughly 50% to 38%. For founders, the practical implication is unchanged but more acute: a pre-seed pitch deck must now navigate a market where capital concentration is accelerating, AI commands a valuation premium that non-AI decks cannot assume, and geographic competition is shifting — Texas overtook New York for pre-seed investment in Q2 2026.
See Related below for more on this topic.
See Sources below for the references behind this article.