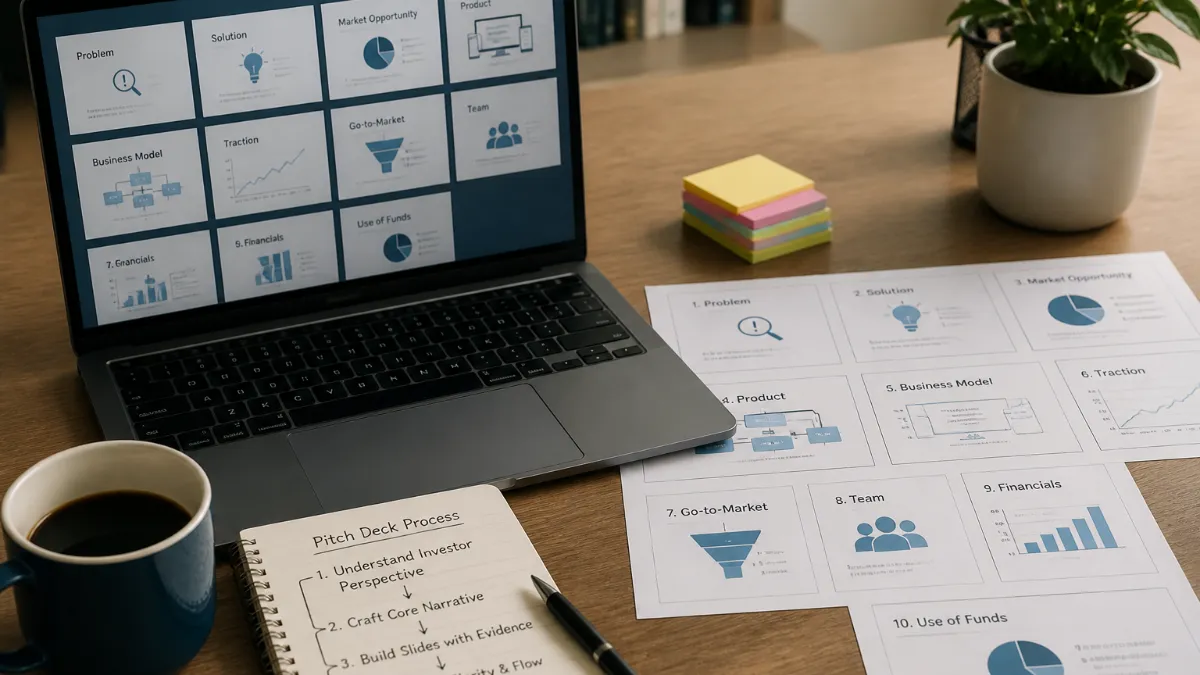
A startup pitch deck template gives you the structure. What it cannot give you is the substance — and that distinction is the difference between a deck that earns meetings and one that gets quietly archived after a two-minute scroll.
Most founders treat the template as the deliverable. They download a well-designed file, drop their company name into the title slide, fill each placeholder with whatever seems plausible, and ship it. The resulting deck looks complete. But investors reading it can feel the difference between a narrative built from first principles and a template that has been populated in an afternoon. Before you touch a single slide, there is one thing to do first.
Start With the Investment Thesis, Not the Slides
The most durable advice for completing any pitch deck template is also the most consistently ignored: write your investment thesis as a single paragraph before you open the file. Not a tagline, not a mission statement — a paragraph that answers the problem you are solving, why the moment for solving it is right now, and why your team is the one that will win. Every slide you fill in afterward should serve that paragraph. If a slide doesn’t, either the slide needs to be cut or the thesis needs to be sharpened.
Your opening slides should make the opportunity easy to understand. Avoid complicated explanations and unnecessary industry terminology — investors should quickly grasp what you do, who you serve, and why the market opportunity matters. That clarity starts on paper, not in a design tool. Writing the thesis forces you to confront the gaps in your argument before an investor does it for you in a first meeting. Founders who skip this step tend to build decks that are visually coherent but logically scattered — each slide looks fine in isolation, but the cumulative case doesn’t land.
Slide Order Is a Strategic Choice, Not a Default
Most templates ship with a default order: problem, solution, market, business model, traction, team, financials, ask. That order works, but it is a suggestion, not a rule. The right structure depends on the stage of your raise and the strength of your evidence.
If you are raising pre-seed, lead with team and vision. At this stage, investors are essentially betting on people and a thesis. Traction is thin by definition, and forcing it to the front of the deck highlights the weakness rather than the opportunity. Put your strongest proof of founder-market fit early — domain expertise, prior outcomes, proprietary insight into the problem — and let traction support that story rather than anchor it.
If you are raising a seed round, the calculus flips. If you have achieved product-market fit, gathered user or customer metrics, or generated revenue, make sure to share these as proof of concept — key metrics that demonstrate traction, such as user growth, engagement rates, or revenue figures, help build investor confidence in your product’s potential and market demand. Front-loading that evidence signals that the company has moved beyond pure hypothesis. Investors at the seed stage have seen enough decks to know when traction is genuine and when it has been staged to fill a template box.
The best pitch deck structure in 2026 still looks disciplined rather than creative for its own sake — founders often hurt themselves by adding too many slides, changing the order unnecessarily, or forcing in extra material that belongs in follow-up conversations. Resist the urge to add slides because the template had a placeholder for them. Every slide that doesn’t advance the argument costs attention you can’t afford.
Each Placeholder Is a Question — Answer It With Evidence
The fill-in-the-blank prompts inside a template are not instructions to write copy. They are investor questions in disguise. The problem slide prompt (“describe the problem your company solves”) is really asking: Is this problem real, painful, and underserved? The solution prompt is asking: Does this product actually solve it better than what exists today? The team prompt is asking: Why are these specific people the ones who will win?
The problem slide is the most critical in your deck. If investors don’t believe the problem is real and painful, nothing else in the presentation will matter to them. Founders who respond to that prompt with market-research language (“studies show that X is a growing problem”) miss the point. The answer needs to be grounded in something concrete — a customer quote, a retention statistic, a frequency-of-occurrence data point. The more specific the evidence, the more credible the problem.
The same logic applies to the competition slide. Be sure to outline the current competition but focus on your defensible moat — investors want to know if your advantage comes from network effects, data superiority, or switching costs, rather than just feature differences. A 2x2 matrix with your logo in the top-right corner tells an experienced investor nothing. A precise articulation of why your distribution, data, or structural position is hard to replicate tells them a great deal.
The Three Slides Where Template Decks Most Often Break Down
Market size, business model, and financial projections are where well-intentioned template decks collapse under scrutiny. These are the slides where founders are most tempted to reach for comfortable numbers and optimistic shapes rather than working through the logic.
On the market slide, show investors how large the opportunity is by using three numbers: TAM (total addressable market), SAM (serviceable addressable market), and SOM — your realistic share of that market over the next three to five years. The problem is that founders routinely pull a large TAM from an industry report and present it without building up to it from their own unit economics. Investors have seen this pattern thousands of times. A bottoms-up market analysis — we sell to X type of buyer, there are Y of them, they pay Z — is far more persuasive than a top-down figure sourced from a consulting firm’s market forecast.
Investors want to understand how your startup makes money and how that model can scale — clearly explain your pricing structure, revenue streams, customer acquisition strategy, and key economic drivers. If your business model slide is a bullet list of revenue streams without unit economics attached, it raises more questions than it answers. What does it cost to acquire a customer? What is the lifetime value? How does the margin profile change at scale? These are the questions the slide should pre-empt.
Financial projections are the slide most prone to wishful thinking. In the current environment, investors prioritize sustainable unit economics — like CAC/LTV and Net Dollar Retention — alongside growth. A hockey-stick revenue curve unmoored from hiring plans, customer acquisition assumptions, and churn rates signals to investors that the founder hasn’t thought through the mechanics of growth. Ground every projection in a named assumption. If revenue triples in year two, what specifically causes that — headcount, a new channel, a price increase? Make the logic visible.
The Cold-Read Test: How to Know When the Deck Is Actually Ready
Completing a template is not the same as completing a deck. Once every slide is filled in, the real work is stress-testing whether the narrative holds together for someone reading it cold — without you in the room to explain it.
Investor attention has declined sharply, with seed-stage founders now getting less than two minutes on a first-pass review — less time than a YouTube Short. That is not a figure to dismiss. It means the investment case must be graspable in a scroll, not a careful read. The cold-read test is simple: set a 90-second timer, open the deck on a device you don’t normally use, and scroll through it as a stranger would. If the core argument — what you do, why it matters, why now, why you — is not clear within that window, the deck is not ready. Do not move to design optimization. Move back to narrative tightening.
AI tools have made it easier to generate slides, which means the bar for what counts as “good enough” has risen dramatically — a deck that would have stood out a few years ago now looks generic. The cold-read test filters out generic. If a knowledgeable friend reading the deck comes away with a clear picture of the company and a reason to believe in it, the substance is there. Design refinement can follow.
From a Completed Deck to the Right Investors
A polished, investor-ready deck is necessary — but it is only the beginning of the work. The harder challenge is identifying which investors are actually likely to fund a company at your stage, in your sector, with your specific profile, and then reaching them with outreach that earns a genuine response rather than a polite pass.
The 2026 funding market has a clear pattern: fewer companies receive the largest cheques, while early-stage investors inspect evidence much more closely. Seed capital still exists, but founders with a vague deck and a generic AI layer are competing against teams with customer revenue, specialist knowledge, and a credible route to a later financing round or acquisition. That competitive context makes investor targeting as important as the deck itself — sending the right material to the wrong investors wastes runway and, more expensively, time.
This is where many founders hit a structural problem. Running a disciplined outreach campaign — researching investors, personalizing each message, tracking conversations, and maintaining the pipeline — is itself a part-time job. It competes directly with building the company. Rupert handles that work on founders’ behalf: experienced operators research and identify the investors most likely to convert, run personalized outreach campaigns, and give founders complete visibility into every conversation and every relationship — without taking the process out of the founder’s hands. The deck you have built gets in front of people who are actually positioned to act on it.
The 12 Slides of a Pitch Deck Template, in Order
Slide 1: Cover
The cover slide is not decoration. It is the first five seconds of the investor’s experience. It should carry your company name, a single one-line descriptor of what you do, and nothing else. The descriptor should be specific enough that an investor immediately knows the category and customer — not “AI-powered workflow automation” but “AI that writes and files insurance claims for independent adjusters.” Specificity signals founder clarity. Vagueness signals hand-waving.
Slide 2: Problem
The problem slide is where the deck either pulls investors in or loses them. Its job is to make investors feel the pain — not acknowledge it abstractly, but viscerally understand why a particular group of people is suffering right now without your solution.
The most common failure here is describing a problem that is technically real but emotionally inert: “The market for X is inefficient.” That is not a problem; that is an observation. A strong problem slide names a specific person, describes what their day looks like today without your solution, and quantifies the cost (in time, money, or lost opportunity) of that pain. If investors have worked in or around your industry, this slide should make them nod. If they haven’t, it should give them enough context to imagine the pain clearly.
Slide 3: Market Size
Demonstrating market potential is critical for securing seed funding. Highlight the size of your target market, growth trends, and any gaps your business can fill. This information reassures investors that your startup has room to thrive and scale.
The market slide has one job: make the opportunity feel worth a fund-returning bet. Venture investors need to believe that if your company captures a reasonable share of the market you’re describing, the outcome could be a hundred-million-dollar business. That means the number you show needs to be large — but it also needs to be credible.
Make your market sizing rigorous and bottoms-up rather than top-down. A top-down TAM pulled from a market research report (“the global HR software market is $45 billion”) signals that you don’t actually understand your customer. A bottoms-up calculation — “there are 180,000 independent insurance adjusters in the US, each filing an average of 400 claims per year, and we charge $3 per claim” — signals that you’ve talked to customers, you understand the unit economics, and you’ve done the math. That’s the version that lands.
Slide 4: Solution
The solution slide comes after the problem and market for a reason. By the time investors reach it, they should already be convinced that the problem is real and the market is worth pursuing. Now they want to know: how does your product actually fix this?
Keep this slide tight. Show the product (a screenshot, a workflow diagram, or a before-and-after view) rather than describing it in prose. Your solution description should make two things clear: what specifically your product does, and why that approach is meaningfully different from what exists today. The differentiation doesn’t have to be technology; it can be distribution, pricing, or focus on a customer segment competitors have ignored. But it has to be real.
Slide 5: Traction
The traction slide is the pivot point of the entire deck. It is where the story shifts from “here is what we’re building” to “here is evidence that it works.” At seed stage, most investors are evaluating four things above all else: team, problem, timing, and traction signal — and even a small proof point such as a paying customer, strong retention, or a notable pilot matters enormously.
The cardinal rule of the traction slide is this: show quantitative metrics that signal genuine demand, not vanity metrics that signal activity. MRR, retention curves, week-over-week growth rate, net revenue retention, and pilot-to-paid conversion rates all tell investors that demand is real. Total app downloads, registered users, and social media followers tell them almost nothing. Investors have learned to discount these numbers precisely because so many founders lead with them to obscure the absence of actual revenue signal.
Your metrics at this stage are limited, so use what you have to show trajectory: how many customers you had three months ago versus now, what changed when you shipped a new feature, and why your churn dropped after you revised onboarding. Trajectory is what seeds conviction — not the absolute number, but the direction and rate of change.
Slide 6: Business Model
The business model slide answers one question: how does this company make money? It should cover your pricing model, the key revenue line, and any secondary revenue streams. It does not need to be a full P&L — that belongs in the financials slide. What it needs to show is that you have thought clearly about how value creation translates to captured revenue, and that the economics are coherent at scale.
Lay out the revenue engines and pricing that will drive cash flow. Map each go-to-market stage and the resources required so investors see concrete traction milestones. The most convincing business model slides also include a simple unit economics view: what does it cost to acquire a customer, and what is that customer worth over time? Even rough numbers at seed stage signal that you understand the levers of your business.
Slide 7: Go-to-Market
The go-to-market slide is where many seed decks go soft. Founders often describe a strategy that is too broad (“we’ll grow through content, SEO, partnerships, and enterprise sales”) and therefore impossible to evaluate. A good go-to-market slide does the opposite: it names the one or two channels where you have early evidence of traction, explains the unit economics of acquiring customers through those channels, and describes the sequencing of expansion as the business grows.
If you already have a distribution insight — a channel, a partnership, or a community where your target customer already congregates — lead with that. Earned distribution advantages are enormously valuable at seed stage because they compress the time and capital required to reach product-market fit.
Slide 8: Competition
The competition slide is not a 2x2 matrix where you conveniently occupy the top-right quadrant. Every investor has seen hundreds of those, and none of them are believed. What works instead is an honest framing: who else is solving this problem (including alternative approaches, not just direct competitors), what are those approaches’ meaningful weaknesses, and what is specifically different about your approach?
The best-performing decks tend to follow the same underlying logic: start with the problem, explain the solution, show the market, prove traction, and end with a credible raise — and the competition slide belongs in that arc as a proof point for differentiation, not as a marketing exercise. If you can name the customers you’ve won from a specific competitor, do it. Concrete evidence of competitive displacement is worth ten 2x2 matrices.
Slide 9: Team
Your seed stage pitch deck should show your conviction as a founder. You need to tell the investor why you’re the right person to build this, what makes this approach work, and what you see that others don’t.
The team slide answers one underlying question: why are these specific people the ones most likely to win in this market? The most compelling team slides do this by naming unfair advantages — domain expertise accumulated over a decade, a prior exit in the same vertical, or deep relationships with the customer base you’re targeting. Titles and university names are not advantages; they’re context. Specific, relevant achievements are what move the needle.
If your team has gaps (and at seed stage, most do) name them and explain how the capital will address them. Investors who find gaps on their own will worry; investors who see you’ve already identified the gaps will trust your self-awareness.
Slide 10: Financials
Investors know that seed-stage financials are projections built on assumptions, not track records. They are not expecting precision. What they are evaluating is whether your assumptions are grounded in reality, whether you understand the key drivers of your business, and whether the opportunity is large enough to justify venture returns if things go well.
Your financials slide should cover a three-year projection at minimum, with a simple revenue model, a path to gross margin improvement, and a view of your burn rate relative to the capital you are raising. Keep it to one or two slides. A dense spreadsheet screenshot signals that you do not know what matters; a clean chart with a few key numbers signals that you do.
Slide 11: Roadmap
The roadmap slide bridges your current traction to your future milestones. It shows investors where the company will be in 12 and 24 months if the round closes — not in terms of features shipped, but in terms of business outcomes achieved. Think revenue milestones, customer count benchmarks, and product capability thresholds that unlock the next phase of growth.
The roadmap also functions as implicit validation of your ask: if the milestones you describe are achievable with the capital you’re raising, your plan is credible. If the milestones require significantly more capital than you’re asking for, investors will notice the mismatch.
Slide 12: The Ask
The ask slide is the most underbuilt slide in the average seed deck. Founders either treat it as an afterthought — a single number floating on a white slide — or bury the key details in fine print. Neither approach works.
A strong ask slide specifies four things: the exact amount you’re raising, the deal structure (SAFE with a valuation cap, or a priced round with an implied valuation), how the capital will be deployed across 18 to 24 months of runway, and the specific milestone that positions you to raise your Series A. Being explicit about what you will use the seed funding to prove — clearly stating “we will use this capital to reach X milestone by Y date” — shows investors you understand what de-risking looks like even before the data exists.
Vague asks signal that you haven’t thought through your capital plan. A fundable ask sounds like: “We’re raising $2M to reach $1M ARR by Q1 2027.” An unfundable one sounds like: “We’re raising $2M to grow the team and expand.” The difference is not just in the words — it’s in whether investors can picture the specific value creation their capital is buying.
Which Free Pitch Deck Templates Are Worth Using?
The Sequoia Capital Outline
The Sequoia Capital template as the firm publishes it today is 10 slides: company purpose, problem, solution, why now, market potential, competition and alternatives, business model, team, financials, and vision. It comes from Sequoia’s own “Writing a Business Plan” guide, and it has outlived nearly every deck fad that arrived after it. That longevity is not an accident. The framework reflects how experienced VCs move through a pitch mentally, and using it signals that you understand that logic.
The template is not a design system. It is an argument in a fixed order: here is a broken thing, here is why it is breakable now, here is the size of the prize, here is why we are the ones who take it. Founders who treat it as a visual formatting guide miss the point. The ten slides are a reasoning structure, and the quality of the reasoning matters far more than the slide design.
The Y Combinator Minimal Format
The Y Combinator approach to pitch decks is similarly free, similarly brief, and similarly investor-recognized. YC’s guidance consistently pushes founders toward a stripped-down deck that leads with clarity: what you make, who uses it, why it matters, and what the numbers say. The format is deliberately minimal because YC has observed thousands of decks and found that excess length usually signals a weak argument, not a strong one. Founders applying to YC or pitching YC-affiliated investors will find the minimal format directly relevant; founders pitching other institutional funds will find it a useful discipline regardless.
Canva, Google Slides, and Pitch.com
Canva has a generous free tier with deck templates and a Pro tier with deeper features, backed by the largest and most approachable template library and a design surface most people already know. It is the safe default when money is tight and the argument is roughly in place: pick a template, drop in content, ship. Google Slides works the same way — free, shareable, and requiring no software installation on the recipient’s end. Pitch.com offers a free tier with collaboration features suited to teams building a deck together.
None of these platforms provide fundraising-specific slide guidance. They provide visual containers. That is genuinely useful — starting from a well-proportioned blank canvas is better than starting from nothing — but the founder still needs to bring the argument.
Template vs. Custom Design: When Design Earns Its Cost
The calculus changes materially at Series A and beyond. By the time a company is raising institutional capital, the investor audience is larger, more competitive, and more attuned to the signals embedded in presentation quality. Series A investors are pattern-matching against dozens of deals they have seen. They want to find key metrics quickly. A deck that looks generic — even if the content is strong — can create unnecessary friction at this stage because design is read as a proxy for brand maturity and operational discipline.
A template provides a structure, while a custom pitch deck is built around a specific company and investment story. Custom pitch deck design focuses on investor messaging, fundraising strategy, positioning, and presenting information in a way that helps investors evaluate the opportunity more quickly. At Series A, where the difference between a term sheet and a pass often comes down to marginal conviction, a deck that feels considered and intentional can close that gap.
There is also a practical signal embedded in design quality at growth stage. When a company is raising $10M or more, the quality of every external communication becomes part of the investor’s assessment of the team’s judgment. A deck that looks like it was assembled over a weekend can undercut confidence in the company’s ability to attract talent, manage a brand, and operate at scale. Custom design, done well, communicates that the founders understand their audience.
The Sequencing Rule That Most Founders Ignore
The single most important rule in this entire debate is one that applies regardless of which path you choose: never invest in custom design until the narrative is fully locked. This sounds obvious. It almost never happens in practice. Founders commission custom design, receive a polished deck, and then discover through investor meetings that the problem framing is off, the market sizing is unconvincing, or the team story needs to be restructured. Every one of those changes means expensive redesign work and weeks of delay. The narrative — the argument the deck makes from slide one to the final ask — must survive investor scrutiny before it goes to a designer.
While slide deck templates provide excellent starting points, authentic pitch deck design requires significant customization. Templates establish structural frameworks and design systems, but a unique value proposition demands unique visual expression. The right order is: lock the structure with a template, pressure-test the narrative with advisors and early investor conversations, then — and only then — invest in custom design if the stage and competitive context justify it.
Where Things Stand
Global venture funding hit a record $510 billion in the first half of 2026, but fewer startups are getting funded overall while the strongest raise larger rounds. Early-stage investors are inspecting evidence more closely, so filling in a template with bottom-up logic and real proof on every slide matters more than ever.