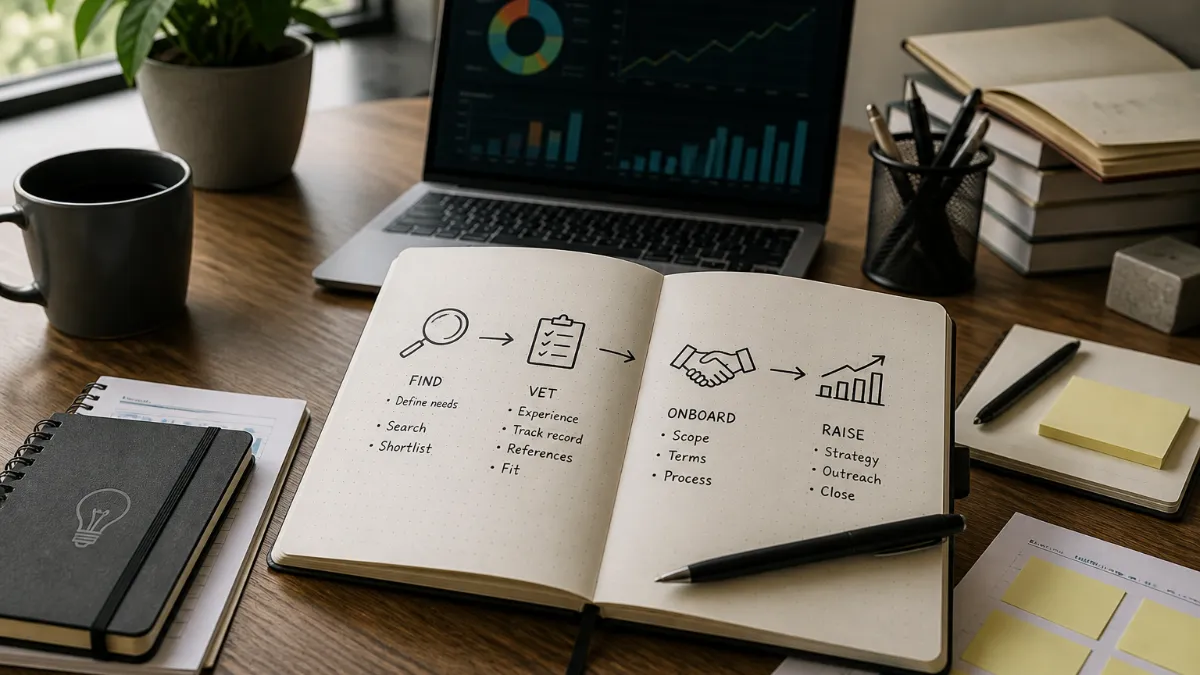
Hiring a fundraising consultant feels like a shortcut. It often isn’t — and the difference between an engagement that closes your round and one that burns through retainer fees while producing polished-looking activity comes down to a few decisions you make before you sign anything. This guide walks through each of them in order, from defining what you actually need through the onboarding phase where most bad engagements reveal themselves. A consultant is one of several options covered in our guide to capital raising services for startups.
Start by Defining the Scope of Help You Actually Need
The most common mistake founders make before hiring a startup fundraising consultant is conflating several distinct types of work into a single mandate. Investor targeting and outreach management is a fundamentally different service from pitch deck refinement, financial modeling, or narrative coaching. Each requires different expertise, a different fee structure, and a different kind of person.
If you have a compelling deck and a clear story but no bandwidth to research which investors actually fund companies like yours — and no process for managing a pipeline of 60 to 100 conversations — what you need is an outreach specialist. If your deck is unclear and your narrative is unformed, what you need first is a positioning advisor. Hiring a generalist to do both rarely produces the outcome of hiring the right specialist for the job you actually have.
Before you start evaluating consultants, answer three questions honestly. Do you have a pitch that earns a second meeting, or does the positioning still need work? Do you have a way to identify investors who fund companies at your stage, sector, and geography — and do you have the time to systematically reach them? And do you have a process for tracking conversations, following up consistently, and maintaining momentum across a four-to-six-month raise? If the answer to the first question is no, fix that before hiring outreach help. If the answer to the second and third is no, a capital raising consultant is the right investment.
How to Vet a Fundraising Consultant Before You Sign
Once you know what you need, the evaluation process has three pillars, and none of them are negotiable.
Active Investor Relationships, Not Just Database Access
The first is genuine investor relationships. A consultant with real relationships can tell you specifically which partners at which funds they’ve worked with in the last eighteen months and will offer founder references without hesitation. A consultant relying on a database subscription will describe their “network” in aggregate terms — thousands of investors, a proprietary platform, high match rates — without naming a single fund and a single partner who took their call. Push on this directly. Ask who made the introduction on their last three closed rounds. If they can’t answer clearly, move on.
This distinction matters because warm introductions and relationship-based outreach convert at meaningfully higher rates than cold or semi-cold database sends. The investor is not reading your email — they are reading an email from someone they trust, vouching for a company they’ve vetted. A consultant who cannot manufacture that signal is, at best, helping you manage an email campaign.
A Track Record at Your Stage and Sector
The second pillar is a verifiable track record at your stage and sector. A consultant who has closed a dozen Series B rounds in enterprise SaaS is not necessarily equipped to run a pre-seed raise in climate hardware, and vice versa. Investor networks, round dynamics, and diligence expectations vary significantly across these contexts.
Ask for a list of the last five to ten rounds they’ve supported. Confirm the stage, the sector, the capital raised, and how long the process took. Then ask to speak with two or three of those founders — specifically founders who went through a process similar to yours, not the firm’s most celebrated wins. Reference calls with comparable founders reveal far more than curated case studies.
Transparent Reporting Structure
The third pillar is reporting structure. You need to know exactly what is being sent to whom, in what format, on what timeline, and what the response rate has been. A consultant who cannot commit to showing you the investor target list before outreach begins, sharing every email thread as it happens, and providing a weekly pipeline summary is asking you to fund a process you cannot evaluate. That opacity is a structural problem, not a stylistic preference — it means you have no way to course-correct before momentum collapses.
Negotiate the Fee Structure Before You Sign
Fee conversations are uncomfortable for founders who are unfamiliar with how the market works, which makes them easy to defer. Don’t. The structure of the engagement determines whether your consultant is financially motivated to close your round or simply to execute activity.
There are three common models. Retainer-only engagements charge a fixed monthly fee regardless of outcome, which creates an incentive to maintain the engagement rather than close it. Success-fee-only arrangements charge a percentage of capital raised at close, typically between three and seven percent, which aligns incentives well but is rare at early stages because consultants bear all the execution cost with no guaranteed return. Hybrid models — a monthly retainer plus a reduced success fee — are the most common structure for Seed and Series A raises and tend to create the best balance of aligned incentives and execution quality.
Within any hybrid structure, two terms deserve particular attention. First, clarify whether retainer payments credit against the success fee at close. Some firms structure it this way — meaning the retainer you’ve paid during the engagement offsets what you owe at closing — while others treat them as independent. Second, understand how the tail period is defined. The tail period is the window after the engagement ends during which the consultant retains a success fee if a round closes with an investor they introduced. Tail periods of six to twelve months are standard; anything longer deserves pushback, and any investor introduced during the engagement should be documented clearly before the relationship terminates.
Also ask about carve-outs: investors you’ve already had conversations with, or who come through your own network independently of the engagement, should typically be excluded from the success fee. Get this in writing.
Red Flags That Disqualify a Consultant Immediately
Some things are not negotiable trade-offs. They are disqualifying.
Bulk outreach with no personalization. If the consultant’s outreach process involves sending the same templated message to hundreds of investors with no customization — no reference to the investor’s specific thesis, portfolio, or recent investments — you are paying to damage your own reputation. Investors talk to each other. Being known as a company that sends mass emails is worse than not reaching those investors at all.
Refusal to share the investor target list. If a consultant won’t show you which investors they plan to approach before the campaign begins, that is not a minor transparency issue — it is a fundamental conflict of interest. The target list is not proprietary to the consultant; it is your round, your company, and your future relationship with every investor on that list. You need to see it, approve it, and own a copy of it.
Vague deliverables. Any engagement that promises outcomes without specifying exactly what will be delivered, by when, and how it will be measured is not a professional service agreement — it is a retainer for effort. Deliverables should include a defined investor target list with rationale, an outreach cadence, a reporting format, and a clear definition of what constitutes a meaningful introduction.
No references from comparable founders. A consultant who cannot produce references from founders who raised at a similar stage and in a similar sector — not their best clients, but their representative clients — has not built the track record the engagement requires.
What a Rigorous Onboarding Phase Looks Like
If you’ve passed through the vetting and fee negotiation and signed an engagement letter, the onboarding phase is where you will learn whether the relationship is going to work. It is also where most bad engagements reveal themselves.
A rigorous consultant treats onboarding as a discovery process, not a formality. That means spending meaningful time understanding your company’s positioning before building an investor target list, because the target list is a direct function of how the story is framed. A company described as an AI infrastructure tool reaches a different investor than the same company described as an enterprise workflow platform — even if the underlying product is identical.
In practice, this phase should produce three concrete outputs: a positioning document that articulates why your company earns capital right now, an investor target list of 80 to 120 names with a written rationale for every investor on it, and an outreach template that personalizes the pitch at scale — customized by investor thesis, portfolio, and context, not just name and firm.
If the consultant skips the positioning work and goes straight to the target list, that is a signal worth noting. If the target list has no rationale — just names, firms, and contact data — that is a stronger signal. A database subscription plus email capacity is not a fundraising consultancy. A consultant who earns the engagement treats the first two weeks as an investment in the quality of everything that follows.
Check the Tail Period and Excluded Investors
The tail period — the window after the engagement ends during which the consultant can still claim a success fee — is one of the most overlooked clauses in any consulting agreement. Standard tail periods run six to twelve months. The critical detail is not the length; it is the carve-out list. Any investor you knew, had met, or had previously spoken with before the engagement began must be explicitly excluded by name. A vague “investors introduced by the client” exclusion is not sufficient protection.
This question matters especially for Seed founders who have been working their network informally before engaging a consultant. If your investor target list already includes people you have emailed, asked for a meeting, or discussed your company with at a conference, those investors should be documented as carve-outs before any contract is signed. Failing to do this creates a scenario where you close a round with an investor from your own network and still owe a success fee.
Confirm Who Owns the Investor Relationships
This is the single most important question on the list, and it is the one most founders forget to ask. Investment strategies are increasingly shifting toward higher-conviction portfolios, with firms allocating more capital per company and placing greater emphasis on long-term ownership — which means the investors you meet during your Seed raise are exactly the people you will need for your Series A, your Series B, and every strategic introduction in between. If a consultant retains relationship ownership after the engagement ends — controlling the contact database, the conversation history, or the warm-introduction access — they are extracting long-term value from a short-term engagement. That is a structural misalignment with your interests as a founder.
The correct answer is unambiguous: every investor contact, every email thread, every conversation record belongs to you from day one and remains yours after the engagement ends. Anything less is a form of relationship rent. A service that genuinely operates in a founder’s interest does not need to hold investor relationships as leverage. That is how Rupert is set up: investor replies come to you, and every relationship stays yours.
Where Things Stand
For founders raising seed and Series A rounds, the market feels selective: fewer deals, larger checks and conviction concentrated at the top. Investors increasingly decide on the conversation rather than the deck, including who is vouching for the founder and whether the process feels like a real round, which raises the bar for any consultant running outreach on a founder’s behalf.